The Senate Banking Committee voted 15-9 on Thursday to move forward on the CLARITY Act, a crypto market structure proposal that has been the subject of debate for a while now.
Nevertheless, just ahead of the vote, the Bank Policy Institute (BPI) put out a series of tweets on X about illicit crypto flows hitting $154 billion in 2025, adding another dimension to what was already an intensely debated topic on the extent of regulation in digital assets.
Bank Advocates Lean on Crime Data
The timing of BPI’s thread drew attention because lawmakers were simultaneously debating amendments tied to stablecoin yield restrictions and enforcement standards inside the CLARITY Act markup session.
According to data from Chainalysis that the institute shared, in 2025, illicit crypto addresses received $154 billion. This was a 162% year-over-year increase, driven largely by a 694% jump in value received by sanctioned entities.
Furthermore, the on-chain money laundering ecosystem grew from $10 billion in 2020 to over $82 billion in 2025, with stablecoins, primarily Tether (USDT), now accounting for 84% of all illicit transaction volume, displacing Bitcoin as the preferred payment method for criminals.
In a separate piece, the BPI argued that banks have spent decades staffing tens of thousands of AML employees while crypto companies have been largely exempt.
It said that the GENIUS Act imposed some obligations on US stablecoin issuers, but did not cover foreign issuers operating stateside. Tether, incorporated in El Salvador, sits outside that net.
The piece also cited the Islamic Revolutionary Guard Corps, whose crypto activity reportedly reached over $3 billion in 2025, representing roughly 50% of Iran’s total crypto ecosystem by Q4 of that year.
According to the BPI, unhosted wallets, cross-chain bridges, and mixers are “specifically designed to frustrate tracing and openly advertised as such.”
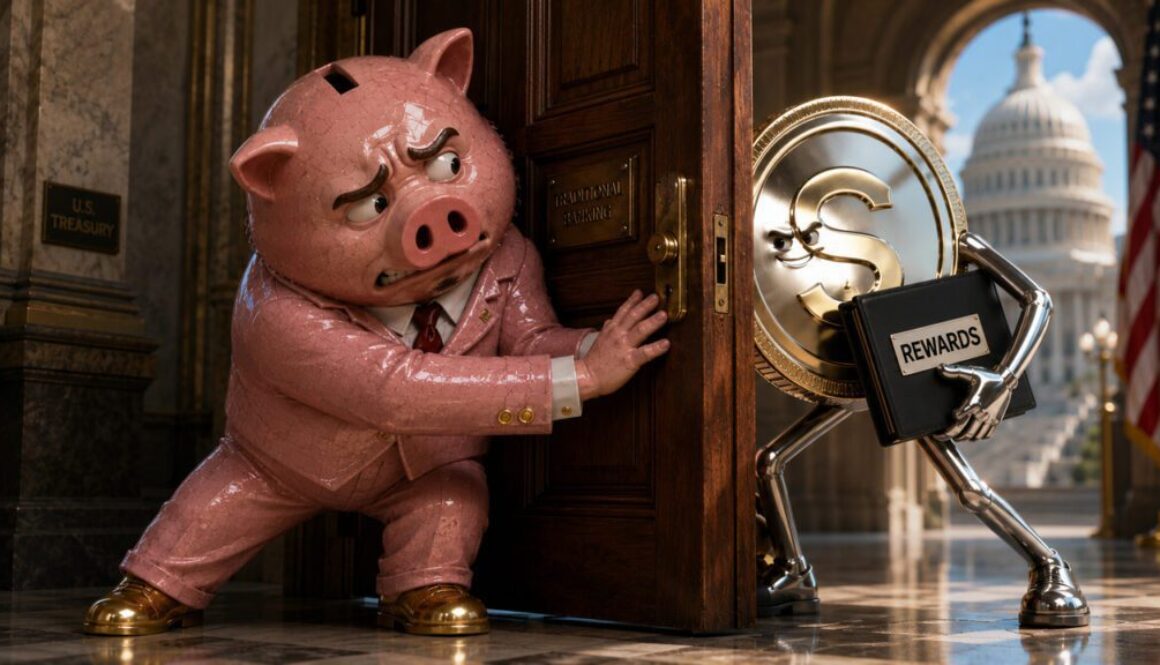
The stablecoin debate has become one of the most contentious parts of the CLARITY Act negotiations, with banking groups, including members of the American Bankers Association, spending weeks lobbying senators to tighten language restricting yield-bearing stablecoins.
As CryptoPotato reported earlier this week, banking groups sent Senate offices more than 8,000 letters ahead of the markup vote, while the crypto advocacy group Stand With Crypto said its supporters had contacted lawmakers nearly 1.5 million times in support of the bill.
But despite more than 40 amendments proposed by Senator Elizabeth Warren and procedural disputes during the hearing, the legislation advanced with support from Democratic senators Ruben Gallego and Angela Alsobrooks.
The Counter-Argument
While the BPI is demanding stricter anti-money laundering laws and sanctions regulations to be applied to crypto the same way it has been done to the traditional banking sector, data shared by Binance Research on May 14, offered some pushback to its claims.
According to Binance, trapped illicit funds on-chain have grown every year because less is being successfully laundered, not more.
Their report showed that more exit points are being blocked by KYC and more balances are being frozen by stablecoin issuers. Even the largest mixers have been processing at most $10 million per day.
Grove has launched a liquidity facility called Basin that offers up to $1 billion in daily stablecoin payouts for investors.
Basin’s big pitch is that investors can now redeem their tokenized real-world assets and receive coins immediately from Basin rather than wait the two to three business days it would take an off-chain platform to complete the transaction.
What is the ‘settlement gap’ in tokenized finance?
Tokenized real-world assets (RWAs) like treasury funds are supposed to run on modern technology. They trade on blockchains and promise speed, theoretically.
The issue was that when an institutional investor wanted to cash out of a tokenized fund like BlackRock’s BUIDL, the process still had to rely on traditional finance methods, which often takes two to three business days to be settled. In the crypto world, which operates 24/7, this delay creates inefficiency and risk.
The tokenized U.S. Treasury sector has grown over 130% in the past year, currently sitting at over $15.20 billion. Major players include Circle’s USYC ($2.91B), BlackRock’s BUIDL ($2.58B), and Franklin Templeton’s BENJI ($2.05B). But growth has been limited by the settlement gap between on-chain assets and off-chain cash-out times.
Grove Labs, a subsidiary of Steakhouse Financial, launched Basin, a programmable credit facility, as a solution to this issue. Now, when an eligible investor redeems shares, Basin gives them stablecoins immediately. Grove then waits for the traditional settlement to finish and gets repaid days later.
How does Basin affect BlackRock and Janus Henderson?
There has been an immediate impact of this new liquidity on BlackRock’s USD Institutional Digital Liquidity Fund (BUIDL, $2.58B) and Janus Henderson Anemoy Treasury Fund (JTRSY, $1.24B).
Previously, selling these tokens meant waiting for the fund administrator to process the request, but now, through partners like Securitize (for BlackRock) and Centrifuge (for Janus Henderson), investors hit “redeem” and receive stablecoins instantly.
Anchorage Digital, Galaxy Digital, and FalconX have signed on as institutional access partners to connect their clients directly to the Basin liquidity network.
BlackRock’s global head of digital assets, Robbie Mitchnick, stated that fixing this “settlement friction” is necessary to make funds usable for institutions. Nick Cherney of Janus Henderson called the move “an absolutely essential component” for realizing the full benefits of blockchain.
Cryptopolitan recently reported that BlackRock filed with the SEC to launch two new tokenized funds: a tokenized version of the existing BlackRock Select Treasury Based Liquidity Fund (BSTBL) and a new vehicle called the BlackRock Daily Reinvestment Stablecoin Reserve Vehicle (BRSRV).
A joint collaboration between Tether, TRON and blockchain analytics firm TRM Labs called the T3 Financial Crime Unit has announced on Wednesday that it has frozen more than $450 million in USDT suspected to be acquired through illicit, criminal means since the initiative launched in September 2024.
The frozen funds by the crime unit involve investigations into various illicit operations including money laundering, crypto exchange hacks, North Korea-linked cyber operations, terrorist cells financing, drug trafficking, and violent crimes including kidnappings and extortion, according to a statement published by Tether.
The T3 FCU has enlisted the help of multiple law enforcement agencies in its fight against illicit activity in the crypto community. These agencies span five different continents, with countries like the U.S., Spain, Germany, the Netherlands and Bulgaria having the highest volume of assets frozen.
Tether’s T3 puts in the work
The T3 FCU reported that it helped in the recovery of 43.9% more illicit proceeds in 2025 compared to the previous year. The unit claimed it can execute asset freezes within 24 hours of a request by law enforcement regarding an investigation, a pace that traditional banks and services find hard to match.
The group pointed to several high-profile cases where it helped with asset freezing and recovery. One involved the freezing of about $26.4 million allegedly connected to a European money-laundering ring that was dismantled alongside Spain’s Guardia Civil in early 2025.
Another case was “Operation Lusocoin”, a Brazilian Federal Police investigation that froze more than 3 billion Brazilian reais in crypto assets, of which 4.3 million USDT linked to a criminal network was a part, according to Tether’s statement. Additional freezes targeted wallets tied to North Korean cyber activity and funds traced to the Bybit hack, with nearly $9 million in crypto funds identified.
In addition, Tether confirmed a $344 million USDT freeze on TRON in April 2026 following intelligence-sharing with U.S. and international law enforcement.
T3 FCU breaks higher ground amid international recognition
The Financial Action Task Force cited T3 FCU earlier this year as an “invaluable resource for law enforcement agencies worldwide.” The FATF highlighted the unit alongside TRM Labs’ Beacon Network as leading examples of public-private partnerships for combating criminal activity in the crypto community.
The recognition comes amid a sharp rise in illicit cryptocurrency activity, with blockchain-related criminal activity reaching a record $158 billion in 2025, according to estimates from TRM Labs. The figures underscore the growing pressure on stablecoin issuers and blockchain platforms to strengthen compliance frameworks as regulators intensify the crypto sector’s scrutiny.
“Compliance is not an option; it is a part of our commitment to protect our users and stop any illicit behaviors,” said Paolo Ardoino in the announcement. “This $450 million milestone is just the beginning of what T3 is capable of,” he added.
Chris Janczewski, who previously served as a special agent with the IRS Criminal Investigation division, said the initiative combines “real-time intelligence and expertise with coordinated public-private action to disrupt illicit activity as it happens.”
The comments reflect an intensified industry effort to ensure stronger oversight and enforcement capabilities.
Is crypto decentralization a myth?
The scale of the recent asset freezes has reignited debate over the level of control centralized stablecoin issuers retain within blockchain ecosystems that are often said to be ‘decentralized’.
Tether includes issuer-level controls that allow Tether to blacklist specific wallet addresses and freeze associated funds, which goes against the intent behind cryptocurrencies like Bitcoin.
According to onchain data compiled by BlockSec, more than $500 million worth of USDT was frozen over a recent 30-day period. This amount extends beyond the activity linked to the T3 Financial Crime Unit in the statement and proves Tether is doing even more blacklisting on multiple blockchains.
The Senate Banking Committee’s CLARITY Act is heading into Thursday’s markup, buried under opposition.
According to reports, Senator Elizabeth Warren alone filed more than 40 amendments before Tuesday’s 5 p.m. ET deadline, and American Bankers Association members sent over 8,000 letters to Senate offices in less than a week demanding changes to the bill’s stablecoin yield rules.
Over 100 Amendments Filed
The total number of proposed amendments going into Thursday is still being confirmed, but according to a list obtained by Politico, there have been more than 100 proposed. To put things in perspective, a total of 137 revisions were proposed before the markup scheduled for January, which was canceled.
Warren’s batch alone covers a wide range of restrictions. One amendment that stood out would bar the Federal Reserve from issuing master accounts to crypto companies, which would effectively cut such firms off from the core infrastructure of the US banking system.
The lawmaker also attacked the updated bill on X, arguing that it lacked ethics provisions tied to President Donald Trump’s crypto businesses.
“No bill should move through the Banking Committee without real ethics guardrails,” she wrote.
That dispute has become harder for negotiators to avoid. Late last month, analyst Simon Dedic claimed that Trump’s meme coin and his crypto-related dinners were part of the reason the CLARITY Act was going nowhere, with Democrats demanding conflict-of-interest language before backing the legislation.
Another revision, filed by Senator Jack Reed of Rhode Island, would prohibit crypto from being used as legal tender, including for paying taxes. That proposal runs directly counter to a bill Representative Warren Davidson introduced last year that would have allowed Bitcoin to be used for precisely that purpose.
Senators Reed and Tina Smith of Minnesota also filed a joint amendment that would incorporate bank-requested changes to the stablecoin yield language.
According to journalist Brendan Pedersen, the proposal will force senators to choose between crypto and the banks on a single vote, making it an uncomfortable moment for Republicans who tend to side with both.
Bankers Blitz Senators With 8,000 Letters
Elsewhere, members of the American Bankers Association have reportedly sent more than 8,000 letters to Senate offices since last Friday, pushing lawmakers to change the bill’s stablecoin yield compromise.
However, Stand With Crypto, the crypto advocacy group, responded with its own numbers on Tuesday, saying its advocates had called Congress 8,000 times and sent 300,000 emails over recent months to protect stablecoin rewards, and have contacted lawmakers nearly 1.5 million times in support of the CLARITY Act overall.
Those on the side of digital assets are framing the banking industry’s lobbying campaign as an attempt to block competition from yield-bearing stablecoins.
Senator Bernie Moreno accused banks of trying to “kill stablecoins that would let everyday Americans earn real yields on their own money.” He also described the banking industry as a “cartel” protecting low-interest deposit models.
But not everyone inside Washington thinks this fight ends at Thursday’s committee vote. According to reporter Sander Lutz, banking policy leaders are already preparing for another push on the Senate floor if they lose the markup battle over yield restrictions.
Meanwhile, crypto journalist Eleanor Terrett reported that Senate Minority Leader Chuck Schumer privately encouraged Democrats to work toward supporting the bill.
As the Senate Banking Committee prepares to mark up the long-anticipated CLARITY Act on Thursday, Coinbase CEO Brian Armstrong has argued that the newest version of the bill represents a workable “compromise” and could meaningfully improve the US financial system.
Speaking to FOX Business, Armstrong said the updated draft reflects concessions on both sides—what he described as the crypto industry meeting requests from bank lobbyists and lawmakers, while the banking sector also gave ground during negotiations.
Coinbase CEO’s CLARITY Act Pitch
Armstrong also highlighted one specific element tied to stablecoin rewards. He said the approach in the latest bill would only apply when there is “some sort of material activity on the account,” adding that he believes the overall package would make the system “more efficient.”
The claim is that the legislation would help streamline financial services, reduce friction, and make access easier for consumers and businesses—while still keeping the framework aligned with banking-sector concerns that were raised during talks.
Still, critics point to the banking industry’s pushback as evidence that the dispute is far from settled. As reported throughout the week by Bitcoinist, banking trade groups have opposed the CLARITY Act’s stablecoin-rewards provision, arguing that it could give crypto firms too much flexibility.
Their position is that the policy might also encourage deposits to shift away from traditional, insured banking channels rather than strengthening them.
Beyond the details of stablecoin rules, Coinbase CEO argued that the broader direction of the CLARITY Act reflects growing institutional interest in digital assets.
In his view, banks are increasingly integrating stablecoins and crypto-related services because customer demand is rising—an angle that suggests the bill, if passed in its current form, could provide the clearer structure institutions want before expanding further.
Can The Latest Crypto Bill Draft Survive?
Supporters of the bill are not limited to Coinbase. Ripple CEO Brad Garlinghouse also backed the current push, commenting on social media site X (previously Twitter) that the Senate Banking Committee is “putting in the work” to move the CLARITY Act forward.
Garlinghouse’s message emphasized that Ripple supports the bill because crypto businesses and major participants should have the “same rules and protections as every other asset class,” and because—if the US is serious about leading in crypto—this is the moment to finalize legislation and get it done.
Even with that backing, the legislative road ahead is not smooth. Politico reported that Senator Elizabeth Warren, a well-known crypto skeptic, is vowing to pursue extensive changes to the bill through amendments.
The reporting says Warren and others are preparing more than 100 amendments ahead of the markup, following the release of an updated 309-page draft that expands on an earlier 278-page version introduced in January.
According to the same reporting, Warren submitted more than 40 amendments on her own, with much of the rest attributed to Democratic members of the Banking Committee.
This mirrors earlier moves around the bill: the January markup session drew 137 amendments, and it was eventually cancelled after a period of resistance that included Armstrong and Coinbase withdrawing support for the bill at the time.
For now, the core question going into Thursday’s markup is whether the latest CLARITY Act draft can hold together.
Featured image created with OpenArt, chart from TradingView.com
Circle’s $222 million ARC token presale has given Wall Street a new way to value the USDC issuer, while raising a harder question for one of crypto’s most profitable alliances.
On May 11, Circle said investors led by a16z Crypto backed the presale of ARC, the native token for Arc, its planned public blockchain for institutional finance.
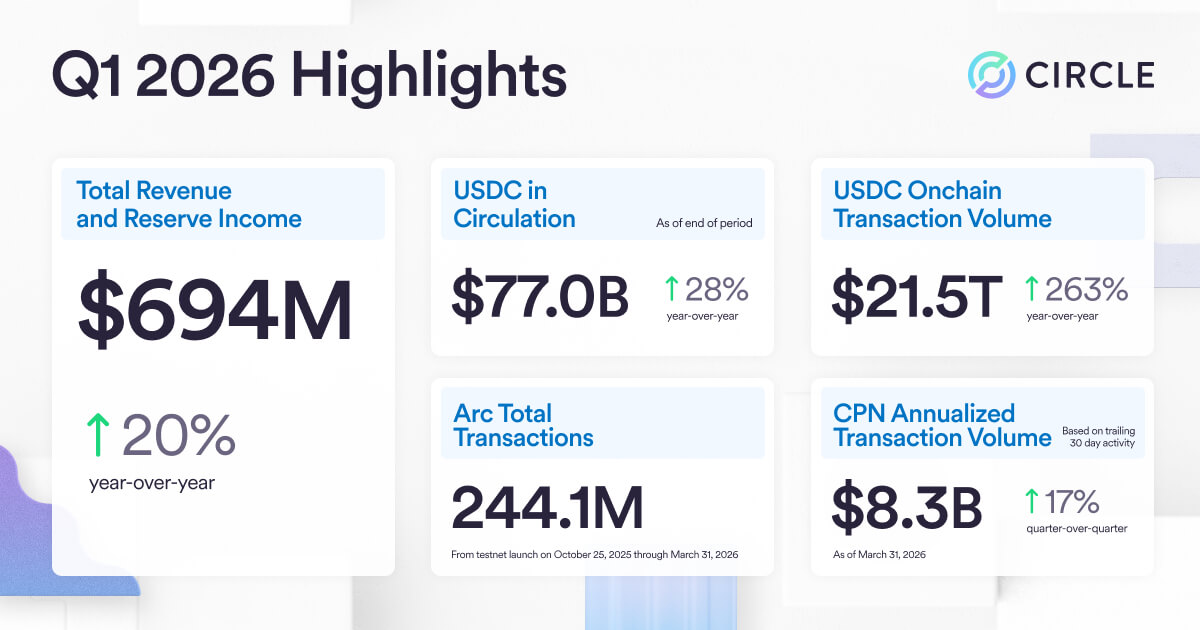
The sale valued the network at $3 billion on a fully diluted basis and came alongside first-quarter results that showed $694 million in total revenue and reserve income, up 20% from a year earlier.
At the same time, USDC in circulation rose 28% to $77 billion, while on-chain transaction volume reached $21.5 trillion, up 263% year over year.
Circle’s Q1 Earnings Report (Source: Circle)
Those figures reinforced Circle’s position as one of the main issuers in the global stablecoin market, where tokenized dollars have become core infrastructure for trading, payments, and settlement.
However, the more important development was Circle’s attempt to move beyond issuance through its new blockchain network, Arc.
Arc gives the company a network-level growth story built around payments, tokenized assets, foreign exchange, capital markets, and AI-driven commerce.
That push places Circle closer to the terrain already occupied by Coinbase, its longtime USDC partner and the operator of Base, the Layer 2 network that the US-based exchange has positioned as a settlement layer for stablecoins, consumer payments, and agentic transactions.
Considering this, Circle’s aggressive expansion could bring a new competition to the crypto landscape: a looming, head-to-head battle with Coinbase.
Circle gives investors a wider story
Circle’s business has long been tied to the economics of stablecoin reserves. The company issues USDC, holds safe assets backing the token, and earns income on those reserves.
That model can be powerful when rates are elevated, but it also raises questions about how durable its earnings will be as interest income declines.
The company is pitching the network as an “economic operating system” for the internet, a shared environment where stablecoins, tokenized assets, and financial applications can operate on common infrastructure.
The chain is expected to be EVM-compatible, with stablecoin-native fees, deterministic sub-second finality, and configurable privacy designed for institutions that need auditability without exposing every transaction detail to the public.
Circle Chief Executive Jeremy Allaire framed the quarter around the convergence of AI platforms and on-chain money, saying:
“Circle’s first quarter reflected strong execution against a much bigger opportunity: the rapid convergence of AI platforms and economic operating systems into a new internet stack. With the ARC token presale, momentum behind the Arc network, and the launch of our Agent Stack, we are building trusted infrastructure for AI-native economic activity and a more programmable internet financial system.”
The investor list shows how far that pitch now reaches. a16z Crypto led the presale with a $75 million investment.
Other participants included BlackRock, Apollo Funds, Intercontinental Exchange, SBI Group, Janus Henderson Investors, Standard Chartered Ventures, General Catalyst,a IDG Capital, Haun Ventures, and Bullish.
The message to investors is clear: Circle wants to be valued less as a stablecoin issuer exposed to rate cycles and more as a full-stack infrastructure company for on-chain finance.
In a note shared with CryptoSlate, Clear Street analysts echoed that view, writing that Circle is “no longer a pure crypto play” and has built the Layer 1 network, application layer, and partner ecosystem required to become a critical infrastructure provider.
The firm raised its price target on the stock from $152 to $157, citing Arc, Agent Stack, Circle Payments Network, and regulatory momentum as potential sources of upside.
USDC already moves across more than 30 blockchains and is integrated throughout exchanges, wallets, fintech platforms, and institutional systems.
That distribution has been one of the stablecoin’s main strengths. Circle could grow as USDC became more widely used, regardless of where the activity settled.
Arc gives Circle a reason to bring more of that activity onto the infrastructure it controls.
The network is designed to support payments, lending, foreign exchange, capital markets, and tokenized assets. Circle has also positioned ARC as a coordination token for validators, builders, liquidity providers, exchanges, institutions, and users.
In that structure, USDC remains the transactional asset, while ARC is intended to help govern economic rules and align network participants.
That creates a broader economic layer around Circle’s core product. If Arc gains traction, investors will not only measure Circle by USDC circulation and reserve income.
They will also track transaction volume, developer adoption, institutional participation, validator activity, and the degree to which Circle can capture revenue from the infrastructure surrounding USDC.
Circle Payments Network adds another part of that strategy. Clear Street said CPN reached $8.3 billion in annualized total payment volume and approached $10 billion by May 7, with 136 financial institutions enrolled.
Managed Payments is intended to reduce friction for banks and payment service providers by handling licensing, liquidity, custody, and compliance burdens.
Taken together, Arc, Agent Stack, CPN, and Managed Payments give Circle a more ambitious public-market story. The company is trying to become the platform where digital dollars move, settle, and interact with software.
That ambition makes the Coinbase relationship more complicated.
Coinbase already controls much of the flow
However, Coinbase has its own claim to the USDC infrastructure story.
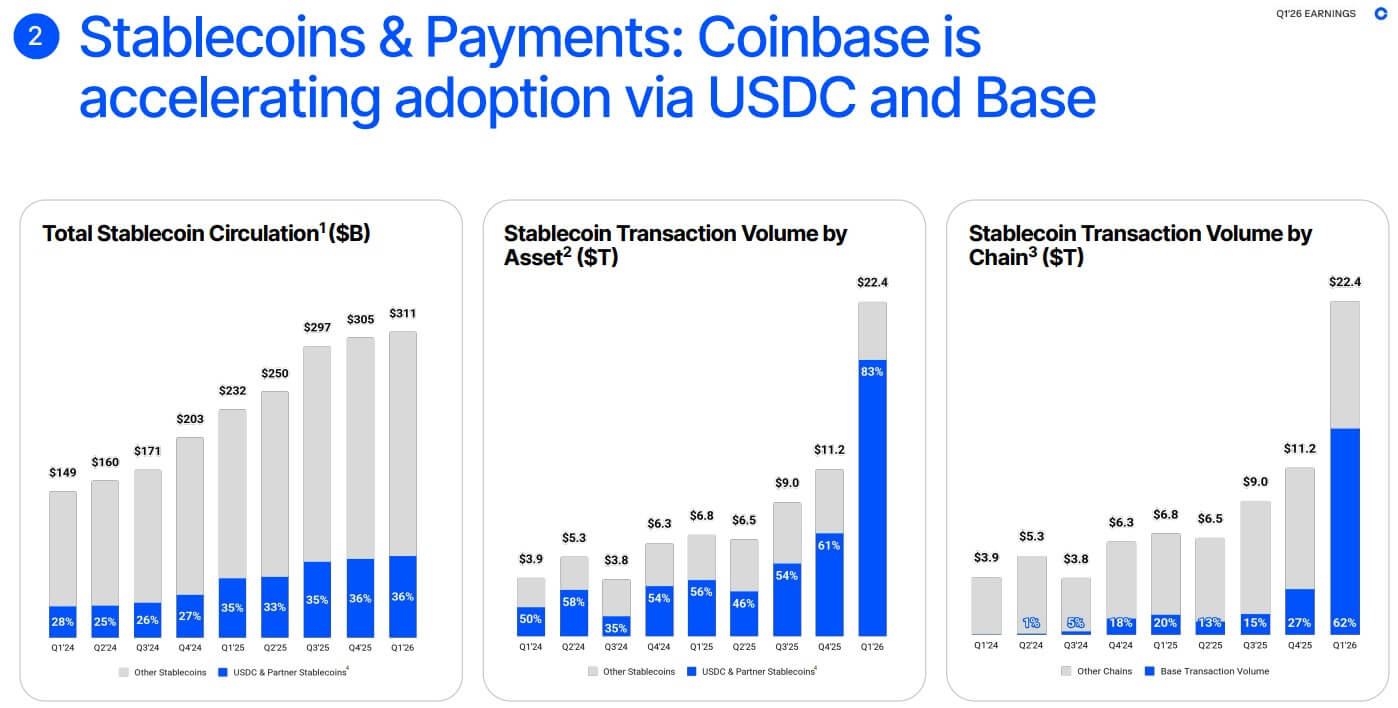
In its first-quarter report, the company described itself as the distribution engine for USDC, with more than 25% of total USDC in circulation, or about $19 billion on average, held across Coinbase products.
Coinbase said Base processed 62% of global on-chain stablecoin transaction volume during the quarter, more than all other chains combined.
At the same time, more than 100 million payments were processed through its x402 protocol, with more than 99% completed using USDC.
How Coinbase is Growing Stablecoin Adoption via USDC and Base (Source: Coinbase)
Those figures show why Arc is sensitive for Coinbase.
Coinbase is no longer merely a distribution channel for Circle’s stablecoin. It is building the rails around the asset.
Its stack includes USDC as the programmable dollar, Base as the low-cost settlement network, and Coinbase Developer Platform, AgentKit, and x402 as infrastructure for developers and AI-enabled payments.
Circle’s emerging stack points in the same direction. USDC provides the dollar asset, Arc provides the network, Agent Stack targets AI-native commerce, and CPN connects financial institutions and payment companies.
The companies remain commercially aligned around USDC growth. But their infrastructure strategies increasingly point toward the same flows.
The alliance gets a new scoreboard
For years, the Circle-Coinbase relationship was one of crypto’s cleanest partnerships. Circle issued USDC. Coinbase distributed it across its exchange, wallet, and institutional products. The stablecoin gained scale, and Coinbase shared in the economics.
That relationship helped make USDC one of the most important dollar assets in crypto. It also gave Coinbase a major stablecoin revenue line and helped turn USDC into a regulated alternative to Tether’s USDT for many US-based institutions.
However, Arc introduces a different incentive structure.
Omar Kanji, an investor at Dragonfly, captured the concern in a post asking how long the “marriage” between Circle and Coinbase can stay clean.
His argument was that the old model worked when Circle was the issuer, and Coinbase was the distributor. But Circle’s public-market demands and Arc’s token-backed network now require the company to show investors that it can own more customers, flows, and infrastructure directly.
That is where Arc overlaps with Base. Circle wants Arc to host USDC balances, tokenized assets, payments, settlement, and eventually foreign-exchange activity. Coinbase wants Base to serve as the main venue for stablecoin payments, on-chain consumer transactions, AI-agent activity, and institutional settlement.
The tension is already visible in adjacent products. Coinbase has cbBTC, a wrapped BTC product used across DeFi. Circle is preparing cirBTC, which is designed to integrate with Arc and Circle Mint.
While this overlap does not signal an immediate rupture, it shows that the companies are no longer staying in separate lanes and are beginning to compete on similar products.
AI payments raise the stakes
The competition becomes more significant when viewed through the lens of agentic commerce.
AI agents are expected to become a larger share of internet activity, handling tasks such as purchasing data, paying for software, settling invoices, managing subscriptions, and executing business processes.
Those transactions require programmable money, low-cost settlement, and infrastructure that can authorize spending without constant human intervention.
Stablecoins are well-suited to that environment because they operate continuously, settle quickly, and can be embedded directly into software. That has made agentic commerce one of the most attractive long-term narratives for stablecoin infrastructure providers.
Coinbase is already claiming early leadership. Its first-quarter materials pointed to Base’s share of on-chain agentic stablecoin transaction volume and the rapid growth of x402 payments. The company is presenting Base, USDC, AgentKit, and x402 as a ready-made stack for machine-driven economic activity.
Circle is moving to meet that opportunity with Agent Stack and Arc. Allaire has framed AI platforms and on-chain money as part of a new internet stack, and Circle’s product roadmap suggests the company wants USDC to become a settlement layer not only for humans and institutions, but also for software agents.
Considering this, Tom Wan, the head of data at Entropy Research, concluded:
“[Circle and Coinbase] business lines are converging across blockchain, tokenization, payments and stablecoins. A formal split is unlikely given the mutual benefits still on the table, but the trajectory is clear. Both sides are building toward a less dependent relationship, and the overlap will only create more friction over time.”
Bermuda’s government is sticking to their plan of migrating their national economy onchain and is now partnering with the Stellar Development Foundation to move payments and other financial services onto its network, XLM.
The island mentioned that its residents were facing processing costs of up to 10%, making the move onchain not just an attempt at modernizing the system, but a necessary step for retaining economic value.
Bermuda moves onchain
The Stellar Development Foundation and the Government of Bermuda announced today that Bermuda will begin moving its payment and financial activities onto the Stellar network (XLM). Bermuda revealed its plans to become the world’s first fully onchain national economy at the World Economic Forum in January this year.
The announcement explains that local merchants currently pay 3% to 5% per transaction in card fees, and effective payment processing costs can reach as high as 10% in some categories. Introducing the use of digital assets and infrastructure will keep more of that value on the island.
Under the plan, Bermudian residents will be able to receive wages, pay local merchants, settle government fees, and hold, send, and receive digital assets through digital wallets on the Stellar network.
Government agencies expect to pilot stablecoin-based payments, financial institutions will be able to integrate tokenization tools, and residents can participate in nationwide digital literacy programs. Digital assets may also be used for government payment systems related to social service disbursements.
“The lack of mobile money applications and reliance on legacy payments infrastructure has left Bermudians paying high payment processing fees and hindered additional economic growth opportunities,” The Hon. E. David Burt, JP, MP, Premier of Bermuda said.
Denelle Dixon, the CEO and Executive Director of the Stellar Development Foundation, added that Stellar was built for the purpose of seamlessly connecting the global financial system.
Before Bermuda, the Philippines had also launched a blockchain transparency system called Integrity Chain for its Department of Public Works and Highways (DPWH) after citizens held mass protests over corruption in flood-control projects.
An estimated 130,000 people protested on September 21, 2025, demanding accountability after reports of overpriced contracts, substandard construction, and ghost projects. The Australian Institute of International Affairs shared that the Philippines allocated over $33 billion to flood-control projects across 15 years.
What other blockchain initiatives is Bermuda working on?
Cryptopolitan recently reported that the Bermuda Monetary Authority (BMA), the island’s central bank and financial regulator, recently completed an “Embedded Supervision Solution” with Chainlink (LINK), Apex Group, Bluprynt, and Hacken.
The solution, announced earlier this month, demonstrates how rules can be built directly into digital asset infrastructure and enforced in real time. The system uses Chainlink’s Automated Compliance Engine (ACE) to check every transaction against Bermuda’s policies.
With Proof of Reserve, it verifies that digital dollars are backed by real money in a bank account. It also uses Secure Mint to stop new coins from being issued when reserve limits have been reached.
Apex Group, acting as an independent fund administrator with $3.5 trillion in assets serviced across 52 countries, supplies authenticated reserve data from third-party custodians. Hacken’s Extractor platform provides real-time onchain monitoring with a detection speed of 250 to 500 milliseconds.
The market has not shown significant price action following today’s announcement. XLM is trading around $0.1622, down approximately 4.82% over 24 hours, according to CoinMarketCap data.
XLM has spent most of 2026 trading below $0.20, fluctuating primarily within the $0.15 to $0.18. The 0.20 level now serves as both technical resistance and a major psychological barrier. Above this level, the next resistance zone sits around $0.22 to $0.25. On the downside, support clusters around the $0.15 to $0.16 range.
Notably, the CME Group began rolling out futures for XLM in February 2026, but the impact on XLM’s price has remained limited, and the futures listing has not yet generated enough buying momentum to push the token out of its sideways range.
According to the Stellar Foundation, the network surpassed $2 billion in onchain real-world asset (RWA) value in the first quarter of 2026. Data from DeFiLlama shows that the network currently has a stablecoin market capitalization of approximately $ 415 million, with its daily decentralized exchange (DEX) volume around $1.83 million.
S&P 500 payments business Corpay has today announced it is integrating stablecoin wallets and settlement into its global platform. This will give its +800,000 business clients payment rails that are open 24 hours a day, seven days a week, excluding bank holidays and weekend cutoffs.
The integration comes via a partnership with BVNK, a stablecoin infrastructure provider. Corpay customers will be able to keep stablecoin balances alongside their fiat currencies. They’ll be able to send, receive, store and convert stablecoins, all without ever leaving the Corpay interface, according to the release.
Corpay (NYSE: CPAY) processes +$12 billion in corporate payments each month. It also handles ~$26 billion in foreign exchange volume across over 145 currencies. The Canadian company plans to wire stablecoin rails into its own treasury operations too. This will cut its dependence on pre-funded accounts and speed up fund movement across its global network.
“At our scale, the ability to move liquidity quickly and reliably is critical,” said Mark Frey, Group President of Corpay Cross-Border Solutions. “Stablecoins introduce a 24/7 settlement capability that strengthens our existing infrastructure. BVNK provides the technology and compliance framework we need to deliver this securely and at scale.”
Jesse Hemson-Struthers, BVNK’s CEO, said Corpay’s reach makes the company a strong partner for pushing stablecoin payments into broader corporate adoption. He added, “Together, we’re enabling faster, more efficient ways for businesses to move and manage money across borders.”
BVNK attracts Mastercard, Visa, and Citi
Mastercard announced plans to acquire the company in a deal that could reach $1.8 billion by the time it closes at the end of 2026. Mastercard CEO Michael Miebach cited BVNK’s network of stablecoin stakeholders, liquidity providers, and hard-to-get licenses as the primary reasons for the purchase. He discussed the acquisition during the company’s Q1 2026 earnings call.
Visa Ventures, the investment arm of Visa, has invested in BVNK. Citigroup started backing BVNK in October 2025, according to Cryptopolitan. Arvind Purushotham, head of Citi Ventures, said that stablecoins are becoming more popular as a way to settle on-chain and crypto deals. He called out BVNK’s enterprise-grade infrastructure as a draw.
BVNK co-founder Chris Harmse said that the demand for stablecoin infrastructure has surged. The U.S. represents the company’s fastest-growing market. He pointed to the passage of the GENIUS Act as a catalyst for institutional confidence.
Stablecoins expand corporate payments integration
The Corpay deal lands as stablecoins continue to expand beyond crypto native use cases.
Dollar pegged stablecoin supply has reached $301 billion, according to data from CoinGecko. Tether’s USDT accounts for $189.6 billion of that total. Circle’s USDC sits at ~$77 billion.
Visa recorded a $7 billion annual run rate in stablecoin settlement volume during its most recent earnings call. That figure jumped +50% quarter over quarter. The card network now has +160 stablecoin card programs running globally with partners including Rain, Reap, and Bridge.
Citi raised its stablecoin market forecast in September. The bank projected the sector could hit $4 trillion by 2030 under a bullish scenario, up from earlier estimates of $1.6 trillion and $3.7 trillion, per Cryptopolitan.
A senior White House official has accused major banking trade leaders of refusing to join earlier talks on stablecoin rewards, escalating a dispute that has become one of the final pressure points ahead of the Senate Banking Committee taking up the CLARITY Act this week.
In a May 11 post on the social media platform X, Patrick Witt, executive director of the White House Presidential Advisory Committee on Digital Assets, said he had asked American Bankers Association President Rob Nichols and other bank trade CEOs to attend the February meetings aimed at resolving the question of stablecoin rewards and yield.
“I specifically requested the attendance of Mr. Nichols and other bank trade CEOs at the meetings we hosted back in February to resolve the stablecoin rewards/yield issue. They refused. I guess the White House was beneath them?”
The criticism injected the White House more directly into a fight that has divided banks, crypto companies, and lawmakers ahead of a scheduled May 14 markup of the CLARITY Act.
The bill is designed to create a broader market structure framework for digital assets, but the treatment of stablecoin rewards has become a flashpoint over competition for deposits, consumer yield, and the future shape of dollar-based payments.
Witt’s comments also reframed the timing of the banking industry’s objections. Rather than a new technical concern emerging before a committee vote, the White House official cast the dispute as an unresolved issue that banking leaders had an opportunity to address months earlier.
Banks reopen stablecoin rewards fight before markup
Over the weekend, the American Bankers Association (ABA) urged bank executives and employees to press senators for tighter restrictions in the CLARITY Act before the committee vote, warning that the current bill could still allow crypto firms to offer reward structures that resemble interest on deposit-like products.
Nichols told bankers that lawmakers needed to hear from the industry before the legislation advanced.
The ABA’s concern is that stablecoin issuers, exchanges, or related companies could attract customer funds by offering returns on assets that compete directly with traditional bank deposits.
Banks rely on deposits as a funding base for loans to households, small businesses, farms, and corporations. If customers move cash into stablecoins that offer rewards, banks argue that lenders could face higher funding costs, tighter margins, and less capacity to extend credit.
The banking industry has described the current compromise language as leaving a loophole.
In its view, a ban on stablecoin issuers paying yield would be insufficient if affiliated exchanges, brokers, or other crypto platforms could deliver similar economic benefits through rewards, rebates, or incentive programs.
That position has put banks at odds with crypto companies that see the rewards language as a basic competition issue.
Stablecoin reserves are typically held in cash, short-term Treasuries, or other liquid instruments that generate income. The policy fight centers on whether consumers should be able to receive part of that return, and which type of institution should be allowed to offer it.
The recent Senate compromise has attempted to separate passive yield from activity-based rewards.
That distinction was meant to prevent stablecoins from becoming direct substitutes for interest-bearing deposits while preserving room for crypto platforms to reward users for participation, payments, or other services.
White House analysis undercuts the lending warning
The Council of Economic Advisers said in an April report that banning stablecoin yield would provide only a marginal lift to bank lending under its baseline assumptions. The CEA estimated that such a ban would increase bank lending by about $2.1 billion, equal to roughly 0.02% of total lending in the base case.
That finding gives the administration a counterweight to the banking sector’s claim that stablecoin rewards could meaningfully damage credit creation.
The report argued that most stablecoin reserves would not be permanently removed from the banking system. Instead, reserves held in cash, bank deposits, or Treasury instruments would continue to circulate through financial markets in different forms.
The CEA also said a more severe impact would require a much larger stablecoin market and more restrictive assumptions about how reserves are held. In the administration’s framing, stablecoin rewards may affect bank margins, but the baseline effect on lending capacity appears limited.
Moreover, a separate analysis by Galaxy Research furthered the argument by focusing on the international flow of dollars.
Galaxy said banks were overstating the risk that stablecoin growth would simply drain domestic deposits. Its model projected that much of the growth under a regulated stablecoin framework would come from offshore users seeking easier access to dollar-denominated assets.
That finding changes the economic lens. If stablecoins mostly draw funds from US bank accounts, banks face a direct deposit migration problem.
However, if much of the growth comes from foreign users moving into dollar stablecoins, the effect could be an inflow into US financial infrastructure rather than a one-way drain from domestic lenders.
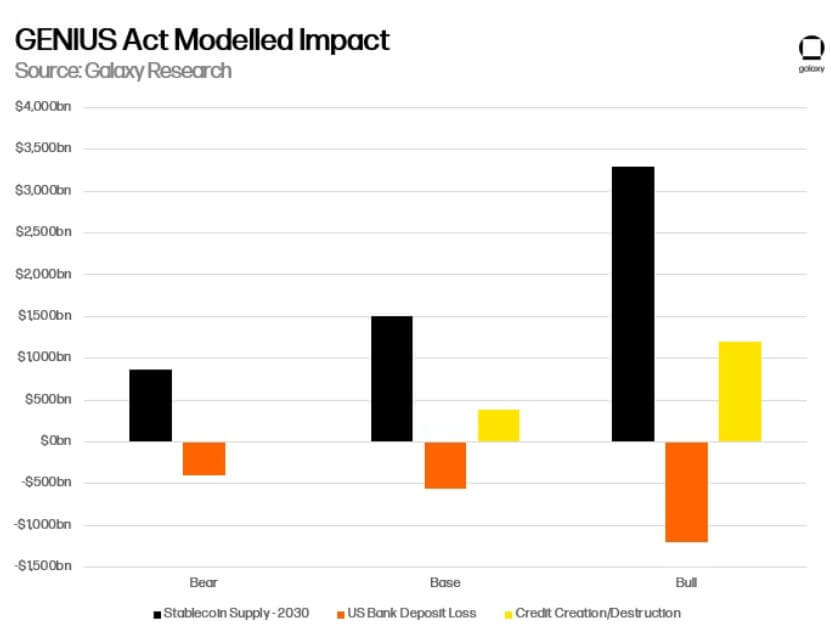
Galaxy estimated that 60% to 70% of stablecoin growth under the GENIUS Act framework could originate offshore. It also projected that imported deposits from foreign demand could exceed domestic deposit migration by roughly 2:1.
The firm said each newly minted stablecoin dollar could generate about 32 cents of net US credit, with total credit expansion reaching about $400 billion through 2030 in its base case and as much as $1.2 trillion in a stronger growth scenario.
GENIUS Act Impact on Stablecoin (Source: Galaxy Digital)
It also projected that stablecoin reserve demand could compress Treasury bill yields by 3 to 5 basis points, potentially lowering federal borrowing costs.
Meanwhile, Galaxy did not dismiss the pressure on banks. The report said some low-cost deposits would likely migrate, funding costs could rise at the margin, and net interest margins could compress in business lines sensitive to rate competition.
Still, the firm concluded that stablecoins could pressure banks that rely on cheap deposits, increase demand for US Treasury bills, import offshore dollar capital, and expand the reach of the US financial system.
Crypto allies accuse banks of protecting margins
Crypto advocacy groups have seized on the ABA’s push as evidence that banks are trying to block competition days before the committee vote on the CLARITY Act.
Coinbase-backed Stand With Crypto urged supporters to contact senators, saying banking lobbyists were trying to weaken stablecoin rewards language before the markup.
The group framed the dispute as a consumer-rights issue, arguing that users should be able to earn returns on their own digital assets rather than have that value captured by intermediaries.
Cody Carbone, CEO of The Digital Chamber, said banks had months to negotiate over the issue and were now trying to force changes late in the process. He described the ABA campaign as an attempt to shield incumbents from competition after earlier opportunities to engage had passed.
Sen. Bernie Moreno, an Ohio Republican on the Banking Committee and a supporter of crypto legislation, used sharper language about the bank’s opposition to CLARITY Act.
He accused the “banking cartel” of trying to preserve a system in which banks pay depositors little while earning profits from lending and securities portfolios.
Moreno wrote on X:
“During the Biden era, these same banks worked hand-in-glove with Sen. Warren and her allies to debank Americans, including President Trump’s own family. They shut down accounts of conservatives, patriots, and anyone who dared challenge the regime, all while regulators applied pressure under schemes like Operation Choke Point 2.0. It wasn’t about risk. It was about political control. Now that innovative stablecoins threaten to break their monopoly and give you actual financial freedom? They’re running to Congress again, screaming about ‘threats to economic growth and financial stability.’”
Moreno’s statement showed how the stablecoin rewards dispute has moved beyond technical drafting.
The fight now carries a broader political message about financial competition, consumer returns, and resentment toward large banking institutions.
That rhetoric could help crypto advocates rally support, especially among Republicans who view stablecoins as part of a broader agenda around financial innovation and dollar competitiveness.
However, it also risks hardening opposition from lawmakers who are already concerned that crypto firms are seeking bank-like privileges without equivalent oversight.
Markup will test whether the stablecoin compromise can hold
If the committee advances the CLARITY Act with the current language largely intact, crypto firms will claim momentum, and banks will likely shift their campaign to the full Senate.
If lawmakers tighten the rewards provisions, the banking industry will have succeeded in reopening one of the most contested parts of the bill at the final stage before markup.
Meanwhile, the vote will also test the broader coalition behind the CLARITY Act. Republicans have pushed digital-asset legislation as a priority, while some Democrats have remained open to a market-structure bill if it includes stronger consumer protections, ethics, and anti-money-laundering provisions.
The stablecoin fight complicates that effort because it cuts across several policy lines at once. It raises questions about bank funding, consumer yield, Treasury demand, offshore dollar usage, and the role of crypto firms in payments.
That gives senators several reasons to demand changes, but also makes the issue difficult to settle cleanly.
Senator Bernie Moreno on Monday accused the U.S. banking lobby of full panic mode over CLARITY Act stablecoin yields. The American Bankers Association is urging bank CEOs to pressure senators against the provisions.
The Ohio Republican sits on the Senate Banking Committee. He published the criticism on X ahead of Thursday’s CLARITY Act markup.
ABA Letter Targets CLARITY Act Stablecoin Yield Language
ABA CEO Rob Nichols sent a Sunday letter to every bank CEO in the country. He called for “immediate engagement” on stablecoin yield policy.
Nichols warned that the current proposal would prompt deposit flight into payment stablecoins, citing risks to growth and stability. His note described what banks call a stablecoin loophole in the committee’s draft.
“we believe committee members may not be fully aware of the risks to the economy by the stablecoin loophole,” read an excerpt in the letter, citing Nicholas.
Moreno rejected that framing, saying the question was already litigated during the GENIUS Act debate led by Senator Bill Hagerty.
🚨 The banking cartel is in full panic mode. 🚨
While Americans were celebrating Mother’s Day with their families, the CEO of the American Bankers Association sent a frantic alert to every bank CEO in the country, demanding “immediate engagement” to lobby Senators and kill… pic.twitter.com/Phd6HsdBXR
The Senate Banking Committee marks up the CLARITY Act on Thursday, May 14, at 10:30 a.m. ET. Polymarket bettors now give the bill a 73% chance of becoming law this year.
Senators Thom Tillis and Angela Alsobrooks brokered the disputed compromise text. It bars yield “economically or functionally equivalent” to deposit interest. The provision still permits rewards from bona fide platform activity.
“I specifically requested the attendance of Mr. Nichols and other bank trade CEOs at the meetings we hosted back in February to resolve the stablecoin rewards/yield issue. They refused. I guess the White House was beneath them? In their defense, I wouldn’t want to have to defend their position in public either,” he said.
A successful markup would advance the bill toward a full Senate floor vote. A stall could sideline U.S. crypto legislation for the rest of the session.