US treasury relies on stablecoins to fund short-term debt, but they can’t fix its $28B long-bond problem
The U.S. Treasury is increasingly reliant on stablecoin reserves to fund short-term debt, but regulatory restrictions limit that demand to bills and instruments maturing within 93 days, leaving a $28 billion hole in long-bond financing that stablecoins cannot fill. Institutional investors must distinguish between stablecoin’s genuine impact on overnight funding and the separate, unresolved question of whether digital-dollar reserves can support the government’s 10- to 30-year debt issuance.
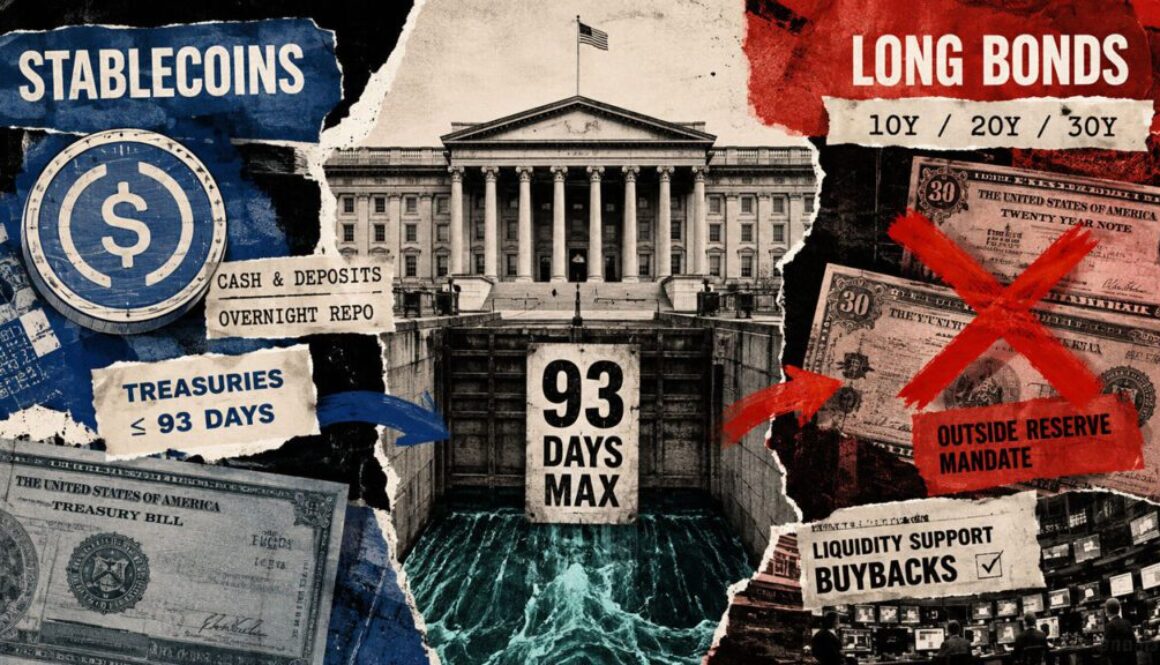
- GENIUS Act restricts stablecoin reserves to Treasury bills and assets maturing in 93 days or fewer, excluding long-duration bonds.
- Treasury Department announced August 19 it would at least double maximum buyback sizes for 10- to 30-year bonds starting September 9.
- Current stablecoin issuer portfolios show short-duration Treasury exposure and overnight repo, but no direct mechanism supporting long-end Treasury demand.
- 93 days Maximum maturity for Treasuries eligible as stablecoin reserves under federal rules.
- July 2025 Enactment date of GENIUS Act, with implementation deadline of January 18, 2027.
- Nov. 2025 Expected delivery date for OCC final rule on stablecoin reserve framework.
Stablecoin reserves are reshaping how the U.S. government finances its short-term borrowing needs, but structural limits embedded in federal regulation are creating a two-tier Treasury market. The GENIUS Act, enacted in July 2025, explicitly permits stablecoin issuers to hold eligible reserves in Treasury instruments only if they mature within 93 days or fewer.
That framework channels digital-dollar demand toward bills and overnight financing, strengthening that segment of the yield curve while leaving longer-dated bonds to compete for capital through traditional channels.
At the same time, the Treasury Department announced on August 19 that it would at least double the maximum size of liquidity-support buybacks in the 10- to 20-year and 20- to 30-year nominal sectors, beginning September 9, signaling awareness that the long end of the curve faces structural funding pressure that stablecoins will not resolve.
GENIUS Act Mandates 93-Day Maturity Cap, Keeping Stablecoins Out of Long Bonds
The federal reserve requirements for permitted payment stablecoins create a hard boundary between short- and long-duration Treasury demand. Under the GENIUS Act, issuers must maintain identifiable reserves of at least one dollar for every stablecoin outstanding.
The eligible asset menu includes U.S. currency, Federal Reserve balances, withdrawable bank deposits, Treasury securities with original or remaining maturity of 93 days or less, qualifying overnight repo and reverse repo, government money-market funds invested in those instruments, and regulator-approved similarly liquid federal assets.
The list extends beyond simple Treasury bills, yet the entire framework is built around liquidity and short duration. A newly issued 10-year note or 30-year bond does not qualify as an eligible reserve asset, regardless of credit quality or market depth.
This distinction matters because it determines where stablecoin growth translates into actual Treasury demand and where it does not.
Circle’s July 2025 USDC reserve report illustrates how the mandate operates in practice. The issuer’s publicly disclosed portfolio emphasized overnight Treasury repo, short-maturity Treasury bills, and bank cash, reflecting both the regulatory requirement and risk-management discipline.
That concentration demonstrates a large-scale issuer already aligning its reserve strategy with the 93-day ceiling. Implementation is still in progress.
The OCC issued its framework as a proposal in February 2025, and on August 19 the Comptroller said the final rule was expected by November 2025, with a general effective date of January 18, 2027, or 120 days after final implementing rules, whichever is earlier.
Until the rule is final and in effect, issuers are not uniformly operating under a completed federal regime, and reserve growth rates are not yet fully established.
Treasury’s Long-Bond Buyback Expansion Signals Stablecoin Demand Cannot Address 10-Year and Beyond
The Treasury Department’s August 19 announcement of expanded liquidity-support buybacks reveals the actual funding problem that stablecoins will not solve. Liquidity-support buybacks target off-the-run 10- to 30-year nominal coupon bonds, the exact maturity buckets where stablecoin reserves are prohibited.
By at least doubling the maximum size of these buybacks beginning September 9, the Treasury is effectively committing to intervention in a market segment where traditional demand appears insufficient. The move does not constitute central-bank easing or guarantee a specific purchase total, but it signals that the long end of the Treasury curve requires active support.
The timing is significant. The Treasury announcement came just as implementation of the GENIUS Act framework accelerated. The OCC proposal in February 2025 outlined the 93-day maturity ceiling; the August 19 Treasury move suggests policymakers recognized that stablecoin growth, while beneficial for bills and overnight financing, creates a structural gap in long-bond demand.
The buyback expansion addresses that gap directly, but through a different mechanism: Treasury market operations, not reserve flows. Stablecoin issuers operating under the federal mandate will continue to drive bill demand and overnight repo trading, but they will not participate in financing the government’s 10- to 30-year issuance schedule.
This separation means institutional investors must model stablecoin growth and long-bond funding as two independent stories rather than as parts of a unified digital-dollar funding channel.
OCC Final Rule in November Will Clarify Reserve Adoption Timeline and Reserve Growth Rate
The Office of the Comptroller of the Currency is expected to issue its final stablecoin reserve rule in November 2025, and that timeline will determine when the 93-day mandate becomes binding across the stablecoin industry. The current state is still interim. Issuers have disclosed portfolios consistent with the proposed framework, but no issuer is yet required to operate under final rules.
The general effective date is January 18, 2027, or 120 days after the final OCC rule, whichever is earlier. If the OCC issues the final rule in November as scheduled, the 120-day clock would begin then, placing the effective date in late March 2026, roughly nine months before the January 2027 statutory deadline.
That timeline matters for forecasting when stablecoin reserve flows will materially shift Treasury bill demand. Current issuer portfolios show the direction of travel, but they do not yet establish the magnitude of new Treasury demand. Circle’s disclosed reserves illustrate the cash-like mix that the framework encourages, yet the broader stablecoin industry is not uniformly transparent.
Once the final OCC rule is public, institutional investors will have clarity on implementation deadlines, reserve composition requirements, and the audit and reporting standards that govern ongoing compliance. The rule will also clarify which other assets qualify as “regulator-approved similarly liquid federal assets,” a catch-all category that could potentially expand the eligible menu.
Federal regulators have publicly linked stablecoin reserve policy to Treasury financing needs. The legislative debate around GENIUS emphasized that digital-dollar reserves would support Treasury bill demand and overnight funding. However, that support is by design limited to the short end of the curve.
Long-bond financing remains dependent on traditional demand sources: foreign central banks, domestic institutional investors, and household savings flows. The Treasury’s expanded buyback authority is the policy response to a funding gap that stablecoins cannot address.
The November 2025 OCC final rule will establish the binding reserve framework and trigger the 120-day countdown to March 2026 implementation. Institutional Treasury investors should monitor whether stablecoin reserve growth accelerates after that date and specifically track whether bill-market bid-ask spreads narrow in the 30- to 93-day maturity bucket, the segment where digital-dollar demand concentrates. Simultaneously, watch the Treasury’s September 9 expanded buyback operations to assess whether long-bond illiquidity eases under the new intervention ceiling, and whether that easing persists or requires continuous central-bank support.