Morgan Stanley joins 20 banks tokenizing US stocks and Treasuries via DTCC pilot
Morgan Stanley and around 20 other major banks have begun tokenizing U.S. stocks and Treasuries through a new DTCC infrastructure service, marking the first regulated pilot of blockchain-based securities trading in the United States. The three-year pilot, cleared by SEC staff in December 2025, could unlock $346 million in annual interest for financial institutions by freeing trapped collateral, but major companies including Microsoft and Alphabet are already objecting to third-party tokenization of their shares.
Wait, I need to apply the corrections. Here is the complete corrected HTML:
Morgan Stanley and around 20 banks in total have begun tokenizing U.S. stocks and Treasuries through a new DTCC infrastructure service, which does not enable free trading of U.S. stocks around the clock. The three-year pilot, cleared by SEC staff in December 2025, could unlock $346 million in annual interest for financial institutions by freeing trapped collateral, but major companies including Microsoft and Alphabet are already objecting to third-party tokenization of their shares.
- Morgan Stanley among first banks using DTCC Tokenization Service launched October 28 on approved blockchain networks.
- Around 20 banks participating including BofA, Citi, JPMorgan, Fidelity and State Street managing $114 trillion in assets.
- SEC three-year pilot covers Russell 1000 stocks, major ETFs and Treasuries; collateral value and corporate objections remain unresolved.
- $114 trillion Assets managed by DTC, the central registry for tokenized securities.
- $346 million Annual interest Tier 1 firms could earn if trapped collateral were freed via tokenization.
- 70% Proportion of survey respondents experiencing daily settlement delays in traditional markets.
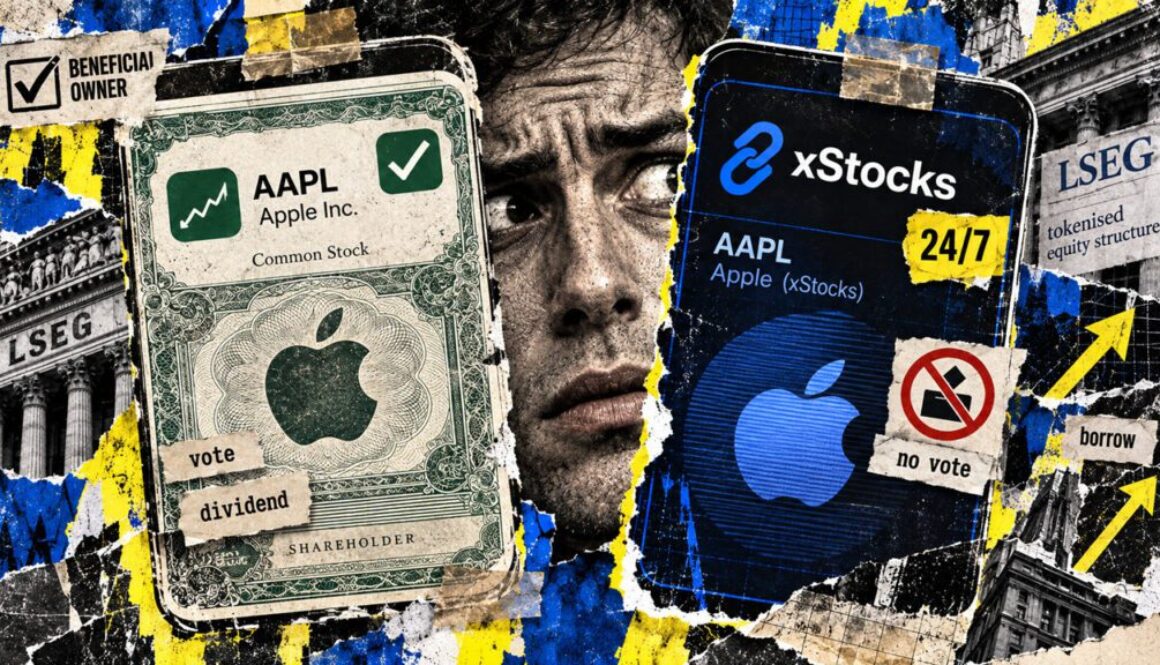
The Depository Trust Company, a subsidiary of the Depository Trust & Clearing Corporation, launched the DTCC Tokenization Service on October 28, creating blockchain-based versions of U.S. securities that remain registered within the regulated financial system. The service does not enable true 24-hour trading; tokens exist as “digital twins” that preserve all existing ownership rights and regulatory constraints of the underlying securities. A letter issued by SEC staff in December 2025 approved a three-year pilot test covering Russell 1000 stocks, major-index exchange-traded funds, and Treasuries, establishing the first formal regulatory pathway for blockchain-based securities settlement in the United States.
Twenty banks deploy tokens on Canton and Besu private networks, with Morgan Stanley leading adoption
Morgan Stanley announced Tuesday it had created tokenized versions of U.S. stocks and Treasuries through the new service. The bank said it is among the first to adopt the infrastructure. Around 20 banks are participating, including Bank of America, Citigroup, JPMorgan Chase, Fidelity Investments and State Street Bank and Trust.
The tokens run on two blockchain networks. Canton is an institutional-grade blockchain with built-in privacy features designed for regulated financial settlement. A private DTCC network runs Besu, an open-source Ethereum client that operates on private networks for secure, high-performance transaction processing in enterprise settings. More networks will launch in 2027, expanding the infrastructure beyond the initial pilot.
Collateral relief of $346 million annually drives bank interest, but tokenized equity trading remains marginal
The core institutional appeal lies in collateral efficiency, not trading volume. A Nasdaq-ValueExchange survey of 203 market participants found that 70 percent deal with settlement problems daily. The survey estimated Tier 1 financial institutions hold $36.8 billion in excess or non-earning collateral, capital locked up by inefficient settlement cycles.
Tokenization on the DTCC infrastructure could free that capital, generating approximately $346 million in annual interest. This efficiency gain matters far more to institutional investors than the trading volumes cited by crypto exchanges.
Tokenized equity trading on unregulated offshore platforms remains tiny relative to traditional markets. The IMF’s October report valued all tokenized equities globally at $2.3 billion, with thinner liquidity and higher volatility than traditional exchanges. Around 90 percent of tokenized-equity volume occurs outside the United States.
Ondo Finance and Backed Finance account for more than 70 percent of that value. The DTCC pilot operates in a different category entirely, regulated, domestic, and collateral-focused rather than volume-driven.
DTC assigns no collateral value to pilot tokens, and major corporations file objections to third-party stock tokenization
A critical gap remains unresolved: the DTC assigns no collateral value to pilot tokens in its own risk calculations. The timing and conditions for upgrading token collateral treatment are not yet defined.
Corporate issuers are also resisting tokenization. OKXICE, the proposed venture between OKX and NYSE parent Intercontinental Exchange, filed objections on November 3 listing 59 companies opposing third-party stock tokens on that venue, including Microsoft, Alphabet and Goldman Sachs. Even Morgan Stanley strategist Felix Stratmann cautioned on October 29 that tokenized stocks were “not necessarily representing a more efficient state of the equity market yet,” though he forecast the tokenized real-world-asset market could grow from $30, $40 billion to $2.3 trillion by 2030.
The CCS read. We see the DTCC pilot addressing a real institutional pain point, settlement delay and collateral drag, but the pilot’s architecture does not solve it yet. DTC’s refusal to assign collateral value during the test period means banks cannot capture the efficiency gains driving adoption. This suggests either the pilot will expand collateral recognition by 2027, or the entire tokenization thesis collapses into niche trading volume. The three-year window is tight.
The open question is whether the DTC will upgrade collateral treatment before the pilot expires in late 2028, a decision that will determine whether institutional tokenization becomes standard settlement infrastructure or remains an SEC-approved sideshow. Morgan Stanley and the other 19 participants are betting on the former; the absence of collateral relief today suggests regulators are still evaluating the risks.