Wall Street pushes Kevin Warsh to future-proof lighter Fed Rules
Wall Street is urging Federal Reserve leadership to embed lighter bank supervision into formal legal rules that would survive a future Democratic administration, signaling institutional concern that deregulatory gains under Trump could be reversed. The push reveals a structural tension: banks want permanent relief from examination intensity, but regulators need the flexibility to tighten oversight during crises.
- Four people familiar with private talks say lenders are pressing the Fed to give new supervisory processes firmer legal backing against future political reversal.
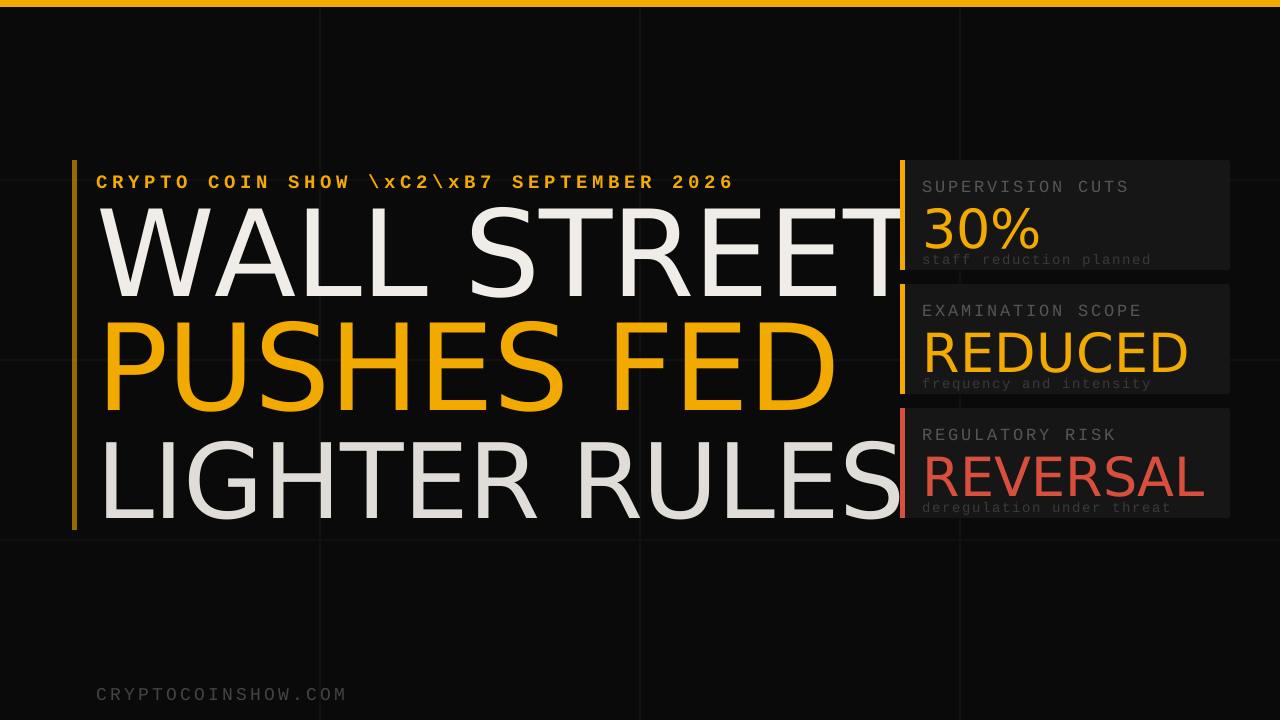
- Fed Vice Chair Michelle Bowman is leading an overhaul that includes cutting supervision staff by roughly 30% and reducing the frequency and scope of bank examinations.
- Institutional investors must assess whether lighter, legally codified rules improve bank lending and capital formation or create systemic vulnerabilities ahead of the next downturn.
- 30% Planned reduction in Federal Reserve regulation and supervision staff under current overhaul
- MRAs Private examination warnings system that Wall Street wants replaced with softer, legally codified supervisory framework
- 2008 Last financial crisis prompting current regulatory landscape that Trump administration is actively reshaping
Wall Street banks are making a direct institutional play to lock in lighter regulation by asking the Federal Reserve to anchor new supervisory processes in formal legal rules rather than informal guidance.
Four people familiar with confidential discussions told media outlets that lenders are pressing Fed officials to give the emerging supervisory system firmer statutory footing, making it legally harder for a future administration to dismantle.
The core concern is practical: absent legal codification, a Democratic Fed could revert to stricter examination regimes within months, erasing years of accumulated relief. This represents a shift in how Wall Street typically operates, rather than lobby for case-by-case flexibility, major banks now want durable, rule-bound deregulation that transcends political cycles.
Bowman’s 30% Staff Cut and Shift Away From MRA Warnings
Michelle Bowman, the Federal Reserve’s Vice Chair for Supervision, is orchestrating one of the most aggressive supervisory overhauls since the 2008 financial crisis.
Under her leadership, the Fed has proposed eliminating Matters Requiring Attention (MRAs), the private, confidential examination warnings that examiners have issued to banks for decades when they identify operational, compliance, or risk management problems. MRAs carry no public stigma; they are internal notices requiring banks to remediate issues or face potential enforcement action.
However, lenders have long viewed them as burdensome, arguing that the examination process prioritizes trivial compliance technicalities over substantive risk management.
To accelerate this shift, Bowman has announced plans to cut Federal Reserve supervision and regulation staff by approximately 30%, representing a substantial reduction in the agency’s capacity to conduct deep examinations and ongoing monitoring. The cuts have prompted departures among long-serving career examiners while creating space for new hires aligned with a lighter-touch philosophy.
The administration has justified this staffing reduction on efficiency grounds, contending that examiners spend excessive time on “foot faults” rather than concentrating on material risks to bank safety and soundness.
Todd Baker, senior fellow at Columbia University’s Richman Center for Business, Law and Public Policy, characterized the effort plainly: Bowman is “attempting to alter the supervisory culture of the Fed and to shift the power balance … in favor of bank management.” This candid assessment reflects the directional clarity of the overhaul, it is explicitly designed to reduce friction between regulators and banks, not merely to improve efficiency.
Wall Street’s Bid to Legally Enshrine Softer Rules Against Future Reversals
The conversation between Wall Street and Fed leadership has moved beyond requests for lighter day-to-day supervision. Banks now want the Fed to translate the emerging softer framework into formal legal rules, complete with statutory or regulatory backing that would make it difficult or impossible for a successor administration to reverse course.
This demand reflects institutional anxiety that political volatility in Washington could wipe out regulatory gains faster than they can be secured.
Banks argue that legal codification serves a practical purpose: it allows large financial institutions to plan capital allocation, hiring, technology investment, and business strategy over multiyear horizons without fear of sudden regulatory whipsaw.
A bank that reduces compliance staffing in response to softer MRA treatment today cannot easily rehire and retrain those teams if examination intensity spikes in 2029. From a banking perspective, durable rules provide the certainty required to deploy capital efficiently and extend credit to borrowers.
However, this request creates a regulatory paradox. Formal, legally binding rules sacrifice the very flexibility that regulators value during financial stress. The 2008 crisis illustrated why the Fed needs discretionary supervisory authority, examiners must tighten oversight rapidly when economic conditions deteriorate or new risks emerge.
If lighter supervision is locked into law, reversing it during a credit freeze or asset bubble becomes politically and procedurally difficult, potentially constraining regulators’ ability to act decisively.
Kevin Warsh’s Appointment and Accelerating Deregulatory Timeline
Kevin Warsh’s appointment as Federal Reserve Chair under the Trump administration has intensified expectations among bankers that the supervisory overhaul will accelerate. Warsh, a former Fed governor and longtime financial market participant, is known for favoring market-based solutions over prescriptive regulation.
Banking industry participants widely expect him to move faster and further than Bowman alone might achieve, particularly on items requiring Fed Board approval or interagency coordination.
The timing matters significantly for institutional investors assessing regulatory risk. The Fed’s Board will vote on major supervisory changes over the coming months, including potential revisions to the confidential rating system banks receive during examinations.
These rating downgrades can trigger enhanced capital requirements and examination frequency, so any formal loosening could materially improve bank profitability and capital flexibility.
Trump’s administration has publicly justified lighter supervision as a tool for expanding lending and supporting economic growth. A White House spokesperson framed the policy shift in terms of “objective and measurable risks” to financial markets, suggesting the government will maintain guardrails against tail risks while eliminating redundant or outdated rules.
This messaging may help secure political cover if a future crisis forces a rapid tightening, though it remains unclear whether courts would uphold emergency regulatory action that reverses formally codified lighter rules.
What Institutional Investors Should Monitor in Coming Months
The outcome of Wall Street’s push for legally durable lighter rules will determine the medium-term competitive landscape for banking.
If the Fed moves rules into formal regulatory text, banks can confidently reduce compliance costs and extend risky credit with fewer examination headaches, a scenario favorable to bank equity valuations but potentially concerning to fixed-income investors and prudential regulators.
If Bowman and Warsh instead proceed through informal guidance and internal policy shifts, the entire framework remains vulnerable to sudden reversal, leaving banks in regulatory limbo.
Institutional asset managers and fixed-income investors should closely monitor whether the Fed proposes formal amendments to its supervisory regulations versus simply changing internal examination procedures. Formal rule amendments trigger notice-and-comment rulemaking, creating a public record and Democratic opposition; informal guidance changes can proceed quickly but leave weaker legal footing.
The Fed’s choice of mechanism will signal whether it intends a permanent realignment or a temporary accommodation likely to reverse after 2028.
Watch for the Fed’s formal proposal on supervisory rating methodologies and MRA replacement procedures, expected over the coming quarters. Kevin Warsh’s stated priorities for his first ninety days as Chair will indicate how aggressively the Board intends to advance legally binding deregulation, and whether Democrats on the Board will force a compromise that preserves some examination authority during downturns.