Open Standard’s OUSD stablecoin hits $666 million with 74% held in ten wallets
Open Standard’s OUSD stablecoin has reached $666 million in circulation one week after launch, but 74% sits idle in ten wallets, signaling heavy institutional positioning ahead of real-world adoption tests. For institutional investors, the metric to watch is not headline supply but the pace at which staged inventory moves into actual payment settlement and DeFi activity.
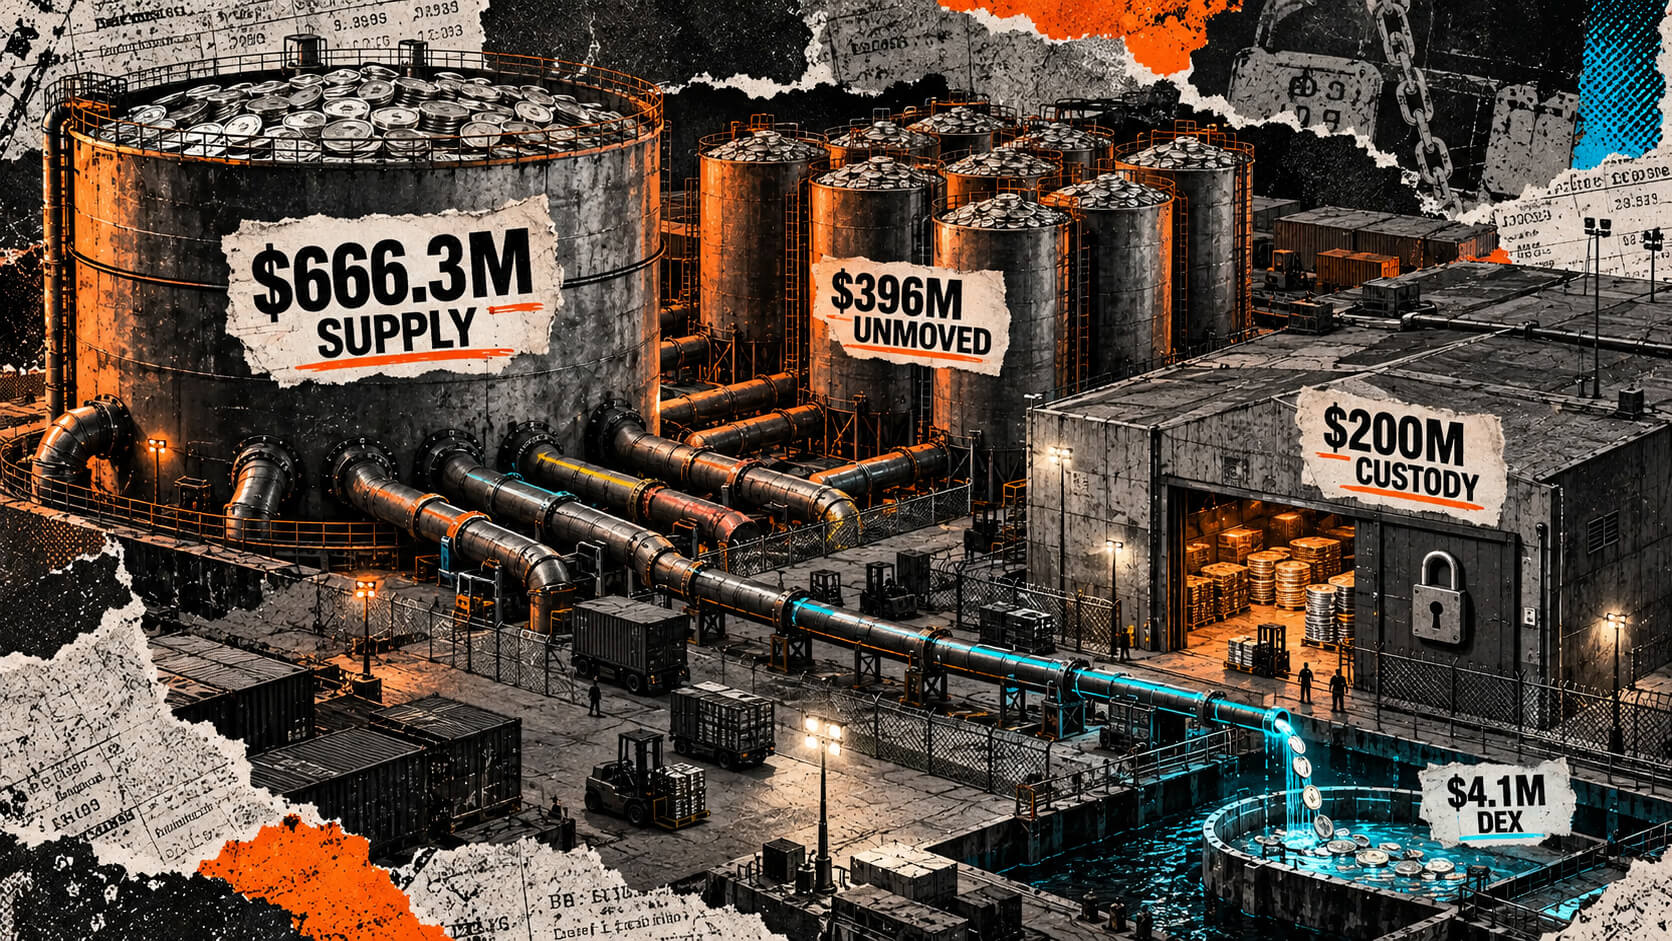
- $666.3 million OUSD outstanding as of October 5, with $396 million locked in eight Tempo staging wallets that have not moved since funding.
- Ten wallets hold 74% of total supply; Tempo accounts for 71% despite hosting only $17,000 in DEX volume in the first week.
- DEX trading totaled $4.1 million across all four chains in six days, or 0.6% of circulating supply, far below the issuer’s stated $1 billion launch liquidity commitment.
- $666.3M Open USD supply outstanding as of October 5
- 71% OUSD supply concentrated on Tempo blockchain versus other three chains combined
- $4.1M DEX volume in six days versus $1B founder liquidity commitment target
Open Standard’s OUSD stablecoin reached $666.3 million outstanding by October 5 after launching September 30 on Tempo, Base, Ethereum and Solana, according to data published by Crystal Intelligence on October 6. The token, issued by Bridge, Stripe’s stablecoin subsidiary, was created by Open Standard, an independent company founded by Coinbase, Mastercard, Shopify, Stripe and Visa alongside more than 200 network partners. Yet according to Crystal Intelligence’s wallet study, most of that supply remains concentrated in founding partner wallets and custody accounts rather than in active circulation or payment settlement.
$396 million frozen in Tempo staging wallets shows heavy partner positioning before demand
Eight wallets on Tempo received between $10 million and $200 million each directly from Bridge on September 29 and have not moved any of those funds since the snapshot on October 5. The largest holds $200 million; the second holds $85 million and appears to be held in Coinbase custody.
These positions represent staged inventory intended to support founding partners’ balance sheets and market-making, not customer adoption yet.
Coinbase separately received $200 million across the four chains on October 1, split into four identical $50 million tranches, one per blockchain. That entire $200 million remains within Coinbase custody accounts. The concentration leaves circulation dependent on a small number of institutional actors.
Tempo’s $17,000 DEX volume exposes the gap between supply and actual use
Decentralized exchange volume across all four blockchains totaled $4.1 million over six days, or 0.6% of the circulating supply. Solana accounted for $3.4 million in trading; Base for $700,000; Tempo itself, despite hosting 71% of all OUSD, managed only $17,000.
The disparity underscores a central tension in the launch: most supply sits on the chain least suited to generating trading activity. Tempo’s own exchange design relies on partnerships and integration rather than open secondary trading, and the chain’s primary function is payments settlement between founding partners rather than speculative liquidity provision.
Transaction fee structures also distort activity measures, Crystal Intelligence classified 73% of Tempo’s 11,544 OUSD transfers as fee payments worth just $3.33 in aggregate, explaining a high transfer count alongside minimal economic activity.
Mints beyond partner placements will determine whether adoption follows positioning
Bridge minted in two discrete bursts: $439.5 million on Tempo on September 29, the day before launch, and $50 million on each of the four chains on October 1, when Coinbase support went live. After October 1, issuance nearly stopped; between October 2 and 4, Bridge minted $1.2 million and burned $3.4 million.
Crystal Intelligence identified the next signals to watch: new mints beyond founder and partner placements, transfers out of staged wallets, redemptions initiated by customers, and sustained Tempo exchange activity. Bridge committed to zero minting and redemption fees and no liquidity restrictions, positioning OUSD as a tool for on-chain payments rather than a yield-bearing asset. Whether that model attracts transaction flow, recurring payments, treasury demand, and settlement volume, remains an open question in the second and third weeks of operation. Aave Labs has already proposed integrating OUSD into core lending markets, indicating institutional interest in deeper protocol exposure once supply finds its way into active use.
The CCS read. Staged inventory tells us where Open Standard expects demand, but not whether it will arrive. The distribution of $600 million to Tempo, Coinbase custody, and bridge wallets reflects the issuer’s bet on partner-driven adoption via integration rather than secondary market discovery. If supply begins flowing out of these staged addresses into merchant payments or settlement within the next two weeks, the launch is tracking to plan. If it does not, headline supply figures will obscure a stalled debut.
Watch for OUSD mints and burns in the week of October 12-18 and for whether Coinbase’s staged $200 million enters merchant or institutional customer accounts at scale. Equally important: monitor Aave governance’s vote on OUSD integration and track redemption volume on Bridge’s infrastructure, which will signal whether businesses are actually using the token for payments or holding it as speculative inventory alongside the founders.