Pump.fun collects $18.6m weekly while 81% of its memecoins crash 90%
Pump.fun collected $18.6 million in protocol revenue over seven days while 81% of established memecoins crashed 90% from their peaks, exposing a structural divide in the memecoin economy where platform profits flow regardless of whether individual token holders recover. For institutional investors, this dynamic raises questions about whether Pump’s expansion into holder rewards can meaningfully offset losses or whether the platform’s economics will continue to depend on perpetual churn rather than asset recovery.
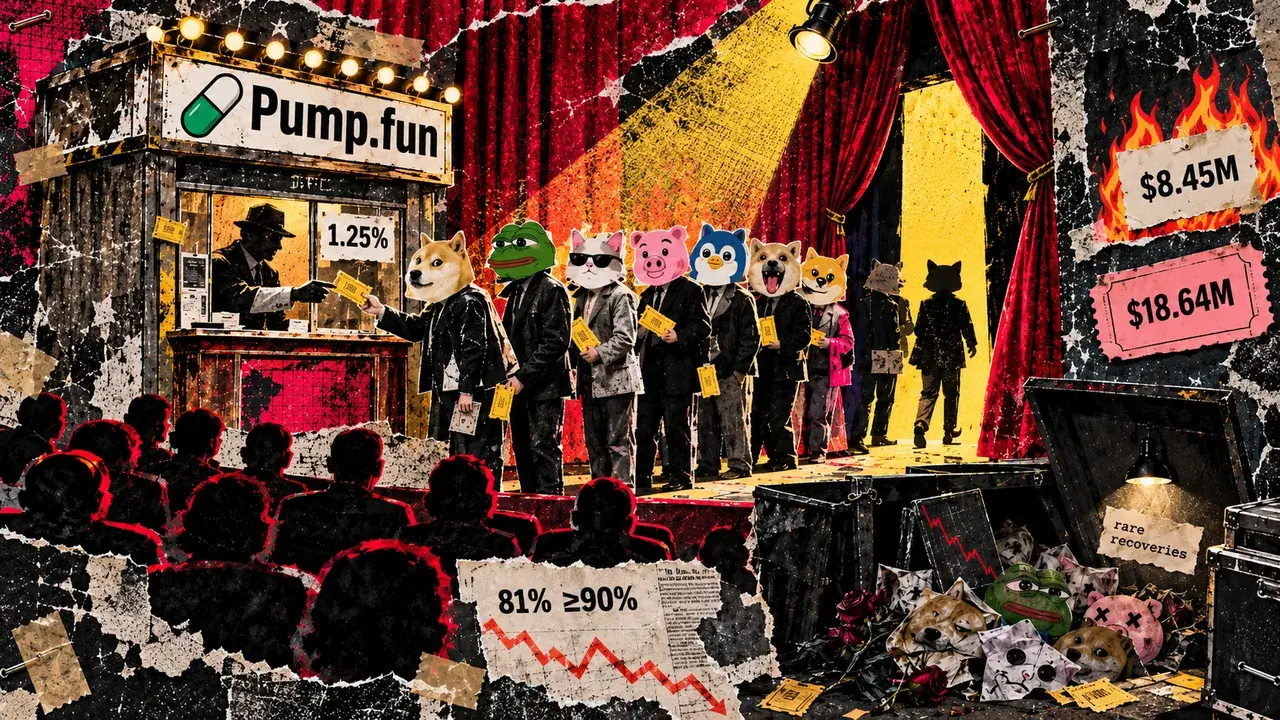
- Pump.fun generated $18.6 million in protocol revenue over seven days through October 7, with $60.7 million over 30 days against $186.2 million in total fees
- 81% of a selected group of 150 memecoins examined by Talos fell at least 90% from all-time highs, with only 5 of 151 tokens remaining above first-day price
- Pump committed to burning $27.29 million in PUMP tokens over 30 days through buybacks, but that mechanism provides no direct recovery path for holders of individual failing memecoins
- $18.6M Protocol revenue in seven days, unchanged as platform processes memecoin churn
- 81% Of memecoins examined collapsed 90% from peak, while only 5 of 151 remained above launch price
- $4.46M Distributed to 140,000 users in 24 hours through rewards programs, compared to platform’s 30-day revenue
Pump.fun’s token launchpad continues generating millions of dollars from memecoin trading even as the vast majority of those assets suffer catastrophic losses, according to DefiLlama data and analysis by Talos Intelligence. The platform collected approximately $52.5 million in total fees over seven days through October 7, with $18.6 million flowing to the protocol itself. Over 30 days, Pump processed $186.2 million in fees and $60.7 million in protocol revenue. Separately, Talos examined 150 memecoins and found that 81% had fallen at least 90% from their all-time highs. The contradiction reveals a fundamental truth about Pump’s business model: the platform profits from transaction volume regardless of whether any individual token recovers or whether traders exit their positions profitably.
Talos study finds 95% collapse common, recovery rare among Solana memecoins
Talos’ analysis examined 150 memecoins requiring pricing on at least one centralized exchange, a threshold that skews the data toward relatively successful tokens. Even among this stronger cohort, losses were severe. The median token peaked approximately 17 days after exchange listing.
Talos defined collapse as a 95% decline from peak and calculated a median of roughly 370 days between that high and the collapse threshold. Only a small fraction of collapsed tokens later revisited previous highs, and just 5 of the 151 coins in Talos’ return sample remained above their first-day price.
Active addresses holding at least $1 per Solana memecoin fell to no more than 7% of their respective peaks, indicating that trading attention rotates rather than returns.
Roughly two-thirds of Solana-era memecoins in the study never staged a meaningful second rally after their initial speculative run. The pattern creates a structural mismatch between how Pump earns revenue and how individual token holders experience the market.
A trader rotating from a fading coin into a new launch generates another fee-producing transaction, and new launches, rotations and speculative bursts can support platform income indefinitely while earlier buyers remain underwater.
Pump’s buyback program burns $27.29 million monthly but does not reach most token holders
Pump committed half of its revenue to buying back and burning the native PUMP token starting in April, a mechanism that gives the asset exposure to platform activity. Over 30 days, the protocol executed $27.29 million in PUMP burns, removing 170.57 billion tokens from circulation. However, that buyback mechanism provides no direct benefit to holders of individual failing memecoins launched on the platform. For those investors, recovery depends on demand returning to their specific asset, sufficient liquidity to exit, and reward distributions large enough to offset token losses.
Pump’s fee structure distributes portions of trading income among the protocol, creators, liquidity providers and, increasingly, through holder reward programs.
Alon Cohen, Pump.fun’s co-founder, said that over a recent 24-hour period, more than 140,000 users collectively received approximately $4.46 million, including $730,000 in Holder Rewards, $330,000 in Callout Rewards and $3.4 million in creator fees.
Cohen stated that “in time, Pumpfun will vastly outperform the social media industry in user payouts & rewards.” Those distributions support Pump’s argument that it is increasingly sharing economics with users rather than retaining them at protocol level. But the three reward categories benefit different constituencies. Creator fees accrue to token launching teams.
Callout Rewards compensate eligible promoters. Holder Rewards apply only to participating coins and do not automatically reach every person holding a Pump-launched asset.
Reward expansion faces a key test: whether distributions can offset token value decay
The distinction matters most when token losses are measured directly against rewards. A holder can receive distributions and still lose money if the underlying coin’s value falls faster. Likewise, a creator can generate substantial trading fees even as buyers who entered near peak suffer deep drawdowns. PUMP holders face a separate equation entirely: buybacks create demand and burns reduce supply, but the token carries its own market risk and does not grant a contractual claim on platform revenue. Scheduled token unlocks can also add supply even as burns remove circulation.
The economics separate as speculation moves through the ecosystem. Pump earns from aggregate trading, PUMP captures part of that activity through buybacks, and selected creators or holders receive fee distributions. None guarantees recovery for investors waiting for buyers to return to older memecoins.
The real question for Pump’s expansion is whether holder reward distributions will grow large enough to materially compensate for declining token values. If rewards accumulate faster than older tokens lose value, the program could alter the economics of staying invested after the initial speculative rush.
If trading velocity continues accelerating toward new launches faster than older coin rewards accumulate, Pump may sustain revenue growth indefinitely while many of the traders supplying that activity remain unable to exit at break-even.
The CCS read. We see Pump’s reward expansion as economically necessary but not sufficient. Platform revenue decouples from holder recovery by design: Pump profits from churn itself, and buybacks benefit PUMP holders, not memecoin holders. Until reward distributions measurably exceed the rate at which older tokens lose value, holders face a geometric choice, sell at loss or wait for a recovery that data suggests rarely arrives.
Watch for Pump’s next quarterly report on holder reward totals. If distributions remain below 5% of protocol revenue by Q1 2027, the program signals that Pump sees reward expansion as marketing rather than genuine wealth redistribution. Conversely, if Cohen’s team commits to a specific percentage of protocol revenue flowing to holders and announces a timeline, that would indicate confidence that rewards can compete with decay. The next material test comes when the first cohort of older memecoins has been dormant long enough that reward accumulation either exceeds or falls below their typical 90% drawdown magnitude.
Original reporting: cryptoslate.com