Treasury yield hits 22-year high, ending crypto’s cheap-money financing era
The 10-year US Treasury yield hit 5.29% on October 1, marking the highest level since 2002 and ending crypto’s era of near-zero borrowing costs that fueled leverage and financing innovation. Institutional investors now face a structural reset: Bitcoin and Ethereum rallied through the shock, but the financing models underwriting crypto treasury companies, DeFi lending, and basis trades have repriced sharply upward.
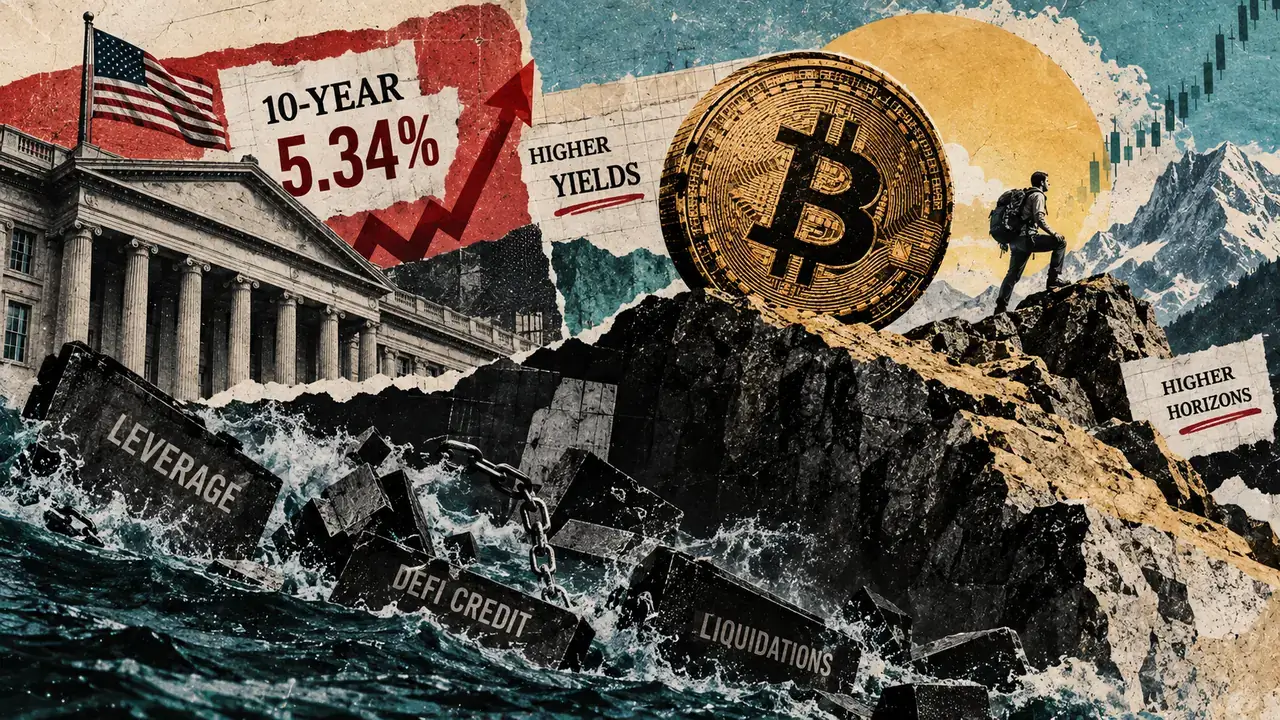
- 10-year Treasury yield reached 5.29% on October 1, up 90 basis points in Q3 alone, the largest quarterly rise this century.
- Bitcoin ETFs drew $6.3 billion in Q3 and Ethereum ETFs $3 billion despite the yield headwind, signaling institutional demand survived the shock.
- Crypto treasury companies now trade at or below net asset value, losing the premium valuations that previously made equity and convertible financing viable.
- 5.29% 10-year Treasury yield on October 1, highest since 2002
- 43% Bitcoin gain in Q3 2026 despite Treasury shock and liquidations
- $6.3B Spot Bitcoin ETF inflows in third quarter alone
The Federal Reserve H.15 release for October 1 put the 10-year Treasury at 5.29%, the 30-year at 5.64%, and the 10-year real yield at 2.93%, a level at which inflation-adjusted government debt now competes directly with a coupon-free asset. That shift marks the operational end of the cheap-money era that enabled crypto lending to thrive.
Even as Bitcoin climbed roughly 43% in the third quarter and Ethereum gained about 71%, the financing infrastructure built around accumulation strategies fractured under the weight of higher funding costs.
Citi raised its 12-month Bitcoin forecast to $113,000 from $82,000, citing stronger institutional activity and ETF inflows alongside adviser and brokerage allocations, but the bank acknowledged that higher yields remain a structural headwind. The story of Q3 2026 is not that Bitcoin won; it is that the machinery financing Bitcoin changed shape.
Treasury rates force repricing of crypto treasury company capital structures
Bitcoin treasury companies, public firms that hold cryptocurrency as balance-sheet reserves, have historically funded purchases through common equity, preferred stock, and convertible debt, according to Skadden. The model worked when shares traded at a premium to net asset value, because issuing stock priced above the underlying crypto value per share allowed management to buy more crypto with fewer shares diluted. At a 5% risk-free rate, the return investors demand on preferred shares and convertible debt rises, the risk premium on common equity widens, and the cost of hybrid capital climbs. Goodwin describes the sector’s compression from premium valuations to NAV or below, with many treasury companies now trading at or below NAV. That gap destroys the financing arbitrage that made the model work.
Higher benchmark rates raise the cost of capital for explicit borrowing and implicit leverage such as perpetual futures, basis trades, options structures, and collateralized loans.
On September 23, a stronger PMI pushed the 10-year above 5.2%, and Bitcoin slipped below $85,000 with $135.8 million of long liquidations in a single hour and $510 million over 24 hours. On September 25, open interest on selected exchanges fell 14.3% as Bitcoin held near $84,000. Leveraged traders bore the damage, not buy-and-hold holders. The fact that equity issuers could not absorb the shock at previous valuations signals that the Strategic Bitcoin Reserve model faces a financing ceiling at current yields unless spreads widen or the cost of capital falls.
DeFi borrowing and stablecoin yields must now clear a 5% hurdle
A 2026 Finance Research Letters study using Aave data found stablecoin borrowing and deposit rates linked directly to US Treasury yields, with the 10-year showing the most consistent explanatory power.
An ECB working paper on Aave examined how restrictive monetary shocks reduce both stablecoin borrowing demand and liquidity supply, with transmission depending on the balance between arbitrage and leverage channels. In the zero-rate era, a 4% or 5% DeFi yield looked attractive against cash paying near zero.
At a 5% Treasury, DeFi products must now cover smart contract, liquidity, counterparty, stablecoin, oracle, and governance risk on top of a 5% risk-free alternative. RWA.xyz lists 108 tokenized US Treasury products, including USYC, USDY, BUIDL and iBENJI, all offering rates close to Treasuries with minimal credit risk.
The San Francisco Fed estimates stablecoin issuers’ Treasury holdings could roughly double to about $400 billion by 2030 if recent growth continues, meaning institutions now have a regulated, on-chain alternative to traditional DeFi borrowing.
That structural shift favors tokenized collateral adoption and reduces the appeal of leveraged DeFi strategies that competed on yield alone.
The CCS read. We see the 5% Treasury yield as the inflection point between two eras: one where leverage and premium valuations funded growth, and one where institutional crypto must compete on fundamentals and custody efficiency rather than favorable financing spreads. Bitcoin proved it survives higher rates, but the companies and protocols that relied on cheap capital to drive activity do not.
If the 10-year falls back below 5% as oil and inflation cool, Citi’s $113,000 forecast becomes the institutional reference, treasury-company premiums could reopen, and tokenized collateral adoption would broaden. If yields hold near 5% and real yields stay close to 3%, Bitcoin can rally in bursts on each data shock, but preferred and debt financing will remain expensive and leveraged trading will face persistent forced deleveraging, the question now is whether institutions will shift capital away from high-yield DeFi entirely toward regulated Treasury products or whether basis trades and spot markets will find new equilibrium partners at higher cost.
Original reporting: cryptoslate.com