Payward acquires Saldo Bank for $181 million to operate EU deposits and payments
Kraken’s parent company is acquiring a licensed European bank for $181 million, marking the exchange’s first major move into regulated deposit-taking and payments infrastructure outside crypto. The deal signals institutional crypto firms are now competing for banking licenses to offer traditional financial services alongside digital asset trading.
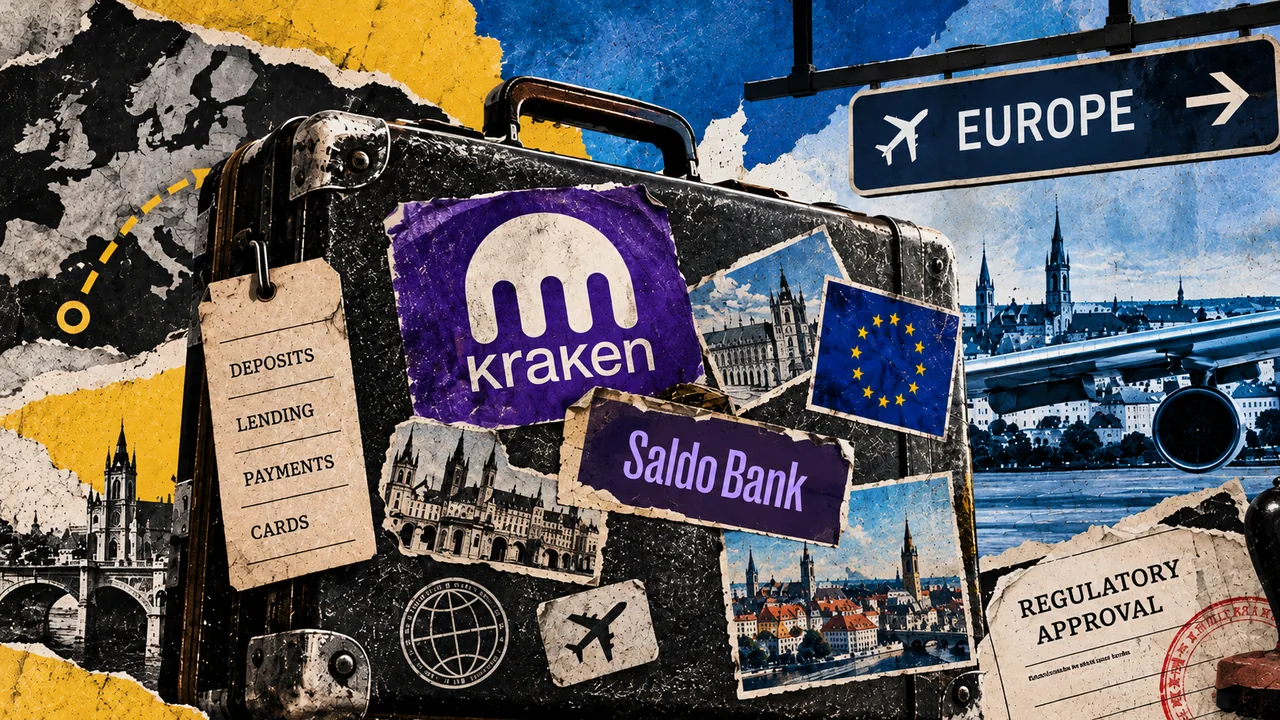
- Payward, Kraken’s parent, agreed to acquire Saldo Bank through its Finnish holding company for $181 million on October 14, 2026.
- Saldo Bank holds a full European banking license in Lithuania, enabling deposit-taking and payment services across the EU under single rulebook.
- The acquisition positions Kraken to offer fiat onramps, staking rewards accounts, and cross-border payments without relying on third-party banking partners.
- $181M Total acquisition price for Saldo Bank, Kraken’s first owned banking entity.
- Oct 14 Date Payward announced definitive agreement to acquire the European bank.
- EU-wide Regulatory scope of Saldo Bank’s operating license across member states.
Kraken is stepping beyond its core cryptocurrency exchange business by acquiring Saldo Bank, a Lithuania-licensed financial institution that will give the San Francisco-based firm direct control of deposit accounts and payments infrastructure across Europe. Payward, the holding company behind Kraken, announced the definitive agreement on October 14 (Wednesday) to purchase Saldo Finance Oy, the Finnish parent of Saldo Bank, for $181 million. The deal grants Kraken a full European banking license, a credential that most cryptocurrency exchanges have pursued only through partnerships or subsidiaries rather than acquired outright.
Kraken gains EU banking license and payment rails independent of third parties
The acquisition hands Kraken operational control over a bank licensed to take customer deposits, issue payments, and offer credit products throughout the European Union under the single rulebook. Until now, Kraken has relied on partner banks to hold customer fiat balances and facilitate EUR and GBP withdrawals.
Owning Saldo Bank eliminates those intermediaries and gives Kraken direct custody of deposits, a competitive advantage that reduces dependence on correspondent banking relationships that have historically cut off crypto exchanges from traditional financial rails.
Saldo Bank operates under the Lithuanian Financial Supervision Authority, a jurisdiction that has positioned itself as a gateway for fintech firms seeking EU banking licenses.
The acquisition also enables Kraken to offer products currently unavailable on its exchange, high-yield savings accounts tied to staking rewards, multi-currency accounts, and cross-border payment corridors that institutional clients demand alongside spot and derivatives trading.
Traditional finance acquisition reflects regulatory shift toward licensed crypto infrastructure
The deal marks a turning point in how cryptocurrency exchanges view regulatory compliance. Rather than remain pure trading platforms subject to varying national rules, major exchanges are now acquiring or building licensed banking entities to control the full stack: trading, custody, lending, and payments.
This approach follows patterns set by traditional fintech firms like Revolut and Wise, which built banking licenses to scale globally without relying on legacy correspondent networks.
For Kraken, the acquisition also addresses a structural vulnerability: many European banks have exited partnerships with cryptocurrency exchanges citing reputational risk and money-laundering concerns.
By owning a bank with its own compliance framework and regulatory oversight, Kraken shifts the risk profile from a trading platform subject to scrutiny to a regulated financial institution accountable to banking supervisors. This positioning matters for institutional investors evaluating the stability and regulatory durability of the platforms they use for trading and custody.
Integration into Kraken’s platform and EU market timing remain open questions
Payward has not yet disclosed the closing timeline for the acquisition or how Saldo Bank will be integrated into Kraken’s existing infrastructure. The deal’s completion will require approval from Lithuanian banking authorities and, likely, EU consolidated supervisors given Kraken’s scale.
Integration could enable Kraken to migrate European users onto Saldo Bank’s licensed deposit infrastructure by 2027, consolidating what has been a fragmented treasury function across partner banks.
The acquisition also positions Kraken to compete with other licensed fintech platforms entering crypto, particularly Gate Money, which launched recently as a multi-asset account combining crypto, stocks and payments. As regulatory frameworks like the Markets in Crypto Regulation (MiCR) in the EU mature, banks and exchanges with dual licenses will have structural advantages in offering bundled services to institutional clients who demand both digital and traditional asset trading from a single regulated entity.
The CCS read. Kraken’s acquisition is not a defensive retreat from crypto but an offensive move to lock in banking infrastructure before the largest institutional investors demand proof that their exchange partner controls its own payment rails. Ownership of a licensed bank removes a single point of failure, partner bank withdrawal, that has repeatedly disrupted the industry. For European institutional traders, this signals Kraken’s commitment to remain solvent and operable even if traditional banking relationships sour.
The next milestone is regulatory approval from Lithuanian banking supervisors and EU consolidated supervisors, a process typically requiring six to twelve months. Kraken’s disclosure of the expected closing date and integration roadmap will clarify whether Saldo Bank becomes a transparent utility for Kraken’s existing user base or a separate licensed entity with its own retail presence. Watch for announcements on whether Kraken will offer fiat savings accounts bearing rates tied to staking rewards, a product that would directly compete with traditional banks offering negative rates to depositors.