
Reid Cuming / Ground
Ground embeds onchain yield into every financial platform
In this episode
Most platforms sit on trillions in idle customer balances every day — and for 15 years, nobody figured out how to turn that into yield without friction, complexity, and regulatory risk. EMBEDDED ONCHAIN YIELD is what Ground is building, and the GENIUS and CLARITY regulatory frameworks just made it viable at scale.
Reid Cuming, CEO and Co-Founder of Ground, joins Ashton Addison on Blockchain Interviews. Reid co-founded Superstate before launching Ground — an API connecting financial platforms to onchain yield. He breaks down why embedded yield beats destination yield products, how Ground wins whether stablecoin yield gets restricted or permitted, and much more.
- Ground builds an API platform that abstracts blockchain complexity to embed onchain yield into existing banking and finance applications.
- Trillions in idle customer balances across neobanks and exchanges remain untapped because onchain finance has been designed for blockchain-native users rather than mainstream consumers.
- The missing piece for wider blockchain adoption is an interface problem, not a technology problem, requiring ease of use comparable to traditional neobank applications.
- Ground's model normalizes access to diverse onchain yield sources through a single integration point, similar to how Stripe simplified online payments infrastructure.
- Demand for embedded yield spans from crypto-native neobanks and exchanges to regulated traditional financial institutions exploring stablecoin integration beyond payments.
Chapters
Transcript
Read the full transcript
I'm Ashton Addison from the Crypto Coin Show, and today on Blockchain Interviews, we have Reed Coming, CEO and co-founder at Ground, connecting financial platforms to on-chain yield, bringing more corporations, big companies, into blockchain, driving more mainstream adoption. Reed, welcome to the show, and thanks for taking the time.
Thank you for having me, Ashton.
Yeah, excited to dive into this because there are still trillions of dollars inside of neo banks and exchanges every day and in traditional finance, and we need to have a common ground, more APIs, SDKs, connections in the back end that allow all of that money to flow on and off chain seamlessly, and just make the financial system work better. I know that Ground is playing a
good part in this, and I would love to start our conversation by just giving a high level on what you and the team have been working on over the past few years, and then we can dive into all the details.
Definitely. So, short answer is we're building the platform to make on-chain finance accessible and embeddable for all banking and finance, wherever it is.
Easy to integrate, easy to use, easy to configure, abstracting away all the complexities of blockchains, of wallets, of gas, of interoperability, of the different systems within. We want to make it as easy to use the a the on-chain financial functions as it is to, you know, use a neo bank app. We think that's been the missing piece for kind of wider use. It's just been
an access problem, an interface problem, and that's the simplest version of what we're building toward today.
Mhm. Yeah, it's super great because I think [clears throat] that neo banks are an upgrade over the traditional slow systems, and I know that blockchain has even more upgrades, but there's just that clunkiness to it still. And although we're, you know, 15 years in
with Bitcoin or, you know, 5 to 10 years with the more smart contract level and on-chain yield products, kind of financial products, there's still some kinks to be worked out and some some tests to be made. I think the legislation has helped put that in the eyes of some of these bigger partners, which we can dive into. I know you have some great points on that, but what do
you think have has been the major barrier from other companies not being able to develop a platform that has the ease of use that Ground has up until now?
I think historically, a lot of development in the blockchain space has been geared and catered toward a more blockchain-centric audience. You know, an audience that is very steeped in the technology and the ethos
of the kind of early adopters. And it really hasn't had the opportunity to really broaden that. Now, we've definitely seen like flashes of this and green shoots kind of over the course of years. You know, with different centralized exchanges really making it easier to access certain crypto assets. But the functions, the financial functions on chain are
still kind of a bit at arm's length. They're not They're not as native. They're not as fluid. There's still a lot of uncertainty around what it is, how it works. And we think that's just not been something that's been really focused on because there's really been just kind of a driving interest in kind of other things. You mentioned like Bitcoin or
altcoins or kind of other other considerations that have driven a lot of interest in the market. But again, the market has been predominantly been geared toward an audience that is already comfortable with the you know, fragility of certain systems or the difficulty of using a app. It's not the you know, typical neo bank user, typical savings account user at a
at a large bank. It's really heavily engaged. And that's mostly begin because those those types of users simply just, you know, don't really want to or need to figure out how to manage a wallet, what a private key is, how to navigate to different blockchains or move between protocols or figure out exactly how to properly, collateralize a position
or understand what an unbonding curve is. It's It's It's still It's still It's still in the framing of a developer context of here's the math. Here's the Here's the CLI. Here's the Here's the system architecture. You know, that's that's one way how computers were sold at one point, you know, give me all the specs, you know, give me the megahertz, give me
the frame rate. But then it you know, we had better interfaces, better design kind of come into place and said, "No, like most people don't want to manage all of that cognitive load to figure out how to make this work for them. It just needs to work for them out of the box." And so that's what we're really driving towards so that someone who is using a savings account
somewhere or has a robo advisor or you know, works with a works with a neo bank, they should literally just have access to the on-chain financial functions in those settings. Not requiring them to download another app or switch screens or figure out the nuances of you know, talking directly to a particular smart contract. It's like no, it should be embedded within their
existing experiences. It just enhances and supercharges what they already have.
Definitely. I completely agree. And so from from what I understand, neo banking, a lot of people love it and they don't want to get new apps to have to relearn everything. and the key is having those APIs, having those back-end connections Ground can work with the neobank. Hey, let's embed this in and
make it as easy as the fiat functions in the neobank, and people won't even know it all of the blockchain stuff is abstracted away. We can start getting yield. We can now move your your USD to USD stablecoin, and you can't even tell that you're using crypto.
That's exactly right. Like you if we rewind time, we're kind of still in that phase of like even like online
e-commerce where pre-stripe, you had to kind of put the pieces together yourself if you wanted to take payments online. You know, talk to the card networks, talk to your gateway, talk to your PSP, and it's like wow, that was a lot of work, very difficult to do. But then a better interface came along that really removed that complexity, packing it for you into
a single API, and then you were able to go off to the races and do what you really needed to do, which wasn't developed competencies in, you know, deep banking infrastructure, deep payments infrastructure. It was No, that's a part of my product. That is not the product. That is not the competency that I have. So, we're we're very much kind of moving away from that
phase, if you will, in the blockchain space for on-chain finance. And Ground is really geared toward exactly that model of, you know, instead of forcing everyone to go to each individual company they would like to buy equity in and request equity from that company. It's like, no, you go to one place. You go to your brokerage. You purchase the stock that you care to
purchase. Similarly here, it's like asking everyone to say, "Okay, go integrate with or as a as a consumer go directly to a vault or go to a liquid staking token or go to an RWA." And you have to figure out how to do it and navigate exactly which of these works for you in languages and in form factors that can change pretty pretty drastically. It's like, no, it's
better to have an interface that normalizes this for you that makes it easy to make decisions and then you just have API calls or buttons to push and that's it.
Mhm. Definitely, let's make it easy. And what's the what's the demand side been like from neo banks, you know, are they require seeing requests from their users? Are you actually reaching out to them and
say, "Hey, this is something that you guys need?" Or are they reaching out to you saying, "We need it?"
It kind of goes both ways. We get some inbound and we do a lot of kind of a going out as well. And really the demand in the market kind of starts with the more crypto native native groups, you know, the neo banks, neo finance apps and exchanges that are already very
familiar and comfortable with on-chain finance, with stable coins. It's either in the workflow or in the product directly. Their clients also are very comfortable with this as well. When we kind of graduate up the up the you know, adoption curve to less crypto native, more regulated, more scaled entities, whether that's our neo banks or traditional FIs of different
kinds, they're really figuring out how to make stable coins work for themselves beyond payments and we think Ground is going to play a really important part there to make make make it so that they can build products that are competitive, that are compelling, that are exciting for clients that want to use stable coins and as they begin to introduce stable coins to the back end systems
more and more and more. So, it really is this interesting moment for the wider bank making and finance space.
Definitely. And since the Genius Act passed with regards to stable coins, I feel like that's opened the floodgates. People they see the news headlines, but they don't have the discussions with these neo banks and institutions like you do at Ground.
How has that momentum shift since the passing of that legislation changed in the appetite to integrate these kinds of technologies into neo banks and traditional systems?
Well, the those companies and neo banks they were kind of already bought in. You know, already using stable coins, already using crypto native things. You know, for them it was it's definitely great cuz it's relief.
You know, not only genius and clarity acts but also some of the statements from regulators in the US really taking off pressure from certain interfaces and others so that they can build and they can do it confidently and innovate really really well. I think what the regulation and you know rule making will take place thereafter is really going to unlock the ability
for larger more scaled more you know, for lack of a better term regulated entities that are really trying to figure out how to make these systems work for them. Really kind of like give them a green light of like okay, there is a there is a road that you can now travel on instead of it being kind of like you know, pioneering. You know, I think I think it's safe to say that most
incumbents are not pioneers. You know, sometimes that is not always the case but usually that's the case. So now they're going to have a road to be able to actually walk on and determine exactly what's going to work well for them. So we think that's
[clears throat]
really where the new legislation is going to really help is enabling or allowing much larger banking and
financial institutions whether those are neo banks or FI's or bass providers, sponsor banks or others to really engage with the functions on chain and the assets there much more concretely than they've been able to historically.
Definitely. And on the clarity side there was a large debate over the yield generation from stable coins and being able to pass that to the holders
of the coins. I think this has been a big battle because the banks they usually have a high interest savings account and usually the percentages are pretty low and what we've seen so far in the in the small growth of stable coins over the last few years is the yields were higher, but even if they were equivalent, there's been an argument that I think from the banks to
protect their yields that the yields should or shouldn't be allowed to be passed to the holders. Are you familiar with this discussion and how that may affect neo banks wanting to integrate the technology?
Definitely. This is like this is a very interesting nuance debate, but it's also fairly easy to contrast. You know, on you know, without naming
names, you kind of two parties. One is the desire to be able to generate yield on stable coins and that's generally where the genius act really comes into play quite quite clearly on what constitutes a stable coin, which is very great. Now we have certainty around what is a stable coin and becomes genius compliant. And with and then within that, you know, what
happens to the yield? Is the yield just held by the issuer? Can the issuer pass that yield on to the holder of a stable coin or is there some restriction? And you know, genius act they there is a restriction on the issuers not being able to provide yield in the form of rewards directly to holders of those stable coins. Now, there's still an aperture
like a window opportunity for distributors, you know, if you will. And then these are exchanges, neo banks, custodians, really anyone that's holding these stable coins on behalf of or in an account controlled by, you know, the end user, the end client. So that they could actually offer rewards. And you know, we've seen this, you know, with some of the larger
centralized exchanges kind of doing this already and you know, it's great. It really does behave like a high-yield savings account and it that perhaps even more so because you get so much more of the of the yield than maybe you would historically. And I think that's kind of the big discussion on like who gets that yield? Is it the depositor or is it the bank? And that's really
where we're seeing this departure of kind of like expectations and desired outcomes. On one side you have, you know, a lot of the banking industry wanting to minimize what yield from stablecoins where that can go, who can get that, how they access that. And then the other side you have, you know, the you know, broader crypto industry saying,
"Listen, that is my those are my assets. They're being put to work. I don't understand why I'm not the kind of net primary beneficiary or why my clients aren't."
[clears throat]
And I think that there's good reason to hold on both sides. You know, the banking industry there the economic models around there are geared toward take deposits in, lend
deposits out, earn more than the interest rates for T-bills. And it's very straightforward and that's I mean, it makes a lot of sense. On the you know, crypto world it's like, well, they don't have those same economic models or constraints kind of built in and there's this ethos of, "Well, those are your assets. Why aren't you just getting like the full
benefit of everything?" And I very much understand both sides of this and I think that the genius and clarity act is really kind of coming to a compromise, which is actually pretty fair to where, "Okay, fine. Issuers of or issuers of stablecoins cannot write yield to holders. Distributors can potentially provide yield, but it has to be in the form of
activity. It can't be just you're holding it at rest and you get it. Basically, holding it at rest almost like replicates the high yield savings account. Instead, it needs to come from some activity that generates the reward itself or is associated to a reward. I think this is a fair compromise ultimately. Oh, I think what has been really healthy about all of this though has been
forcing the debate of like who really gets this yield? Whose yield is this? Like whose money is this in some in some regards? And I think it's forced the banking's the larger banking industry to have to figure out like, oh, maybe if we're earning 3 or 4% it's not okay to just pass back 25 or 50 basis points. Maybe maybe it is worthwhile to figure out how to pass back more to the
holder of those deposits. Now, does it alter some of the economics? Does it alter some of the business models? Yes. But, you know, I think this is where innovation really kind of does quite a lot of good things. It really just forces new ideas. It forces new new mental mental scenarios and really puts forward kind of new ideas on how to actually
build banking financial products. So, I ultimately I think the net result is positive for the industry. The genius and clarity act provides certainty in a variety of dimensions including this component here where yield can be can be put put together. So, I think it's really really good ultimately. You know, I think both sides will be a little bit displeased.
You know, if you start to like you know, actually lay on names of the different parties, there's some degree of displeasure which ultimately that's the compromise, you know. And I think yeah, I think it's really you know, going to be a net benefit though to have all the other certainty in place for the industry. There's still a lot to do. There's a lot of rule
making that has to be done. The job is not finished. But, it's it's a strong step in the right direction.
Yeah, that's really interesting read and I agree. It's a fair compromise to be able to say that you need to do some activity with your stable coins and which I think will help with the growth of the industry or the velocity of money. So, for example,
if you lend you want to lend out your stable coins or you want to put it into liquidity of like a decentralized exchange or something like that. Are those valid activities? And is that something that Ground can actually help with in the neobanks to make it like a one-click thing?
That's exactly right. Definitely a valid activity. And I think there's all
kinds of other activities. And you're right, I think I think it's not a bad incentive, right? Like just parking dollars and like, you know, pushing it to the US government is like it's it's not a bad way to earn yield, but it's, you know, I [snorts] think it's good to have incentives that kind of generate more activity. If we look at the blockchain space, I
think more activities generally good, generally valuable for the industry, for the for the on-chain economy. So, it's a positive thing. And you're exactly right. Ground helps with this so that it's very easy for clients of ours, whether B2B2C or B2B to integrate Ground to generate yield using on-chain financial functions. And those can be
crypto-native things like crypto-native sources of yield like borrow-lending protocols, like the staking tokens and others. And we're potentially going to be introducing RSLA's as well in the future. And by engaging in those activities, clients of ours will be able to potentially not only earn the yield from the stablecoin itself, depending
upon, you know, how how things are arranged for them, but also on this additional activity. So, it's really a net win for everyone. The platform that's facilitating this, the platform integrating Ground, the end client, whose whose dollars or assets these really are. I think everyone benefits from this added effect of more activity and allows for
quite a lot more free-ranging choice versus just kind of, you know, take some T-bills and that's it.
Mhm. Definitely. You mentioned RWAs there. Is that something, you know, what's the what's the timeline on that part? I think it's been a big narrative for a couple of years, but getting the right assets, we're already starting to see, you know, money market and like the
basic assets being tokenized and eventually we're getting into equities and other real estate, real world assets and things like that. Where are the discussions at with ground and the neo banks and integrating other assets?
Yeah, yeah. Kind of all not all over the map, but there's a high demand for tokenized assets. You know, the assets that I have
reserves or have begin their life cycle off-chain. They're brought on-chain. There's a lot of desire for that for the type of assets that those are. The safety, the security, the risk, the liquidity, the yield profile of these are just different than what you get from crypto-native sources of yield. What we're generally finding is a desire
to have access to track around a risk curve to where you can start on the very low end, I high yield or low yield, low risk, high liquidity, and then track up further to where obviously get less liquidity, higher risk, but higher yield. And then there's a desire to kind of find portfolio mixtures kind of in between that really accommodate clients'
you know, ultimate goals of, you know, where do they want to sit for liquidity, for risk, for yield, and then the ability to maneuver as those underlying positions change, and they can just kind of slide up and down this risk scale at will. So we're definitely seeing a lot of interest here. And I think that's really kind of what we're seeing
broadly across the industry. You know, the original RWA is obviously a stable coin. It's done very well. And now it's really about what's, you know, tokenized cash is great. What's better than tokenized cash? Okay, tokenized government debt starting with T-bills. Then we kind of track up to other forms of assets, commercial paper, munis, private credit, stocks.
And private equity maybe in the future, real estate in the future. But today we're kind of seeing a lot of the interest kind of start with the most easily defined, understandable kind of asset classes. And those are US government debt, commercial paper from reputable issuers, and you know, the beginning flashes of things further up the risk curve, which is
exactly what you would expect. A lot of kind of the distribution really being in that class of highly liquid, relatively safe and easy to understand, but still, you know, a reasonable yield that someone can can can rely on.
Yeah, I agree. The risk curve it can it's good to start low and work your way up as you're integrating new
technology. I feel like there's a lot of benefits to having these debt-based instruments, and low-risk things like T-bills. I feel like for the average young investor, that's not even in their mind. But if you had a tokenized version that was in the neobank, and it was a one-click thing with an option showing like safe, low yield, I feel like a lot of young investors
would take advantage of that.
That's exactly right. And it ultimately we want to make it so that all of our clients can embed on-chain financial functions, make the proper disclosures, but it really does kind of fully, you know, go in the background. Blockchain is not the front and center thing that it kind of is today for a lot of the blockchain audience.
It really becomes an infrastructure layer to where you're not really questioning it. It works. It behaves as expected. You know, I think it's it's one of those interesting things where I want the space to get to a point where you know, you're not asking your neo bank or your broker where they the company of the equity that you have
of like, are you using AWS or Google Cloud?
Yeah.
To host everything. You're like, or to store data. I think that's very much the same same outcome we want here to where there's less of a questioning of the infrastructure and we want to help build more robust components that kind of encapsulate all of the on-chain functions so that it really does kind of
fade to the background and it's not not something that is promoted so predominantly, but it really is just the a natural integration point for access to particular types of assets, to particular types of financial opportunities. And it that's just what it becomes. You know, very much a infrastructural component to a larger array of products at a neo bank. That's
where we think the future needs to go where, you know, on-chain finance is ultimately increasingly just in the background, slightly invisible. Certainly can be exposed very directly if desired, but not not necessarily something that is pronounced so prominent in an experience.
Mhm. Definitely. And speaking of figuring out which providers you don't
need to know in the back end, I'm curious on the growth of interest in institutional DeFi versus some of the negative news that we've seen in DeFi. Maybe more on the degenerate side in the first half of 2026, there's still hacks or exploits in decentralized finance, even ones affecting Ave, you know, the biggest platform because they have so many partners and
integrations. One thing over here can affect the whole platform. Is that a thought that's still in the minds of the institutional DeFi partners that you're speaking with and when I get that yield, I do I need to know where it's coming from in the case that this situation happens?
certainly, absolutely. In fact, some of the deriving motivations for
clients of ours that are not just you know, smaller neo banks, but also those that we're having discussions with that are much larger. There is this really strong, you know, recognition of you know, all financial products are are not, you know, there's no guarantee. But under these conditions of where there's a possibility of there being an
exploit that is not tied to the financial outcomes of deploying assets, but you know, a technological exploit that really you know, drains assets. That's just viewed as like very, very unacceptable and I think that's correct. Very, very correct. What we're really seeing is this really strong emphasis on transparency, on control and the
ability to take action rapidly if a particular you know, on-chain yield source or on-chain function or venue begins to behave in ways that our clients do not do not anticipate or do not do not desire to be a part of. And that can be just purely on the financial side of things, like, you know, okay, liquidity is constrained. I do not you know, some clients do not
want to be in constrained constrained opportunities. Others are really kind of focusing this quite a bit on the security side, the operational security side of the underlying. And coupled with that sort of desire for transparency, configurability is really a lot of the driver for access to RWAs to where okay, one way to remove this risk is to use tokenized
assets that simply do not have that same sort of risk profile all together. And that's what we're seeing quite a lot of demand for increasingly, which I think is ultimately incredibly incredibly good for the industry at large to push push more toward tokenized assets, real world assets. I think there's this like great world future where you look at the total
value of assets on all blockchains and it increasingly is not crypto native assets. It is real world assets, tokenized assets that are simply using the technology to provide better products, but it is still steeped in kind of the security and protections of a non of an off-chain reserve of some kind. I think that's really where the future needs to go and I think it's
going to be really really exciting to have helped build that at ground.
Definitely. I agree and I think you know, these meme coins and the early blockchains were were testing grounds for the technology and now that it's over a decade in and some of the kinks have been worked out, they're still there's still some there, but and legislation has been starting to be put
in place in certain pieces, we're now ready for the onboarding of the low risk pieces of the financial system and it's super exciting turning point because there's trillions quadrillions in derivatives that are ready to come on chain and like we're just at like day one here.
Completely agree. Completely agree. It's still, you know, still early
as as we all like to say. But it really is. You know, I think technological shifts and innovations like like the blockchain do not happen overnight. You know, there it is a you know, it is a it's on a on a growth trajectory, but it is not somehow linear. There is kind of starts and stops, fits and starts, but it is projecting kind of upward. And it's it's been really really great to
see just like so much engagement from the more institutional components of the banking financial space. You know, we're seeing particularly for tokenization and RWAs and even just using the technology technologies themselves, stablecoins as well as on-chain finance. And we see this with the Nasdaq. We see this with ICE. We see this with DTC. We see this
with much larger FIs, Franklin Templeton, Fidelity, even JP Morgan. So it's really really great. And this is all happening while you know, some of these security vulnerabilities have been exposed in some of the underlying technologies. Ultimately, those are going to be shored
up and I think they'll be just kind of an ongoing effort to continuously do so by by these by these the those that are managing or building on these platforms. But it's very it's very heartening to see just still a lot of progress made regulatorily, a lot of progress made at the institutional level for these technologies and for these these assets on the blockchain.
Definitely. And you know, it's it's a it's going to be a long journey to onboard everything step-by-step, but where do you see the industry in ground 12 months from now in the summer of 2027 in an ideal scenario?
It's always hard to make predictions, especially when you're talking about banking or finance as you know, a lot of things can change depending
upon macro environments and things kind of out of your control, but I would say that you know, a year from now we're going to be in a much different place. You know, the I ideally the clarity act has passed. I think there's a window of opportunity. There's some growing urgency to try to get it done this year. And we'll get into rule making and I think that's going to be
just this very very different world where you have these you know, these bullwarks, these pillars in place that really make it clear on what is possible. And so I think, you know, a year from now we're going to have much more robust systems kind of at the protocol level to really be able to monitor and manage the security risks that have been you know, really really unearthed
over the past several months. But then I think we're also going to see more and more adoption kind of building on top of the stablecoin wave, the dollarization effect outside of the US, stablecoins picking up there and penetrating that in states. A lot of discussion and I think we'll see this more and more around tokenized deposits. I think all of that
is going to generate this sort of you know, critical mass of okay, we have stablecoins, we have we have tokenized tokenized deposits and it's going to kind of push everyone up the risk curve of like, what do I do with these things? Oh well, I you know, I can put them into a crypto native sort of the yield. I can I can can put them to work using crypto native assets. I can also
do this with tokenized assets. So, there's going to be this supply and then the demand is going to meet supply. So, I think we're just going to see just a continuation of more assets put on chain, whether they're stable coins or tokenized assets, and a lot more healthier systems put in place to make those more valuable.
All right. And you know, the Ground team
just closed a 3.6 million dollar fund raise as it as well. First of all, congratulations on that. And you know, with the vision that you've just given for the industry in the next 12 months, how do you expect to, you know, utilize this capital to the maximum efficiency to help make an impact in making that happen?
Yeah. It's been a been a really eventful
year for Ground with the fund raise, with bringing on team members, launching the product quietly and then announcing earlier this week actually. You know, we're going to be very very aggressive. We think the puck and where the industry needs to go and where Ground wants to move is towards not just this better interface, but also more safe, secure, compliant platforms and
systems that can really cater to those sorts of requirements and demands from the broader banking and financial industry. You know, I think we've gone the whole industry has gone a very long way by focusing quite a lot on a very crypto native audience, but the future is not going to be strictly crypto native. There's going to be needs to make the products really
resonate with those that are not familiar with crypto, but also have these sorts of risk, security, safety, and compliance requirements. And that's really where we're going to be leading into very very aggressively over the next 6-12 months as building the system for that, building the platform, the interface, and the frameworks necessary for our clients
to be able to really engage with on-chain finance, but with those sorts of, pillars in place. So, we're really excited for the rest of the year, to build in that direction.
Yeah, I'm super excited for you guys. I'm looking forward to opening up my banking and neo-banking apps and being like, "Okay, we're on-chain. Let's, let's start deploying
these, you know, crypto capital stablecoins, without having to go back to the old days of, the private keys and all of this, stuff that, you know, my grandma would never bother to do. My grandparents with their wealth fund can now start getting on-chain without any knowledge of crypto keys.
That's exactly right. And you may not even know that, you know, on-chain
sources are being used. You know, it may not be the most important, aspect of that of that product. That's what we want to enable, so that, people can interact with the superpowers of crypto. They can get better financial products, but the products can be built, but without requiring everyone to be so enmeshed in it and,
you know, read into with all of the complexities of the blockchain. So, it's going to be an exciting year to, to make that, make that happen.
What's the best way to follow along with the updates and the integrations and so I can see, you know, how close you guys are to integrating into my favorite app?
Yeah. Ground.tech.co is the website.
You can obviously see, what we have going on there, kind of very directly. API docs are public. You can, create an account to, play around in the sandbox mode before really onboarding. But you can follow us on Twitter. Again, that's ground_onchain and we're on LinkedIn as well. So, come come find me, come find ground, and
we're pretty excited to, to help help people build on a very solid ground.
I love it, Reed. Thank you so much for the time today. All the best with Ground. Congratulations on the raise and let's move the future on chain and would love to follow up in the near future.
Fantastic. Thanks for having me, Ashley.
Related coverage
 WOO X launches MiCA-compliant European exchange with Kraken infrastructureSep 29, 2026
 Brave’s Rewards Card waitlist doubles to 131,000 before an issuer is namedSep 20, 2026
 ECB decision may weaken dollar this week without easing credit conditions Bitcoin needsSep 8, 2026
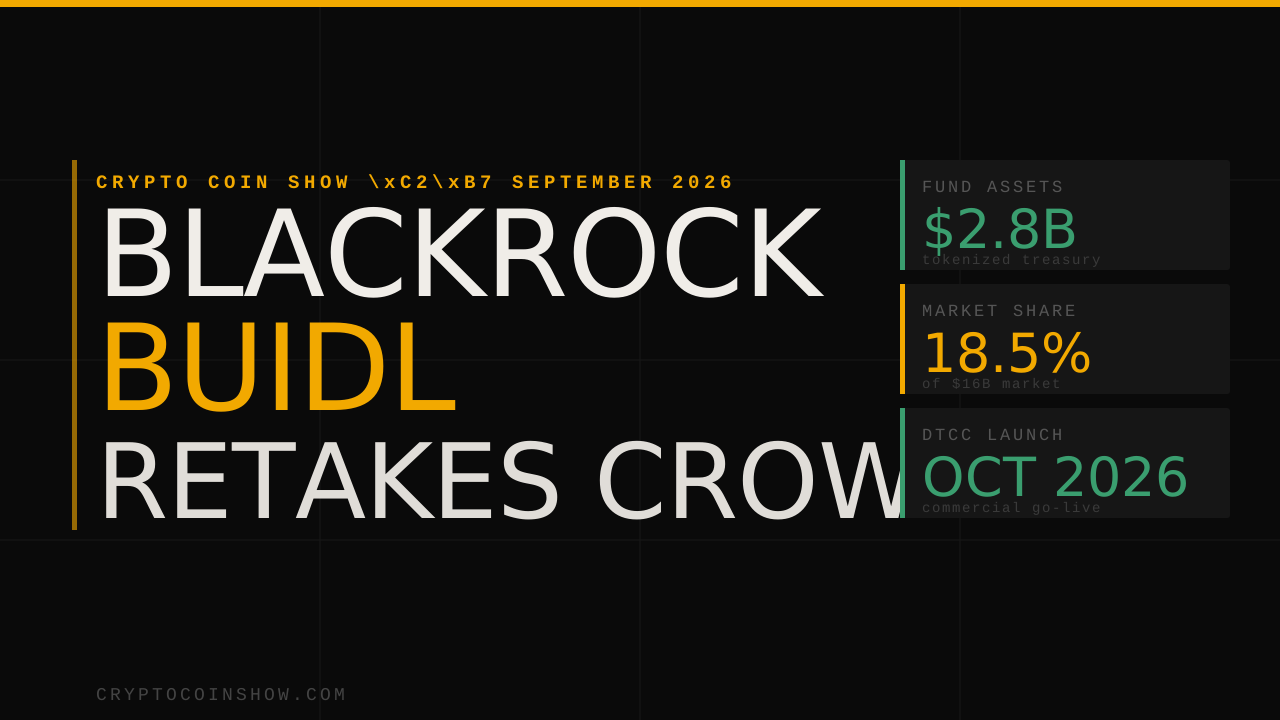 BlackRock’s BUIDL retakes tokenized Treasury crown at $2.8 billionAug 31, 2026
More interviews
 How Robinhood built its own blockchain to control compliance and feesSep 29, 2026
 Geo Protocol founder Yaniv Tal launches Geo Debates, its first productSep 28, 2026
 How Brave is expanding beyond ad blocking with Drew PotterSep 27, 2026
 Why Kevin Carter thinks China is winning the AI raceSep 25, 2026
 Brave's plan to bring self-custody payments to 120 million usersSep 18, 2026
 Arie Trouw on why AI agents now need proof of actionSep 14, 2026