
Lux Thiagarajah / OpenPayd
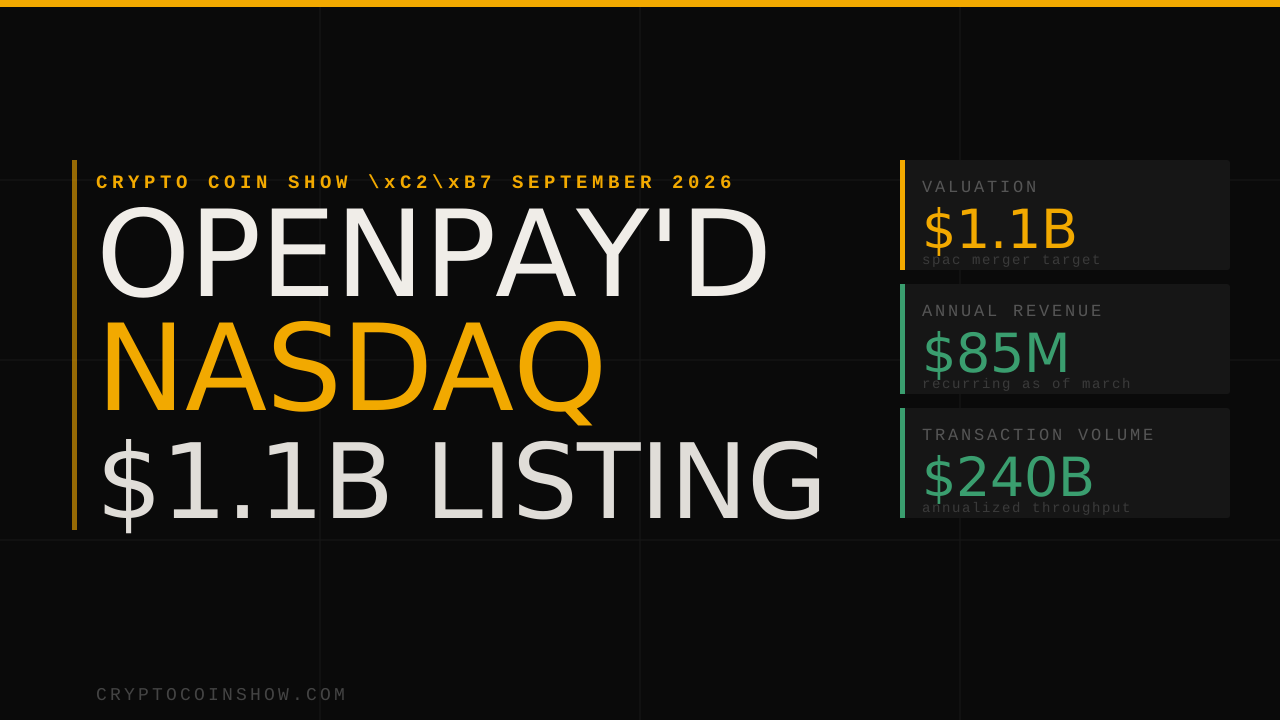
OpenPayd settles cross-border payments in minutes across 38 currencies
In this episode
Cross-border payments still fail in 2026 — and most businesses have no idea how much settlement delays, FX spreads, and fragmented banking are quietly eating their margins.
Lux Thiagarajah, Chief Commercial Officer at OpenPayd, breaks down how modern companies scale payments across 38 currencies, handle stablecoin settlement via USDC and USDT, and replace slow SWIFT rails with infrastructure that settles in minutes. From the Genius Act's impact on enterprise stablecoin adoption to replacing the dollar leg of FX trades with USDC, this is a practical look at where payments infrastructure is heading in 2026.
You’ll learn:
- What OpenPayd provides that most teams should not build in-house (accounts, payments, FX, reconciliation)
- Where reconciliation breaks and how strong ops teams make it automatic
- When stablecoins help in payment flows and what must be true for enterprise adoption
- How founders should think about FX risk, pricing, and transparency
- What “reliability” means in payments infrastructure (uptime, settlement certainty, controls)
openpayd.com · Watch on Refinitiv
- OpenPayd provides multi-currency accounts across 38 currencies with embedded KYC, AML, and reconciliation through a single API integration.
- Regulatory fragmentation, high licensing costs, and difficulty securing banking partnerships remain significant barriers to stablecoin adoption for institutions.
- Companies should partner with EMIs offering multiple banking integrations and redundancy rather than relying on single banking relationships that create failure points.
- Modern payment infrastructure must bridge traditional fiat rails like SWIFT with blockchain-based stablecoin settlement to truly enable global money movement.
- Startups scaling internationally face overwhelming complexity with payments, FX, and reconciliation across multiple jurisdictions without proper infrastructure partnerships.
Chapters
Transcript
Read the full transcript
I'm Ashton Addison from the Crypto Coin Show, and today on Blockchain Interviews we have Lux Fe Garaja, Chief Commercial Officer from Open Paid, here to talk about financial infrastructure, behind the scenes, how payments businesses can scale across rails and geographies, the importance of stable coins in small and large businesses, and how embedded
finance is colliding with digital assets here right now. Lux, welcome to the show and thanks for taking the time. No, Ashton, thanks for having me. A pleasure to be here. Yeah, excited to dive into payments, especially with stable coins for small businesses and all the businesses in the world that have yet to open the floodgates to crypto and digital assets and or maybe don't know
that there's can be a lot of benefits over traditional payment rails, especially when you're doing globalized commerce. We'd love to kick off our conversation with just a bit of a high level on your work at Open Paid and the vision for Open Paid and then we can dive into all this infrastructure. Yeah, sure. No, so Open Paid, I mean, at its core, the best way that I could
describe what we're doing is we're trying to build that universal financial infrastructure for institutions to be able to move and manage money globally. And I think the key distinction for me really in the company in the last couple of years has been what that movement looks like, that movement of money. Previously, when we thought about moving money, we thought of money as
traditional fiat and we thought of it over traditional rails like Swift. You've got separate in the UK, you've got FPS you've got separate in Europe, you've got FPS in the UK. But that's what we thought about traditional rails and money movement. And I think now you've got to bridge that or combine that with our blockchain and you've got to think stable coins now.
So for us, that's really what we're trying to do is build that ability, that infrastructure that's universal and can truly mean that clients can move and manage their money, but that incorporates not only the rails of the past or the traditional rails of fiat, but also merging them with those of blockchain. Definitely. And the easier you can move
money, the easier you can do commerce. And now with the introduction of more modern APIs or just stable coins, theoretically, it would be so easy if I just, you know, could open my stable coin wallet and send you the stable coins and it would be as easy as that. But it seems like money is still hard to move in 2026 despite this technology. Can you talk about some of
those barriers and why it's not as easy as it should be? Yeah, I think there's I mean, I'll be honest, there's a few and most of them aren't fun or sexy topics. I mean, one is regulation. You know, that there's still you know, we've had great regulation in the crypto space of late. I mean, we've had MiCA, which is coming into force now, which is great.
We obviously then had the genius act, but it's still feels fragmented and it's not unified across the globe. You know, we've got Europe in the US, but like being in London, we still haven't seen the UK move really. And when you think about it, we're in 2026, crypto's been around a long time. And with that sort of slowness, it means that companies don't feel comfortable
really coming into that this space as much, especially that institutional flow. So I think regulation has been a barrier to entry and can and will continue to be sadly, even though some jurisdictions are opening up. I think there's been a slowness for people just to really embrace that kind of stable coin infrastructure just because it's not their area of
expertise. Because of the regulation side of things, people just haven't got the internal sign-offs needed to kind of incorporate it into their treasury movements or into their their product stack. Like at Open Paid, for example, we took the decision quite early on that if we were going to be a payments firm, we had to move into blockchain and crypto and stable coins.
I think a lot of companies still still haven't got there. So yeah, for me it's the regulatory burden. It's the fact that we're still not as advanced as probably the market would like us to be in terms of up uptake, even though we are processing, if you think about stable coin processing, it's it's it's huge. And also just costly. I think you know,
it's costly to get the right licenses. It's costly to get the right banking partners in different jurisdictions. This all takes time, this all takes people, this all takes ultimately ultimately money and this also is a massive barrier to entry, I think, for a lot of firms. Definitely.
[clears throat]
What do you think breaks when someone starts
an online business and it's so exciting, but then they realize there's payments and foreign exchange and reconciliation and they have customers now in 20 countries in the first month and it can be a little bit overwhelming, I feel like. Yeah, I think it is and I think you know, and that's why companies like Open Paid exist, right? Because ultimately, if
you could be any client and really or you could be any institution and go and get a bank account depending on which vertical you operate in, but you know, you could try and go and get a bank account at HSBC in the UK. The problem is does that bank appetite A support your business and the risk appetite of your business? You know, as we still see crypto companies still struggle to get
tier one banking partners. The other problem with that approach is there's a there's one source of there's one centralized location of failure point in my mind. If I go and if I'm a company and I go and get one banking partner to service my business, what if that banking partner either has technical issues or has regulatory issues or has to switch off?
You then suddenly feel that you can't service your business or if you suddenly need to service, as you rightly say, well, I've just onboarded 10 new clients, but they are in different jurisdictions. I don't have those rails. And it's why I think companies like us exist really where this is where those sort of companies should be looking at for these EMIs for
their first ports of call because Fintechs like us, we have multiple banking partner integrations that service different verticals, whether you're in crypto, whether you're in financial institution, whether you're a CFD or FX shop or whether you're in gaming. With that, we have more than one banking partner, we have redundancy. So if one fails, we can switch it over to
another. So one, it gives companies the ability to scale up quicker. It gives them continuous you know, support for their banking rails. But yeah, I absolutely agree. I think in this day and age, I think companies have to be a bit more strategic about who they partner up with because otherwise you're ultimately going to throttle your business even before it's taken off.
Definitely. Can you talk to me more about that situation? Say I have a new online startup. Maybe I'm not familiar with crypto intricately either and I have clients in multiple countries. How does that work easily for me working with Open Paid with different currencies, whether it's fiat or crypto? Yeah, so ultimately through one API integration or you know, even clients
who don't use an API integration but want to use our standalone platform or our user interface, we are able to give our clients multiple or multi-currency accounts and these go up to 38 currencies that we now can provide. So if you need a euro account, we can open you up a euro account. If you then need to switch on sterling, dollar, Swiss franc, Australian dollars,
you know, dirhams for the UAE, we can switch that all on immediately as in it doesn't need to take any more further onboarding, there's no more further KYC. We obviously do transaction monitoring on our side, so there's a lot of KYC, a lot of AML that's embedded in our platform and processes. Absolutely, don't get me wrong, it does not mean that should be outsourced. Like every
client should be running their own processes, but we've also got that all in-built and this is all through the API as well. We everything is reconciled all through our API. Our clients are able to track every single cent or dollar or penny that comes into their account and they will know, okay, well, Ashton Addison sent me exactly $10.35. They'll be able to track that with a
unique ID reference. We've got webhooks when it comes to our API. So this all makes the operational sort of complexities a lot less burdensome. But really from just a go-to-market and kind of growth point of view, we can not only give our clients up to 38 currencies, we can then also do all of their FX trading. We can also, in addition, be their crypto on and
off-ramp provider. And we can actually also provide them crypto wallets. So they can accept crypto payments and make crypto payments. So really then you if you think about a company sort of in its in its nascency, through one provider, you've got multiple services and multiple redundancies and that's one KYC, that's one annual review, that's one set of
fees you're paying as opposed to having to do five different onboardings and then do five different KYCs and then do five different annual reviews, which gets burdensome and gets costly. Yeah, definitely no fun. It would be nice if the bank would just take my stable coins directly. Maybe in the future that will happen. Yeah, we're not we're not quite there. I
mean, the day that will happen, I will I think that's the day I'll happily ride off into the sunset and think job's done. They finally accepted us. Yeah, I mean, it feels like I still don't know if that's the case because it feels like the banks are going to want to, you know, digitalize their own currency first before they accept, you know, the likes of USDC USDC and
others. But hey, you know what? That is still a step in the right direction because it shows the credibility and legitimacy of blockchain Definitely. Well, it feels like when you use the traditional banking infrastructure, it's like you against them. Like, oh, we got to move to this currency? Okay, that's going to be a huge surcharge. Or you want to, you
know, a transfer, you know, there's fees on this, fees on that. And yeah, that's their business model, but that's part of the reason why companies get into stable coins or other fintech platforms is because it's a better deal, right? Yeah, I mean I think look, I think and when I think before blockchain really, if I was sending a cross-border payment,
I had absolutely no idea what final amount would end up in the in the in the in the receiving country, right? Or the beneficiary's account. You know, I would see on my side, okay, it cost me this much to send a swift payment, but then there are plenty of times when you know, you're you're trying to settle an invoice and you know, your counterparty is calling you up saying, "Oh, you're
you're $50 short." And you're like, "How on earth am I $50 short?" Well, you didn't see those opaque correspondent banking fees. There's a correspondent bank on this side of the Atlantic, there's a correspondent bank on that side of the Atlantic, and then there's the FX fees, which they are nowhere near where the FX markets are, let's be honest. You know,
the rates that I see on Bloomberg, on Reuters, we are talking, you know, multiples of like percents away. So, what blockchain gave really is transparency. And not only transparency, which is important because at least you can, you know, from a finance team point of view, you know exactly what your costs are, but I think also from an operational point of view in treasury movement, it
let you know when your funds were going to be received or sent out. So, it means that businesses can operate because a lot of businesses don't have, you know, endless pools of capital that they can dip into to run their business. They are dependent on that money landing by this point, and then I can deploy that capital to make payroll, or I can do it
to pay my vendors. And without that kind of transparency, it's you wonder how we used to do it. But now that we've seen what it can be like, it just feels it feels very tough to say that we won't we'll be walking away from this now. Mhm, definitely. With you know, we gave the example of if I started a small business, an online store in 20 countries, I
feel like there's a lot of people that are just starting up small businesses online. What are the ideal businesses even that you're working with right now? Is it small businesses? Are there actually large enterprises? Is it more crypto native that understand, hey, we can use the stablecoin feature for this? I mean, OpenPayd, we're really kind of vertical
agnostic when I think about the verticals that we operate in. We service more than one. So, we definitely do have a large number of digital asset names, but then within that digital asset vertical, we have the huge enterprise names. So, you can imagine the largest exchanges in the world are our clients that we power their payments. You know, we do their
euro payments for their European operations, we do their cross-border payments, we do their effects. We even do some of their on and off-ramping. But then within that digital asset vertical, we also service startups, you know, five-people big companies who are getting into blockchain for the first time and, you know, either doing something like a cross-border
remittance, a money remittance company who are using stablecoins to move money from the US to the UK or US to Europe. So, for us, we have a wide range of clients, and also, and you know, we'll always be that way because you never know who the next big enterprise is going to be. And so, for us, we love backing well-thought-out companies who have got a vision.
The most important thing for us is we always look at the institutions we're working in terms of the leadership, in terms of their licensing, their regulatory footprint. You know, the key thing for us is always always, do they have the right license to do the activity they want to? That's the first box that we need to get ticked. The second thing is we always also look
at, you know, what's their history, where do they used to come where do they come from? Not that's a prerequisite, but it's always interesting because as I said, you never know who the next, you know, Kraken is going to be or the next crypto.com will be. But no, like in terms of the enterprises, you know, whether it's CFD FX brokers, financial institutions, they
range from ginormous enterprises, but all the way down to very new startup companies. Definitely. And on the stablecoin side, how did the introduction of the genius act, at least in the US, warm up to the clients that are using OpenPayd, not just for fiat, but for stablecoins? What do you think about the appetite of using stablecoins in non-crypto and tech businesses?
Yeah, so I think that's the biggest shift I've seen in the last, I mean, let's call it 12-18 months, but really since the genius act, it was the adoption of stablecoins by these enterprise names that you kind of mentioned. You know, when we look at the range of clients we have, I think those using stablecoins would generally they either were digital asset
native firms, you know, like the big exchanges were always using them. But when I look outside of that vertical, the only companies that were using stablecoins were probably startups who kind of who saw the vision and were like, we want to get into it. What we didn't see was large FX and CFD companies, for example, or large financial institutions use it. But, you
know, if you look at the headlines over the last few year couple of years, it's been MasterCard, Visa, Stripe, you know, Stripe with the acquisition of Bridge. What you're now seeing is non-crypto native enterprise names adopting stablecoins, and that's the difference we saw. I think as soon as as soon as you know, President Trump and the genius act sort of all got done, there was that
massive race and adoption by the big enterprises to come in. So, that's the shift we've seen where we've seen our non-crypto native large clients start embedding stablecoins into their everyday operations. As for the sort of on that scale of our client size, towards the lower end of the scale in terms of size, they've been using them for a long, long time, and they're just
using them much more now. Like we've seen a lot of their volumes grow over the last 2 years because I think a lot of these these startups that started 2 years ago have suddenly become mid-size companies now in this space. That's very cool. There's always been a separation between fiat and foreign exchange and then stablecoins or digital assets in
general. It's like you could do it all in the bank, but then if you wanted to get crypto, you had to open a separate crypto exchange, and it was like, it's this foreign country way over there. Is that converging within OpenPayd, you know, doing FX transactions between different fiat and then going to stablecoins? Is that converging? Yeah, I mean,
it is definitely converging. I think what I'm seeing I mean, what you see more of is previously, when someone wanted to do a euro to dollar conversion, let's call it, right? Euro-dollar is the most, you know, actively and largely traded FX pair in the world. You now we now see a lot of that trade happening via a stablecoin. And the reason is for that
settlement leg because instead of doing euro versus dollar, they're doing euro versus USDC or euro versus RLYUSD or euro versus USDT. Because ultimately, when you think about that, why would they do that? Well, it means instead of sending dollars in for example, if a client had to sell dollars and buy euros, the first thing they need to do is send the dollars to the liquidity
provider so they can receive the euros back. Now, unless that dollar movement on fiat rails is instant, which it can be if it's local, but let's say it was cross let's say it was across timelines or time zones, that's probably going to be a T+1 settlement. So, actually, why don't I just do that via a stablecoin, which is basically one to one dollar, and then
I'm going to get my euro probably a day earlier than everyone else. So, what I've seen the shift more is instead of just doing a pure FX, one of the legs or one of the assets is becoming a stablecoin. So, instead of sterling versus dollar, it's sterling versus a USDC, or instead of euro versus dollar. We've also definitely seen a shift. Like, you know, at OpenPayd, we
are by no means a we wouldn't describe ourselves as a liquidity provider in the crypto space, right? Like there are we have a lot of clients who are you know, the likes of B2C2, the likes of Win Smooth. These guys are market-leading, world-famous liquidity providers. But we have a significant amount of client base doing volume with us. And the reason
we've what we're noticing is it's not the pricing per se that people are coming for. I think it's just the efficiency and the speed of settlement. Because if you think about what we do for our clients, we can receive USDT from our client into a wallet. We can instantaneously, and I mean sub-10 minutes, move that into dollars into their account, and then
about 5 minutes later, I can convert that FX into euro and put that into their account, and they can make a third-party payment. That whole process from the crypto coming in into dollars, then conversion into FX, takes us about 15 minutes. And I think that's what people now demand. It's that speed of movement, it's that speed of how quickly can I make that final payment out because
that's ultimately what I need to do. As long as I can do it in a cost-effective, but actually more and more importantly, in a timely manner. And that's the conversion we're seeing now. They people want that one-stop shop, that one provider. Definitely. I love that, and I think any business who gets into stablecoins or other digital assets, and they do
payments, and then, you know, one of their partners doesn't accept that, and they go back to fiat, and then people really realize how good they have it with stablecoins. It's just such a mess to deal with. You know, it's like, oh, it's going to be there next week or something. It's like, Yeah, and also so fast. Yeah, and also, like imagine if
actually you had a company yourself, and let's say your one provider could do the initial USDT into, let's say, USD, but then you wanted a an FX transaction for whatever reason, you would then need to do an added operational hop of taking those dollars, then sending it to your other provider, and then waiting for euros. So, from an operational point of
view, it's rubbish because you then have to literally go and do another payment out, which is open to manual error, and then you've got that lag time of getting the euros back. So, there's also that efficiency side, right? It's just people prefer, you know, it's that interoperability of so many systems talking to each other. Why can we not just have one provider
who can do all these different things for me in an efficient manner? Definitely. And from what I understand, you were an FX trader in this life. How
My sins, yes. How is your experience on that weighed into the FX side of globalized commerce here? Yeah, I mean for me when I joined OpenPayd, myself and a colleague came and we were we were both JP Morgan
and our career was was was started in FX. So, being in a at a payments firm as well, I think that having a good FX offering is an incredibly important thing to do and the reason for that is you know, these clients aren't trading FX with us to do speculation, which is what we used to do at JP Morgan. You know, we used to manage hedge funds, etc. It's really cross-border
settlement, right? Like you know, you've got a company that's based in Europe that needs to make a payout to a dollar client, a US client in dollar. So, want to do a FX at a at a good price. You know, when I when I log onto my HSBC app now, if I want to convert euro sterling to dollar, I get charged 1.75%, which is just it's mind-blowing for me. You know, whereas we can do that at
OpenPayd for about five basis points. So, you suddenly you're you're saving you're saving company on their you know, you're saving your clients on their bottom line and again, you're giving them that one-stop shop. So, no as a payments firm, look, I think the FX is going to continuously evolve. I think people more and more you know, a lot of our clients are international and
have the need to do cross-currency, cross-border payments and that's where FX comes into. I guess the shift we're seeing is what I mentioned earlier that one of those legs seems to be more and more replaced by a stable coin now. Yeah, it's a crazy shift that's happening. If you could wave a magic wand and remove one thing that's stopping, you know, the other 90% of companies
that are stuck in the past to move into something like OpenPayd, what's that barrier that we need to remove? I think if you if in terms of you're asking about moving into like stable coins and taking the plunge, for me if I could wave it, I would I would wave the wand and create a global coordinated regulatory policy for crypto. Like it's to me that would not
only get everyone into embedding stable coins into their operations and how they can be much more efficient across you, but also it would get all the institutional capital that is probably sitting on the sidelines waiting for the right moment to flood into the space and then we'd see the Bitcoin at 250,000, we'd see Ethereum at 10,000, which I would love personally.
So, for me that would be it. It would be a coordinated regulatory policy framework. That extends throughout the world. Yeah, no that makes complete sense. You know, the genius act is great for US companies, but then now that you have to do business with everybody else in the world, well we got to coordinate here. No, agreed. And like even even with MiCA
in Europe, you know, we've got MiCA and you know, it's being implements now, but then within Europe you've got Poland who still haven't decided on their frameworks. Even within Europe, even though we have MiCA, you still have member states who are still not sure on what they're doing and there's no frameworks there. So, it's it's still feels a bit too fragmented and yeah,
that would be the ultimate wish list or the dream for me. Definitely. Well, while we have that global stablecoin regulation, you know, being written up, what are you and the team at OpenPayd working on throughout 2026 that you guys are looking forward to growing? Yeah, I think for us we're going to double down on stablecoins and what it means to
us as a business and that just doesn't mean just you know, the crypto offering, but also what do the companies who are using stablecoins need? And for me that means that we want to be able to offer our clients more local rails. You know, so I'd love to be able to offer our clients, you know, local bank accounts in LATAM, you know, in Brazil, you know, Chile, Argentina, Mexico, etc.
And we want to do that globally. Like OpenPayd so incredibly well known in Europe and UK because that's where our head office is and that's where we offer local rails. All of those other currencies are via Swift and sort of you know, which is a little bit slower. So, for me it's for me and the company it's really to say, okay, how can we now go global dominance and for that we need to
have those local rails. So, you know, we come into the US and we have local rails fed via ACH. We go to look at Singapore, Hong Kong, we look at the Middle East, etc. But that's really what we need and the reason for that is because all a majority of financial institutions who have embedded stablecoins require that local rail access and that's where we
hope OpenPayd can can step in. Yeah, I think that's a great direction. The South America is huge and I know that they're they're all in on stablecoins, but get getting that interaction with fiat and those other local currencies, I think is important. So, would love to see that. You know, for all of the businesses, most of them that aren't yet tapped into
something like OpenPayd, what's the best way to get started quickly? As in sorry, and you mean by that as in getting into the like the stablecoin stuff? Yeah, [snorts] and Or to or to work with us? Well, to work with you guys, more importantly. Yeah, I mean to work with us, I mean look, we are I would definitely follow our company page on LinkedIn and
reached out there or you we have a lot of inbound through our website. So, our website is got all the materials on who we are and you can contact our commercial team by leaving your requirements and your details there. I'm also obviously on LinkedIn and I'm always happy to receive any kind of messages from people who A, just want to even learn more about us, let alone just
even working with us. But yeah, for me it would be LinkedIn, it would be the website or and directly to me. Those would be the three avenues. Sounds great, Lex. I appreciate your insights into payments and getting more businesses involved in stablecoins and I'm all for it. Of course, we know you and me both know that there's many benefits and the more businesses that
get involved, the better it's going to be for them speed, cost-wise and for the world. So, thank you for what you and the team are doing at OpenPayd and wishing you and the team all the best. Would would love to follow up again in the near future. No, again Ashton, thank you for the time today and appreciate that. Oh yeah, we'll keep building and absolutely look
forward to catching up with you again soon.
Related coverage
More interviews
 How Robinhood built its own blockchain to control compliance and feesSep 29, 2026
 Geo Protocol founder Yaniv Tal launches Geo Debates, its first productSep 28, 2026
 How Brave is expanding beyond ad blocking with Drew PotterSep 27, 2026
 Why Kevin Carter thinks China is winning the AI raceSep 25, 2026
 Brave's plan to bring self-custody payments to 120 million usersSep 18, 2026
 Arie Trouw on why AI agents now need proof of actionSep 14, 2026