
High insurance costs threaten EV boom as the sector pivots to smart tech
Rising insurance premiums and maintenance costs for electric vehicles threaten to undermine the EV adoption economics that institutional investors have modeled into their energy transition theses. As European households face 37% higher insurance costs since 2021 alongside critical gaps in charging infrastructure, the path to mass EV adoption now depends on resolving competing demands for grid capacity between vehicle charging and data center expansion.
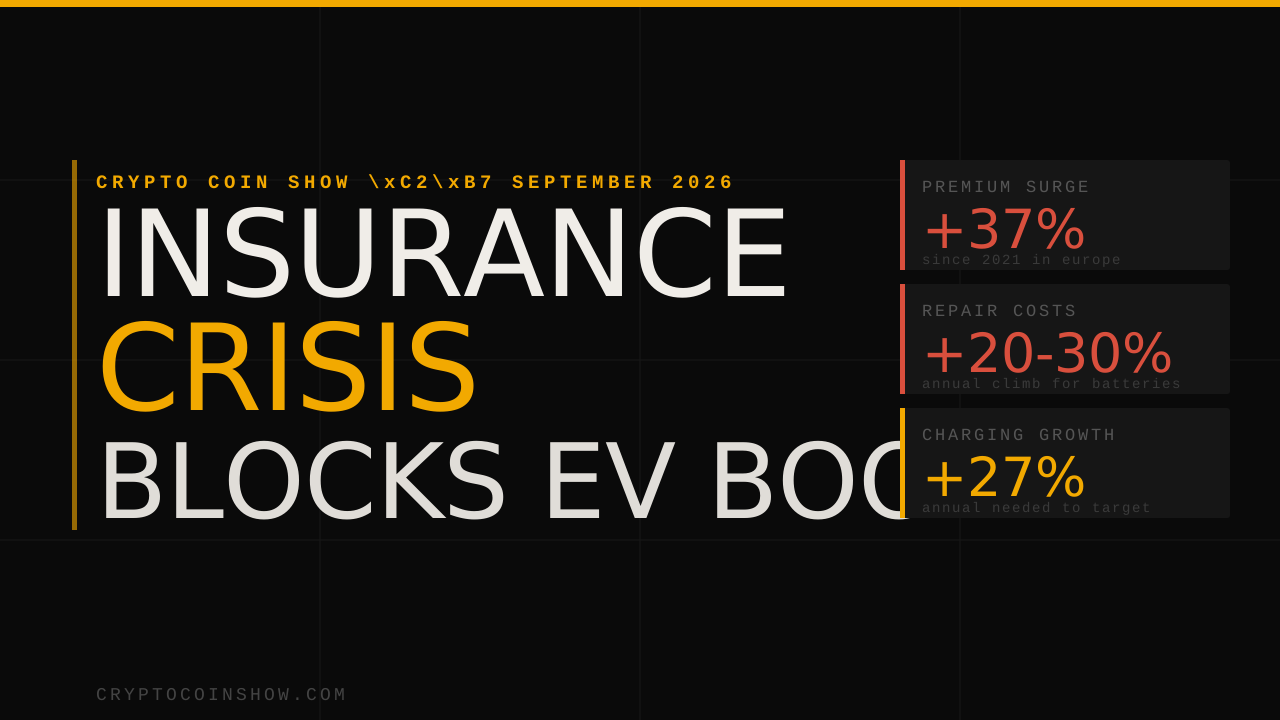
- Insurance premiums in Europe have risen 37% since 2021, while EV repair costs climb 20%-30% annually due to battery complexity.
- Europe reached only 1.1 million charging stations by early 2026, requiring 27% annual growth to meet the EU’s 3.5 million target by 2030.
- EU electricity demand from data centers will surge 65% by 2030, directly competing with EV charging for grid capacity as overall demand grows only 1.1%-1.5% yearly.
- 37% Rise in European insurance premiums since 2021 versus baseline.
- 1.1M Charging stations in Europe by early 2026 versus 3.5M target by 2030.
- 65% Projected increase in EU data center electricity demand through 2030.
Electric vehicle adoption across Europe faces an unexpected headwind: the total cost of ownership is narrowing as insurance and maintenance expenses rise faster than fuel savings accumulate.
While oil price spikes have historically driven consumer interest toward EVs, the actual economics of switching to battery power are becoming less attractive in real terms, particularly for middle and lower-income households where transport spending already consumes 7% to 11% of annual budgets.
Insurance premiums have jumped 37% since 2021, while repair and maintenance costs have climbed 20% to 30% annually, driven by the complexity of EV powertrains and the high cost of battery replacement and servicing.
This erosion of the EV value proposition matters to institutional investors because it signals potential demand ceiling effects in markets that lack sufficient alternative incentives, such as regulatory mandates or price caps on insurance, to sustain the volume growth needed to justify the capital expenditure cycle that manufacturers and utilities have already committed to.
Insurance costs and repair complexity offset fuel economy savings in emerging EV markets
The financial advantage of switching from internal combustion to electric power is narrowing in ways that standard cost-of-ownership analyses may not fully capture.
James Kan, who leads industrial research for Asia Pacific at BNP Paribas, has identified a critical blind spot in EV adoption modeling: the assumption that lower fuel consumption will translate into proportional savings for household budgets.
Instead, in many emerging markets, the gains from eliminating petrol expenses are being erased by sharply higher insurance premiums and the escalating cost of maintaining vehicles with sophisticated battery management systems and electronic components.
In France and Germany, where automotive spending already represents 7% to 8% of total household expenditure, the margin for additional cost absorption is minimal; for the poorest households in these countries, transport costs already consume 11% of annual spending, leaving little room for higher insurance bills.
The problem is compounded by the fact that repair costs in the EU are rising much faster than household incomes, creating a structural affordability squeeze that will constrain EV adoption regardless of fuel prices. Mechanics require specialized training to service EV batteries and power electronics, and parts availability remains limited outside major markets.
Battery replacement alone can cost between 5,000 and 15,000 euros depending on vehicle size and chemistry, creating a discrete financial shock for owners outside warranty periods.
This dynamic suggests that EV adoption will remain concentrated in wealthier regions and demographics unless governments intervene with insurance subsidies, warranty extensions, or standardized battery-swap programs that lower perceived lifetime ownership costs.
Europe’s charging network falls 0.8 million stations short of 2030 targets amid uneven geographic distribution
Infrastructure readiness remains the second major constraint on EV acceleration, and the gap is widening rather than closing. Europe has added charging stations at roughly 20% annual growth since 2020, reaching 1.1 million by early 2026.
The EU’s official target of 3.5 million stations by 2030 requires 27% annual growth from this point forward, a step-function increase that would require both capital investment and grid capacity that does not yet exist.
At current rates, Europe will fall approximately 0.8 million stations short of its mandate, creating a persistent bottleneck in secondary cities and rural areas where charging accessibility directly determines EV feasibility for commuters without home garages.
The geographic concentration of existing infrastructure exacerbates this shortfall. The Netherlands, France, Germany, and Belgium account for roughly 65% of all EU charging stations, while Eastern European nations, southern Spain, and rural France remain severely underserved.
Equally problematic, only 16% of Europe’s installed chargers are ultra-fast DC units capable of delivering 150 kW or higher output; France and Germany concentrate 40% of these premium chargers, leaving the rest of the continent dependent on slow Level 2 chargers that require four to eight hours for a full charge.
For institutional investors in utilities, grid operators, and EV charging network operators, this creates a two-tier market dynamic where returns concentrate in wealthy, densely populated corridors while the addressable market in less developed regions shrinks due to infrastructure poverty.
Kan emphasized that “the infrastructure readiness is not necessarily there” in many countries, pointing to the United States and developing nations as examples where weak power grid capacity is forcing consumers toward hybrid vehicles rather than full electrification.
This reveals a critical constraint that EV adoption models often underestimate: grid bottlenecks act as hard ceilings on EV adoption rates independent of consumer demand or vehicle cost. Without simultaneous investment in distribution-level grid upgrades, transformer capacity, and demand management systems, the charging infrastructure gap will persist even if station density improves.
Data center electricity demand will consume grid capacity allocated to EV charging by 2030
A more acute constraint is emerging on the supply side: the EU electricity grid faces competing demands from both EV charging infrastructure and data center expansion that cannot be simultaneously accommodated within current capacity growth trajectories.
The International Energy Agency projects that EU data center electricity consumption will rise from 70 TWh in 2024 to 115 TWh by 2030, a 65% increase driven by artificial intelligence workload concentration and cloud service expansion.
This surge directly competes with planned EV charging networks for grid capacity at precisely the moment when overall EU electricity demand growth is only 1.1% to 1.5% annually. The math is unforgiving: data centers alone are absorbing more than double the average annual electricity growth rate, leaving minimal headroom for the incremental demand from mass EV adoption.
The implication for institutional investors is stark: either renewable generation capacity must expand faster than any current trajectory suggests, or grid operators will be forced to make explicit prioritization choices between EV charging and data center infrastructure.
In most EU member states, data centers represent higher-margin, lower-political-cost loads because they generate immediate tax revenue and employment. This suggests that in infrastructure-constrained regions, EV charging will lose priority access to new grid capacity, creating persistent supply-side constraints on EV adoption even if vehicle costs, insurance, and repair economics improve.
National grid operators are already signaling this risk through energy rationing frameworks and dynamic pricing models that front-load costs to off-peak charging, effectively raising the cost of EV ownership for drivers who lack access to cheap overnight rates.
Oil price volatility and EU Net Zero policy create divergent scenarios for fuel costs and EV demand
Near-term EV adoption rates remain tethered to oil price dynamics, but long-term demand depends on policy-driven fuel cost escalation that may ultimately price fossil fuel vehicles out of reach for most households. A 30% rise in Brent crude has already pushed fuel prices in France, Germany, and the Netherlands above 2.0 euros per liter, a level not seen since the Russia-Ukraine conflict. In Germany, where fuel price sensitivity is historically high, elevated petrol costs have repeatedly triggered reductions in overall car sales, suggesting a ceiling beyond which consumers defer vehicle purchases entirely rather than switching to EVs. Current EU Net Zero policy frameworks suggest fuel prices could reach 2.10 to 2.55 euros per liter by the early 2030s under baseline scenarios, or as high as 5.60 euros per liter under tougher climate standards with oil exceeding 190 dollars per barrel