Tesla delivers 480,000 vehicles in Q2 but BYD keeps the global EV crown
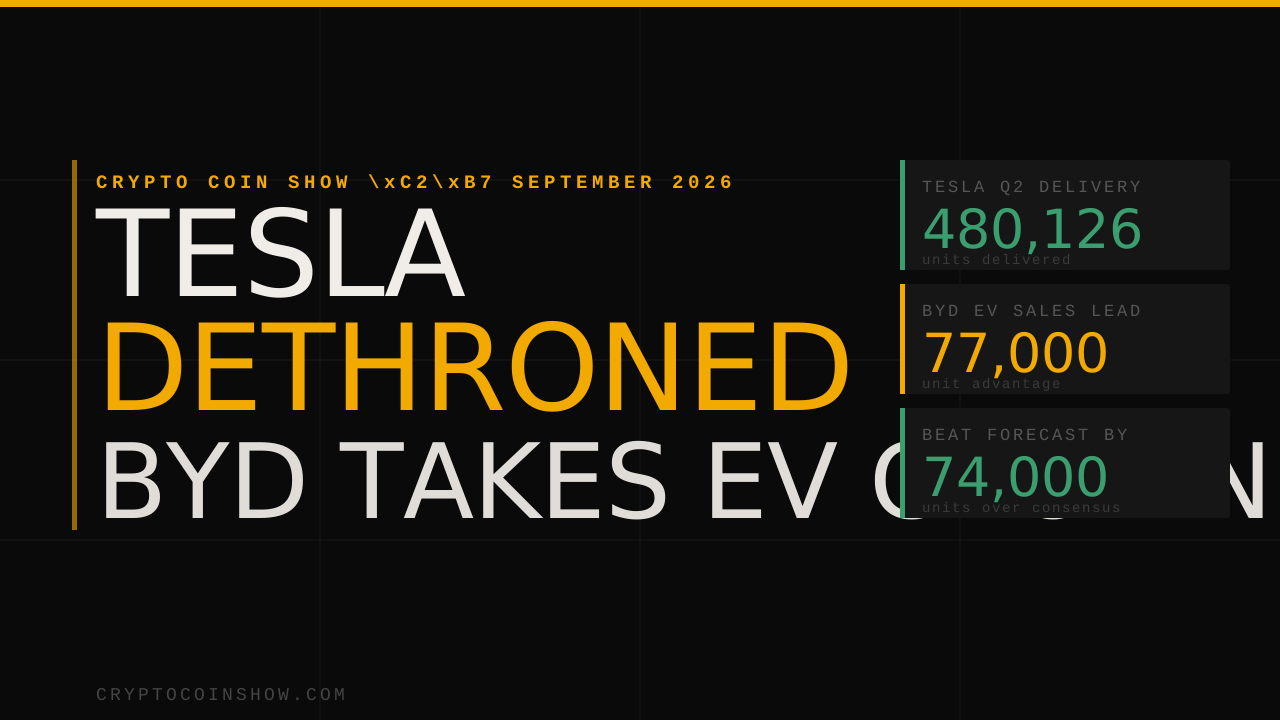
Tesla delivered 480,126 vehicles in Q2 2026, beating Wall Street forecasts by 74,000 units and marking a 25% year-over-year surge, yet Chinese rival BYD retained the global EV sales crown with 557,090 deliveries, widening the gap to 77,000 units. For institutional investors, the divergence signals that scale and cost leadership in emerging markets now matter more than execution surprises in a single quarter, reshaping how to value legacy automakers versus vertically integrated Chinese competitors.
- Tesla delivered 480,126 vehicles in Q2 2026, surpassing Wall Street consensus of 406,000 by 74,000 units.
- BYD sold 557,090 fully electric vehicles in Q2, outselling Tesla by 77,000 units and retaining global EV sales leadership.
- Tesla’s U.S. sales fell 20% following federal EV tax credit expiration, while European registrations surged 152% within the EU.
- 480,126 Tesla Q2 2026 deliveries versus 406,000 Wall Street consensus forecast
- 557,090 BYD Q2 2026 fully electric vehicle sales versus Tesla’s quarterly volume
- 152% Tesla EU vehicle registration growth in May versus same month prior year
Tesla’s second-quarter delivery report arrived with the trappings of success: a 74,000-unit beat against analyst expectations, a 25% increase versus Q2 2025, and the second-largest quarterly volume in the company’s history at 480,126 vehicles. Yet the stock market response told a different story.
Tesla shares closed down nearly 8% on July 2, 2026, the day the earnings comparisons became clear, signaling that institutional capital has begun to discount the significance of unit growth divorced from market share and profitability momentum.
The real news lay not in whether Tesla exceeded consensus, but in what that consensus had already priced in: a mature company in a market where Chinese manufacturers now set the pace.
Tesla’s Model 3 and Model Y account for 97% of quarterly deliveries as mass-market focus deepens
The composition of Tesla’s sales reflects a strategic narrowing. Model 3 and Model Y vehicles made up 467,762 of the 480,126 total deliveries, leaving only 12,364 units for Cybertruck, Model S, and Model X combined.
That 97% concentration on two platforms underscores Tesla’s dependence on high-volume, lower-margin segments to drive headline growth, even as premium and specialty products, historically sources of higher profit per unit, remain marginal to the overall mix.
The quarter also revealed production-delivery timing: Tesla manufactured 451,758 vehicles but shipped 480,126, meaning approximately 28,368 units came from inventory accumulated in prior periods. This gap suggests demand remained soft enough that the company needed to draw down stock to meet delivery targets, a dynamic at odds with the public narrative of demand-constrained supply.
Sequentially, the acceleration was notable. Q1 2026 saw 358,023 deliveries; Q2 represented a 34% jump in just three months. Yet only three quarters in Tesla’s operating history exceeded Q2’s result: Q3 2025 (497,099 vehicles), Q4 2024 (495,570), and Q4 2023 (484,507).
The company has not grown beyond its own historical ceiling, suggesting maturation in core markets rather than new-market expansion driving the headline beat.
U.S. sales collapse 20% as federal EV tax credit expires, forcing Tesla to chase international growth
The real vulnerability in Tesla’s numbers appeared in the U.S. domestic market, where sales fell 20% after the federal EV tax credit expired, according to Cox Automotive data. The loss of this subsidy directly increased the effective price of Tesla vehicles for many American consumers, a structural headwind that beats to quarterly consensus cannot overcome.
The company has no control over U.S. tax policy, yet must navigate its consequences in the world’s second-largest EV market.
Tesla’s response was geographic pivot: Europe became the growth engine. Tesla registrations across Europe hit 28,610 units in May 2026, a 108% increase year-over-year. Within the European Union specifically, May registrations more than doubled, climbing 152% versus May 2025.
Year-to-date registrations through May reached 118,068 vehicles, a 57% increase. Deutsche Bank analyst Edison Yu attributed this surge to aggressive competitive pricing by Tesla, coupled with expansion in China, rather than to any new product or technology breakthrough.
The pricing strategy carried a reputational cost: some European buyers chose Tesla vehicles despite disagreement with CEO Elon Musk’s political views, prioritizing the cost advantage over personal alignment. This dynamic reveals the fungible nature of demand in mature EV markets, where price and availability matter more than brand loyalty or founder persona.
BYD’s 557,090 Q2 sales and 43% overseas revenue mix signals Chinese EV leadership now extends beyond domestic market
BYD delivered 557,090 fully electric vehicles in Q2 2026, maintaining a 77,000-unit lead over Tesla and cementing its position as the global EV sales leader.
The Chinese manufacturer announced results one day before Tesla, setting the benchmark against which Wall Street subsequently measured Tesla’s “beat.” That sequencing mattered: institutional investors already knew the global sales leader had sold more, making Tesla’s 74,000-unit beat against consensus feel incremental rather than impressive.
BYD’s quarterly volume did decline 8% year-over-year from a higher prior-year peak, suggesting the company faces its own demand moderation in China’s saturated domestic market. However, BYD disclosed that 43% of Q2 sales originated outside China, indicating successful geographic diversification into Southeast Asia, Europe, and other emerging markets.
Tesla, by contrast, remains structurally dependent on the U.S. and Europe for the majority of its volume, with limited penetration in price-sensitive markets where BYD has built manufacturing footprint and supply-chain advantage.
The market responded accordingly. BYD’s stock closed up 3.61% on July 2, 2026, on its Shenzhen listing at 83.57 Chinese Yuan, while Hong Kong-listed shares closed at 78.30 Hong Kong dollars. The positive reaction reflected investor confidence in BYD’s scale and international expansion trajectory.
Tesla’s 8% stock decline the same day signaled market concern that unit growth no longer translates to valuation support when the company trails the global leader and faces structural headwinds in its largest market.
Tesla energy storage deployment misses analyst expectations as battery supply tightens across industry
Beyond vehicle deliveries, Tesla’s energy storage business provides a secondary gauge of manufacturing momentum and supply-chain health. In Q2 2026, Tesla deployed 13.5 gigawatt-hours (GWh) of energy storage, representing a 53% increase from 8.8 GWh in Q1.
This sequential jump appeared strong until placed against analyst expectations of 13.8 GWh, revealing that storage growth, while accelerating, remains supply-constrained rather than demand-constrained.
The miss on storage guidance, combined with inventory drawdown in vehicle sales, suggests battery production capacity remains the limiting factor for Tesla’s overall growth, not market demand or pricing power.
Stock market divergence between BYD and Tesla signals institutional reassessment of competitive positioning in global EV markets
The intraday stock performance on July 2, 2026, crystallized the institutional view of the two companies’ trajectories. BYD’s price appreciation despite flat-to-negative year-over-year volume reflected investor confidence in its cost structure, geographic diversity, and position in the world’s largest EV market.
Tesla’s 8% decline despite a beat against consensus reflected growing concern that the company has become a mature, volume-focused manufacturer competing in a price-driven market dominated by Chinese competitors with lower cost of capital and manufacturing expense.
For institutional investors, the implication is straightforward: Tesla’s ability to exceed quarterly consensus matters less than its ability to