Short interest in SpaceX jumps to 13% from 8% in one session
SpaceX short interest has surged to 13% from 8% in a single trading session, signaling institutional bearish positioning following the stock’s 30% decline from its post-IPO peak. For institutional investors, this rapid shift in leverage metrics and borrowing availability suggests both heightened volatility ahead and a divergence in positioning from other mega-cap technology stocks.
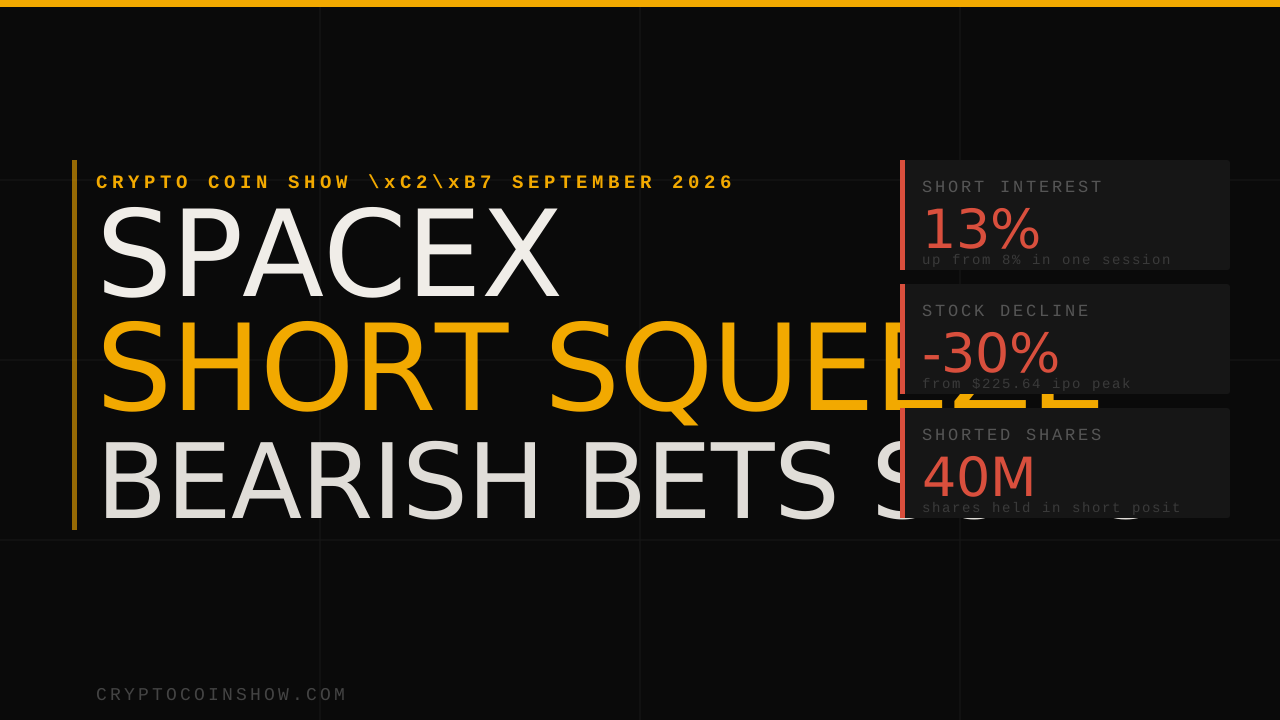
- Short interest jumped from 8% to 13% in one session, the steepest single-day increase among major tech stocks
- Approximately 40 million SpaceX shares are now held in short positions, representing 5-7% of publicly tradable shares
- Stock has fallen nearly 30% from its $225.64 peak reached shortly after the June 12 IPO debut
- 13% Current short interest as percentage of float, up from 8% prior session
- $600B Market value lost over three trading days since IPO peak
- 0.60% Annual borrowing rate for shares, versus 0.30% for easiest-to-borrow stocks
SpaceX shares have become the focal point of a sharp reversal in market sentiment following the aerospace manufacturer’s public listing on June 12. Within days of opening, the stock reached $225.64, but has since contracted to a market capitalization below $2 trillion for the first time as a public company, erasing roughly $600 billion in value over just three trading sessions.
The selloff coincides with a broader market decline that saw the Nasdaq 100 lose more than $1 trillion in a single session as investors fled technology and semiconductor holdings. Against this backdrop, short sellers have moved aggressively into SpaceX positions at a pace that exceeds the typical defensive repositioning seen in other mega-cap tech names.
Short Interest Doubles as Bears Seize SpaceX’s Post-IPO Tumble
Data from Ortex Technologies, a real-time financial analytics firm, documents the acceleration of bearish positioning with precision. Short interest climbed from 8% of the float in the prior trading session to 13% in the current one, a jump that stands out even within the context of a market-wide technology selloff.
By comparison, the Magnificent Seven, Apple, Microsoft, Nvidia, Alphabet, Amazon, Meta, and Tesla, carry short interest levels of only 1% to 3% of their respective free floats, indicating that SpaceX’s leverage concentration among bears is now substantially higher than peer-group norms.
S3 Partners, another major provider of short-selling analytics, estimates that roughly 40 million SpaceX shares are currently held in short positions. That figure represents between 5% and 7% of the company’s publicly tradable shares, though Ortex’s higher short interest reading of 13% suggests methodological differences in how each firm calculates the measure.
Regardless of the precise number, the trajectory is unambiguous: traders are rapidly increasing their bearish exposure.
A jump like this is a clear sign that a growing number of traders are positioning for the price to fall sharply.
Peter Hillerberg, co-founder, Ortex Technologies
Falling Borrow Costs Signal Abundant Share Supply for Short Sales
The speed of short accumulation reflects a technical shift in the mechanics of the short market: borrowing shares has become both easier and cheaper. According to S3 Partners, short sellers are currently paying approximately 0.60% annually to borrow SpaceX shares.
While this rate exceeds the 0.30% charged for the easiest-to-borrow stocks in the market, it remains low enough to signal ample supply and minimal friction in locating shares to short.
Ortex data confirms the abundance of lendable shares, showing that the cost of borrowing stands at roughly 1% and that utilization, the percentage of available stock currently on loan, sits at approximately 39%, up from the mid-30s the week prior. Even at the open of the trading session in question, borrowing costs briefly reached 14%, yet this spike did not substantially deter new short entries.
For institutional short sellers, these low barriers to entry explain the aggressive positioning: there is no scarcity premium constraining their ability to build positions.
This dynamic stands in sharp contrast to mega-cap peers, where borrowing costs of 0.25% to 0.33% reflect tighter supply and less acute bearish crowding.
Options Market Echoes Bearish Bias Among Derivatives Traders
The directional bias visible in the equity short market extends to the derivatives complex. Options traders have begun positioning defensively in response to the same downward price momentum that has drawn equity short sellers.
The confluence of elevated puts, short equity positions, and falling borrowing costs creates a multi-layered bearish structure that did not exist at the IPO opening price of $225.64.
For institutional investors tracking hedge fund and algorithmic positioning, this options-and-equity alignment carries specific implications.
When derivatives traders and short sellers converge on the same directional view, it typically signals either capitulation (a one-time repricing) or the formation of a liquidity trap, where any rebound may be met by rapid short covering but any further decline could accelerate.
SpaceX’s high short interest relative to the Magnificent Seven suggests the market is treating it as a distinct risk asset, not as a defensive mega-cap play.
The derivatives market is currently pricing in continued downside exposure, mirroring the equity short positioning data.
SpaceX Short Positioning Diverges From Magnificent Seven Peer Dynamics
The 13% short interest in SpaceX contrasts sharply with positioning in Apple, Microsoft, Nvidia, Alphabet, Amazon, Meta, and Tesla, each of which trades with only 1% to 3% of float held short.
Borrowing costs for those names remain compressed at 0.25% to 0.33%, indicating that short sellers see less opportunity or less conviction in betting against them even amid the broader technology sector decline.
SpaceX’s higher leverage ratio and elevated borrow costs suggest that market participants are treating the newly public aerospace manufacturer as a higher-risk, higher-reward short than the established mega-cap technology cohort.
This positioning divergence raises a key question for institutional allocators: whether SpaceX’s post-IPO volatility reflects valuation normalization following an inflated opening or signals genuine skepticism about the company’s medium-term trajectory.
The fact that short sellers are paying more to borrow shares and accumulating positions faster than in peer stocks implies they view SpaceX as a near-term momentum reversal play rather than a long-term short thesis.
The lack of sustained supply constraints, utilization remains below 40% rather than spiking toward 100%, suggests shorts expect to exit positions profitably within weeks or months rather than locking in multi-year hedges.
Institutional investors should monitor whether the 13% short interest level stabilizes or continues to climb. If it approaches 20% or higher, it may signal a structural shift in how the market values SpaceX relative to other post-IPO technology names.
Conversely, if utilization tightens sharply or borrow costs spike above 5%, it could indicate that supply constraints are forming and that near-term short covering may drive a sharp rebound, even absent positive fundamental news.
The next critical inflection point arrives if SpaceX shorts breach 15-20% of float or if borrow costs spike above 2-3%; either event would signal either capitulation of bearish crowding or the emergence of structural supply constraints that could trigger short-covering rallies. Watch for weekly Ortex and S3 updates, and track changes in utilization and borrow rates as the primary forward indicators of whether short interest remains a medium-term headwind or reverses into a catalyst for upside momentum.
Original reporting: cryptopolitan.com