SEC Treasury clearing rule drives 165% jump in daily volumes before compliance deadlines
The Securities and Exchange Commission is requiring Treasury trades through clearing agencies starting December 31, reshaping how stablecoin issuers access dollar liquidity behind their tokens. The change could make reserve management cheaper or harder depending on whether dealers pass savings to smaller clients or restrict access to those offering the best terms.
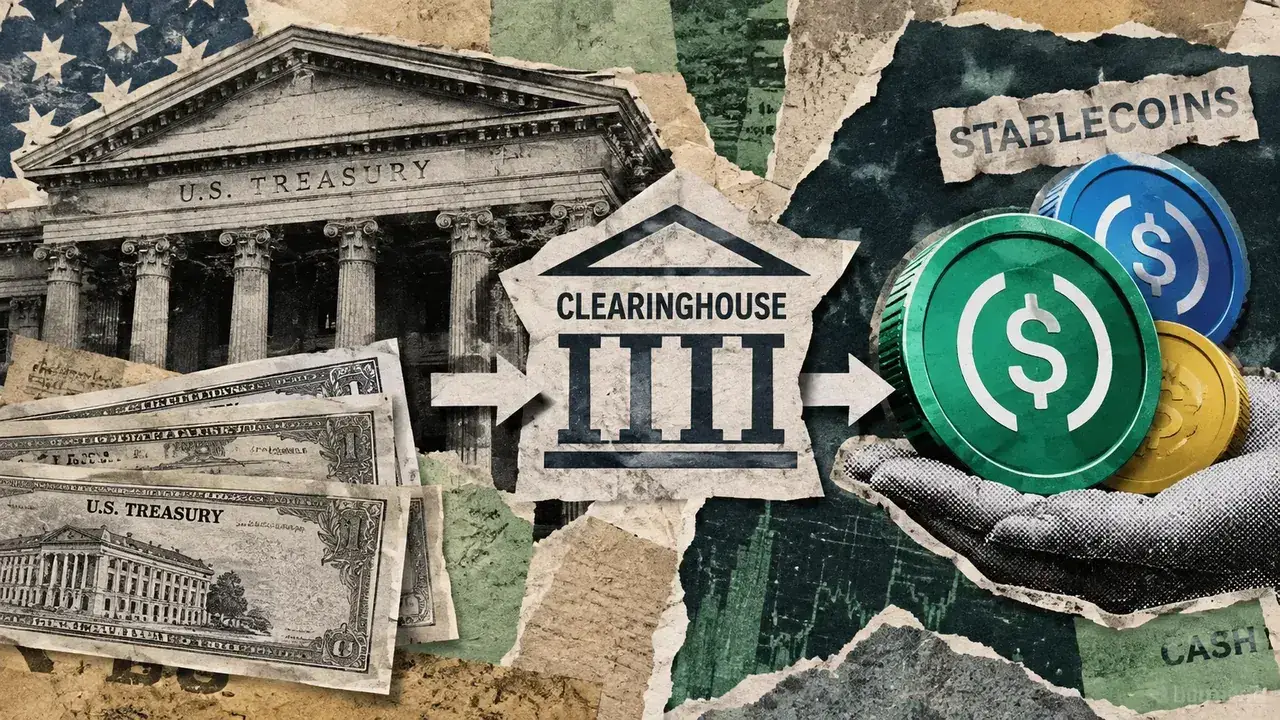
- Repos involving Treasuries, sales with agreements to repurchase, moved from less than half of the market centrally cleared to mandatory clearing by June 30, 2027.
- Only about one-third of dealers surveyed by FICC expect to offer Treasury cash clearing to clients, raising questions about access for smaller stablecoin issuers.
- $3T Daily SOFR transaction volumes, up from roughly $1 trillion in early 2022
- 33% Proportion of FICC members expected to offer Treasury clearing to clients
The SEC is mandating central clearing for Treasury trades involving clearing members, effective December 31 for outright sales and purchases and June 30, 2027, for repurchase agreements, according to remarks by Commissioner Mark Uyeda. The overhaul addresses a fragmented market in which fewer than half of Treasury repo transactions moved through a central clearinghouse before the rule. That gap meant dealers managed risk bilaterally with individual counterparties rather than through a single entity that guarantees completion of trades and holds collateral to cover losses if a member defaults.
Stablecoin issuers depend on these Treasury markets to convert their reserve assets into dollars when customers request redemptions. The issuer must be able to sell or finance its holdings quickly to pay out cash.
The cost and availability of that liquidity flow directly into the issuer’s reserve management, affecting whether redemptions run smoothly and whether the issuer can maintain the yields needed to back its tokens economically.
Clearing Requirements Expand Access but Create New Collateral Burdens
Central clearing reduces some of the operational friction dealers face by allowing netting, the ability to combine offsetting obligations so dealers post less collateral. According to the New York Fed’s framework, overnight repo volumes feeding the Secured Overnight Financing Rate reached $3 trillion, up from roughly $1 trillion in early 2022. Dealers act as intermediaries connecting money-market funds and hedge funds, absorbing capital constraints that limit how many customers each can serve simultaneously. When a dealer’s capital reaches regulatory limits, it cannot take on additional business no matter how much cash exists elsewhere in the market.
The SEC has approved enhanced margin-efficiency tools including collateral-in-lieu arrangements at the Fixed Income Clearing Corporation (FICC), which allow eligible cash lenders to avoid posting initial margin if they use Treasury collateral from the transaction instead.
These changes expanded the number of participants who can access central clearing, buy-side institutions, smaller broker-dealers, and principal trading firms that previously had no practical way to participate.
But the machinery requires participants to post margin, meaning cash or eligible securities held as protection against default.
Dealer Reluctance to Serve Small Clients Could Concentrate Access
The constraint is not technical but economic. A July survey by FICC of its member firms found that 79% had the necessary account setups to participate in centrally cleared Treasury trading, yet only about one-third expected to actually offer that clearing service to their clients.
That gap between capability and willingness signals that dealers see the operational burden or capital cost as outweighing the benefit, particularly for smaller counterparties generating less revenue.
For stablecoin issuers, this creates a two-tier market. Large issuers with substantial daily Treasury activity may negotiate favorable clearing terms with multiple dealers and gain access to netting benefits that lower their borrowing costs.
Smaller issuers or those with irregular redemption patterns may face fewer provider options, higher fees, or restrictions on how much they can finance or sell.
The SEC’s approval of two additional clearing agencies, CME Securities Clearing and ICE Clear Credit, was intended to create choice, but market forces determine whether those alternatives offer better economics for all participants or primarily serve institutions with specific business models.
Stablecoin Reserve Management Faces New Constraints on Timing
Treasury-backed stablecoins hold short-term government securities because they earn income and are easy to resell. When a customer requests redemption during business hours on a trading day, the issuer can sell or repo those securities to obtain dollars.
The new clearing requirements operate within normal market hours and settlement cycles; central clearing does not extend Treasury market operations to weekends or make intraday transactions instant.
An issuer receiving a redemption request on Sunday or after 5 p.m. ET must rely on its own cash reserves or pre-arranged credit lines to pay dollars immediately.
If access to Treasury financing becomes more expensive or restricted, issuers have two main levers: hold larger cash balances earning lower returns, or rely more heavily on selling or financing securities during market hours. Each choice involves trade-offs. Greater cash holdings reduce the issuer’s ability to earn yield across its entire reserve portfolio.
Heavier reliance on market-based financing makes the issuer more dependent on dealer access and more vulnerable to disruptions in clearing or dealer capacity. The SEC’s rule does not change the underlying operating hours of banks and securities dealers; it only changes how their risk is managed when they trade among themselves.
The CCS read. We see a bifurcation risk for stablecoin holders. Larger Treasury-backed issuers with institutional-grade funding relationships and frequent Treasury activity will likely negotiate tighter clearing terms and see reserve costs stabilize or decline. Smaller issuers or those with episodic demand face potential margin and access pressures that could widen their redemption spreads or force higher cash holdings, ultimately weakening their competitive position without the issuer cutting token supply or raising new equity.
The December 31 deadline for outright Treasury purchases and sales is the first enforcement point; the SEC has said it does not currently intend to extend either deadline. Watch whether dealers begin formally notifying smaller clients of new clearing fees or volume restrictions in the weeks before December, and monitor whether any of the three clearing agencies alter margin terms or eligibility criteria in response to dealer feedback about implementation costs.
Original reporting: cryptoslate.com