
Tesla plans to hire 1,000 workers at Berlin factory as European demand rebounds
Tesla’s plan to add 1,000 workers at its Berlin factory and raise weekly output to 7,500 vehicles signals a structural shift in EV demand toward Europe, even as US market headwinds persist. For institutional investors tracking exposure to European economic recovery and automotive sector capex cycles, the move underscores a durable reallocation of manufacturing capacity away from saturated North American markets.
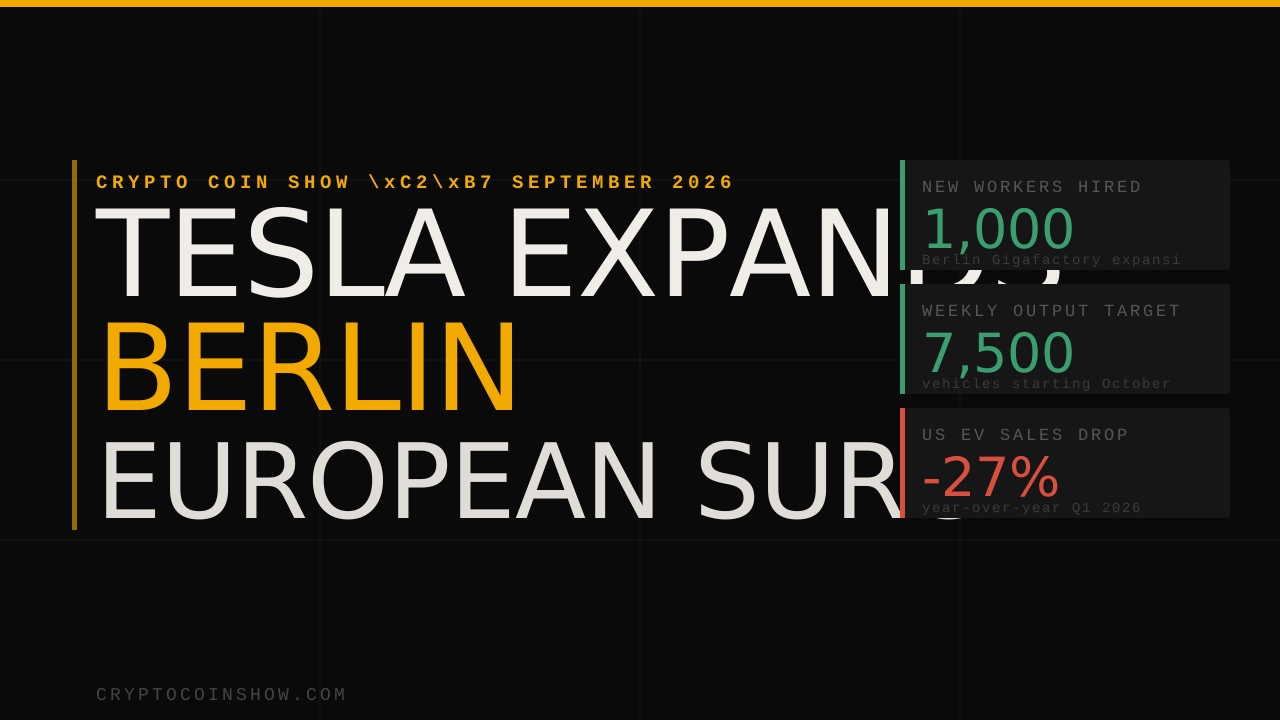
- Tesla will hire 1,000 workers at Berlin Gigafactory to support 20% weekly production increase to 7,500 vehicles starting October
- European EV market share surged to 2.3% for Tesla in May from 0.9% year prior, with Germany Model Y registrations up 4x
- US EV sales dropped 27% year-over-year in Q1 2026 following expiration of $7,500 federal tax credit in Q3 2025
- 1,000 Additional workers planned at Berlin facility within current hiring cycle
- 20% Weekly production increase targeted for Gruenheide plant starting October
- 27% Year-over-year decline in US EV sales during Q1 2026
Tesla announced plans to hire 1,000 additional workers at its Gigafactory Berlin to support a 20 percent increase in weekly production capacity, ramping output to 7,500 vehicles monthly starting in October.
The expansion represents the third consecutive workforce commitment at the Gruenheide facility east of the German capital within three months, following an earlier April disclosure of 1,000 new hires and a May announcement of incremental battery cell manufacturing investment. Combined, the three tranches will create 3,500 jobs across vehicle assembly and battery production at the site.
The timing reflects a sharp reversal in European demand dynamics after a weak 2025, when the Berlin plant delivered just over 200,000 vehicles against an annual design capacity of 375,000 units, a utilization rate well below nameplate.
European EV registrations surge as Tesla market share quadruples in Germany
Tesla’s European footprint strengthened materially in the first half of 2026, with particular momentum in its largest regional market. Model Y registrations in Germany reached 9,252 units in March, a four-fold year-over-year increase, while France, Denmark, and Sweden each posted registration gains exceeding 46 percent.
Across the European bloc in May, Tesla moved 21,767 vehicles, lifting its aggregate market share to 2.3 percent from 0.9 percent twelve months prior, a 156 percent relative gain in a single year.
The acceleration reflects both structural tailwinds in the EV adoption cycle and near-term supply dynamics. Battery-electric cars accounted for one-fifth of all new European Union passenger registrations in May 2026, up from 15.3 percent in the same month of 2025.
Within that expanding category, Tesla’s share of registrations grew faster than the segment itself, indicating competitive gains beyond simple category growth. The spike in German demand follows a period of regulatory uncertainty and local political friction surrounding the factory, signaling that production reliability and pricing have overcome prior skepticism among European buyers.
Industry data from Cox Automotive’s Kelley Blue Book confirms the regional divergence is real and durable. US EV sales fell 27 percent year-over-year in the first quarter of 2026 to approximately 216,400 units, driven primarily by the expiration of the $7,500 federal tax credit in Q3 2025.
Demand has not yet rebounded despite the policy withdrawal, suggesting the credit was masking latent price sensitivity rather than driving genuine category expansion.
US EV market contraction forces Tesla to reallocate manufacturing focus eastward
The divergence in regional demand is forcing a strategic reallocation of Tesla’s production footprint. Tesla’s domestic US deliveries dropped more than 8 percent in Q1 2026, though the company gained overall market share as competitors contracted faster.
The erosion of the $7,500 tax incentive removed a material demand catalyst for price-sensitive buyer cohorts, leaving the company to compete primarily on product merit and brand rather than on subsidy-driven affordability.
Against that backdrop, the Berlin expansion signals management confidence that European demand will sustain near-term. The Gruenheide facility currently employs approximately 11,500 workers. Adding 1,000 workers represents a 9 percent headcount increase, supporting both the immediate production ramp and preparations for battery cell manufacturing.
Tesla disclosed that a dedicated battery cell production line will begin operations at the site in the first half of 2027, requiring additional staffing now to train and onboard labor ahead of that launch.
The timing of hiring in advance of the battery line commissioning is strategically necessary. Battery production requires specialized training and capital equipment setup that cannot be accelerated late; Tesla’s decision to commit headcount now signals management expects sustained European demand to justify both the capex and the fixed labor costs.
This contrasts sharply with the cautious posture in North America, where Tesla is managing headcount and capex more conservatively.
Battery cell production launch in 2027 accelerates Tesla’s European vertical integration
The in-house battery cell line scheduled for the first half of 2027 represents a step change in Tesla’s European manufacturing strategy. Previously, the Berlin facility relied on sourced battery cells from external suppliers, constraining production flexibility and margin defensibility.
Vertical integration into battery production at Gruenheide will allow Tesla to reduce input cost volatility and respond more dynamically to European demand swings without relying on external supply agreements.
For institutional investors, the battery line commissioning is a critical inflection point. It will increase the plant’s fixed cost base significantly and tie additional labor and capex to European market success.
The 1,000 workers being hired now will staff both the assembly ramp through October and form the initial cohort for battery manufacturing operations in the second half of 2026 and into 2027.
This compressed timeline means Tesla is essentially betting that the European demand surge is durable enough to justify concurrent expansion of two production lines with different cost structures and labor profiles.
The next material data point will be Tesla’s third-quarter 2026 delivery and production figures, due in early October, which will reveal whether the Berlin facility actually achieves the targeted 7,500 weekly vehicle output and whether European market share continues its upward trajectory.
Simultaneously, investors should monitor quarterly European EV registration data for any evidence of demand normalization or competitive pressure, particularly from Chinese EV makers entering European markets. Tesla management has committed to battery line commissioning in H1 2027; any delay or revision to that timeline would signal underlying confidence in demand has shifted.
Berlin Ramp Coincides With Structural Shift in EV Subsidy Regimes Across EU
The timing of Tesla’s Berlin expansion aligns with a broader recalibration of European EV incentive structures, which have pivoted toward domestic manufacturing credits rather than point-of-sale rebates.
Germany’s KfW bank, which administered subsidies for battery-electric vehicle purchases, shifted its support model in Q2 2026 to prioritize vehicles assembled within EU borders, effectively redirecting subsidy capture toward Tesla’s Gruenheide plant and away from imported Chinese EV makers.
This regulatory shift has no direct US parallel following the expiration of the federal $7,500 tax credit, creating a policy-driven tailwind for European localized production that institutional investors have begun pricing into automotive supply chain positioning.
The subsidy reorientation reflects deeper protectionist currents within the EU’s industrial policy. Brussels has raised tariffs on imported Chinese EVs to 38.1 percent as of July 2026, compared to zero tariffs on intra-EU shipments, fundamentally altering the competitive equation for foreign-assembled vehicles sold in European markets.
For Tesla, which operates the only foreign-owned high-volume EV plant in the bloc, the regulatory environment now favors local production over imports from Shanghai or Austin, even accounting for higher German labor costs. This contrasts sharply with 2024-2025, when Tesla’s Berlin plant operated well below capacity partly because vehicles imported from China and the US faced no tariff penalty.
EU member states will finalize their own national subsidy frameworks by Q4 2026, and early indications suggest France and Italy will adopt similar domestic-production preference models. Institutional investors tracking automotive sector rebalancing should monitor whether this subsidy architecture proves durable through the next European Parliament term, given the political sensitivity of US automaker treatment under proposed carbon border adjustment mechanisms.