
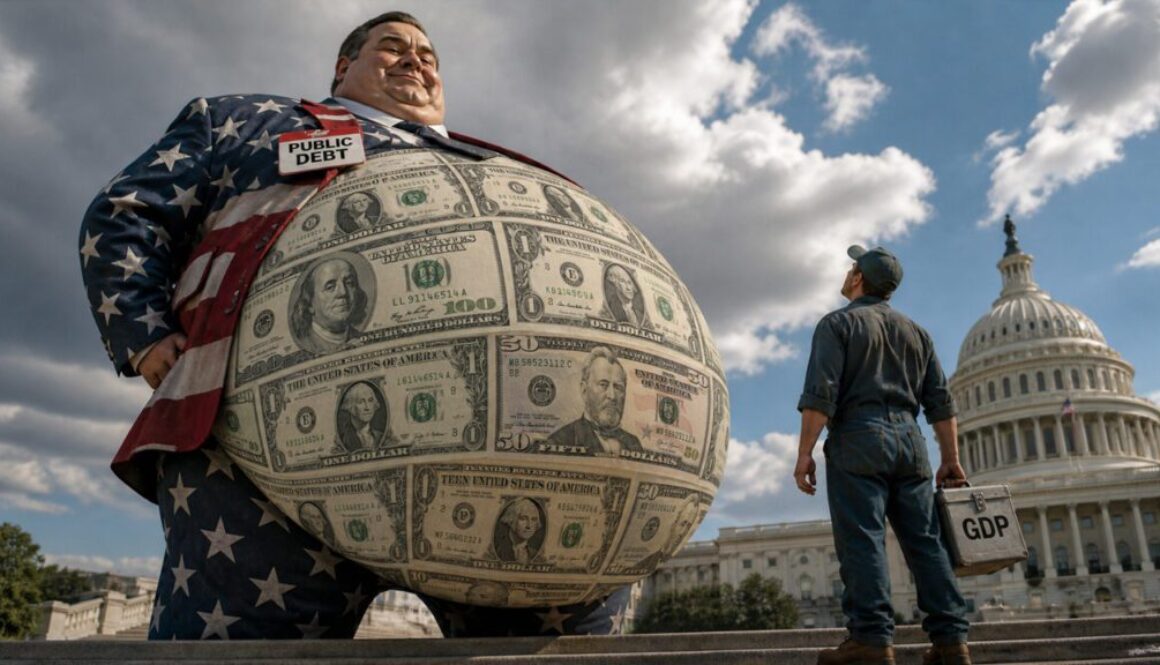
America’s $31.27 trillion in debt now exceeds GDP – silently reinforces the case for Bitcoin
U.S. public debt has exceeded the nation’s gross domestic product for the first time since World War II, crossing the 100% threshold at $31.27 trillion against $31.22 trillion in trailing annual GDP. For institutional investors evaluating Bitcoin and other scarce assets, the milestone transforms fiscal sustainability from an abstract concern into a concrete macro signal affecting how capital allocates between sovereign debt and alternative stores of value.
- U.S. public debt reached $31.27 trillion in Q1 2026, exceeding 12-month nominal GDP of $31.22 trillion by a 100.2% ratio
- The debt-to-GDP crossing marks the first such breach outside the early-COVID GDP crash since the end of World War II
- Bitcoin’s fixed supply of 21 million coins now offers institutional investors a direct monetary contrast to a fiscal system capable of unlimited debt issuance
- 100.2% Debt-to-GDP ratio, first crossing above parity since World War II era
- $31.27T U.S. public debt held by outside investors and non-government holders
- 20.02M Bitcoin circulating supply versus 21 million maximum cap, as of May 1
The Committee for a Responsible Federal Budget’s calculation marks a decisive fiscal inflection point that reshapes the macro case for non-sovereign, fixed-supply assets. When public debt held by external investors and non-government entities exceeds the total economic output of the nation issuing that debt, it signals a structural imbalance between fiscal commitments and growth capacity.
The U.S. Treasury market remains the global center of collateral and confidence, yet the 100.2% ratio now grounds investor conversations about fiscal credibility in numerical reality rather than forward-looking assumptions.
The timing compounds the signal’s weight. The Bureau of Economic Analysis reported that current-dollar GDP expanded 5.6% in the first quarter, yet debt growth has consistently outpaced nominal expansion.
This divergence means that without sustained economic acceleration or material fiscal consolidation, the ratio will widen further in subsequent quarters, moving the debate from a crossing into a trend.
CRFB’s debt measure clarifies which fiscal metric matters for Bitcoin comparison
The Committee for a Responsible Federal Budget’s use of debt held by the public, rather than total public debt outstanding, is methodologically essential for the Bitcoin analysis to hold institutional weight. The public-debt figure excludes intragovernmental holdings, capturing only the portion owed to outside investors, foreign governments, and non-government entities.
This distinction matters because those external holders represent the actual claimants on U.S. fiscal capacity, whereas intragovernmental debt is essentially internal accounting.
Treasury’s Debt to the Penny data, updated via API on March 31, separates these categories with precision. At that date, debt held by the public stood distinct from the larger total-debt figures often cited in political debate. When institutional investors model fiscal stress scenarios, they use the public-debt measure because it reflects real external claims on U.S. resources.
The 100.2% ratio thus carries different implications than a higher figure would, but it remains the economically accurate one for stress testing.
Historical context sharpens the significance. Outside the brief economic contraction in early COVID, debt held by the public had not exceeded annual GDP since 1946, the final year of World War II demobilization. That comparison transforms the 100.2% figure from a statistical anomaly into a marker of structural fiscal pressure comparable only to wartime finance.
The Treasury market’s continued dominance as global collateral does not negate the signal; it may even amplify it by concentrating global wealth concentration risk into a single sovereign issuer.
Bitcoin’s fixed 21 million supply now offers institutional hedge against fiscal expansion
Bitcoin’s supply schedule, approximately 20.02 million coins in circulation as of May 1, 2026, approaching the immutable 21 million maximum, provides the direct monetary contrast that makes the debt milestone relevant to crypto markets.
While the U.S. fiscal system can issue unlimited debt through congressional appropriation and Federal Reserve policy, Bitcoin’s protocol enforces a hard cap that cannot be exceeded or softened by political pressure.
Asset managers including BlackRock have framed this distinction in institutional terms: Bitcoin operates as a scarce, non-sovereign, decentralized alternative to sovereign balance-sheet risk. When debt-to-GDP ratios approach and exceed 100%, the marginal value of that scarcity increases because it offers investors an asset whose supply cannot respond to fiscal stress by expanding further.
This is not an argument that Bitcoin replaces Treasury bonds; it is an argument that Bitcoin may operate as insurance against the degradation of fiscal credibility at the margin.
The transmission mechanism operates through multiple channels. As debt ratios widen and investor confidence in fiscal sustainability weakens, capital seeking diversification beyond sovereign claims may allocate incrementally to fixed-supply assets. Treasury yields, Federal Reserve liquidity policy, volatility regimes, and overall risk appetite all condition whether those allocations materialize.
But the 100.2% debt-to-GDP threshold now supplies institutional investors with a concrete fiscal benchmark against which to model that allocation decision, rather than relying on theoretical or forward-looking arguments about Bitcoin’s monetary properties.
GDP revision scheduled for May 28 could alter the exact debt-to-GDP calculation
The Bureau of Economic Analysis’s first-quarter GDP release was an advance estimate, meaning the denominator in the debt-to-GDP ratio remains provisional. The preliminary data showed real GDP expanding at a 2.0% annualized pace and current-dollar GDP at 5.6%, but the next official revision is scheduled for May 28.
Depending on whether the BEA adjusts first-quarter output upward or downward, the precise ratio could shift above or below 100.2%.
This technical detail carries real institutional weight. If May’s revision produces higher nominal GDP, the ratio falls below 100% and alters the narrative framing; if GDP is revised lower, the ratio widens and reinforces fiscal pressure. Even fractional shifts in the denominator matter when trading and portfolio construction decisions operate at the margin.
The fiscal signal remains clear, debt is tracking at or above GDP, but institutional investors tracking this metric should expect the exact figure to move until final estimates are published later in the year.
The macro conversation around Bitcoin and scarce assets now pivots on whether institutional capital will actually reallocate into fixed-supply alternatives while Treasury yields, reserve conditions, and volatility continue to price the cost of holding non-yielding assets. The May 28 GDP revision will update the denominator; what remains open is whether the 100%+ debt-to-GDP threshold catalyzes material allocation shifts or remains a political talking point that fails to move institutional portfolio construction in real time.