BlackRock IBIT options expiration collides with Fed rate decision this week
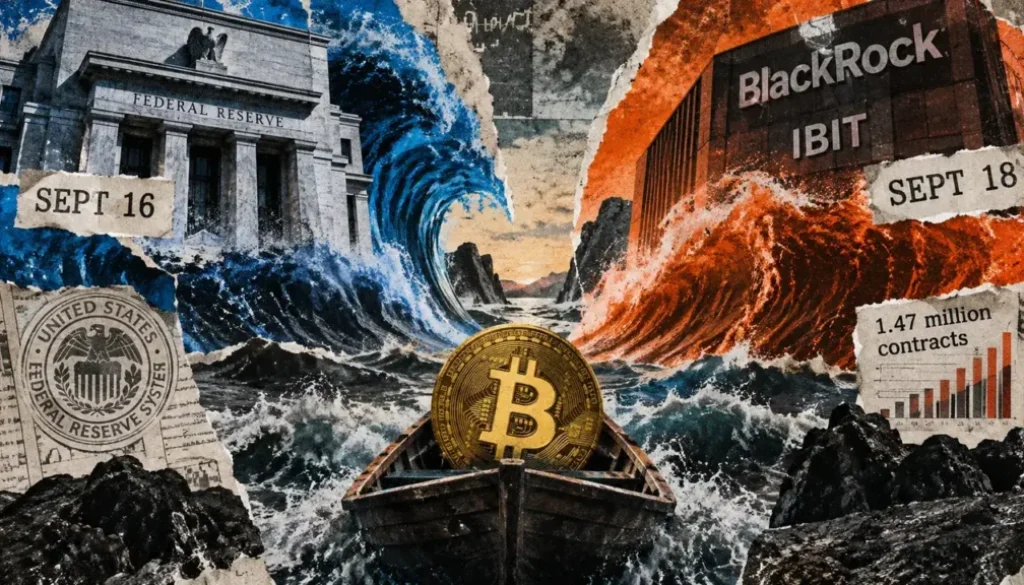
A $6.3 billion concentration of BlackRock iShares Bitcoin Trust options expiring Friday will test whether the Federal Reserve’s rate decision can move Bitcoin decisively or whether dealer hedging and position adjustments pull price back into crowded strike zones. The outcome carries direct consequences for leveraged traders and options desks deciding whether to unwind or roll positions ahead of settlement.
- 1.47 million IBIT options contracts expire Friday with 37.2% clustered between $40 and $45 strike prices
- The crowded $40, $45 strike band maps to roughly $70,900, $79,700 in Bitcoin equivalents, where current price sits in the middle
- Fed decision Wednesday at 2 p.m. ET followed by Powell’s press conference will test whether macro momentum can break through the expiry concentration
- $6.28B Gross underlying value represented by Sept. 18 IBIT options expiring this week
- 1.47M Total open contracts across IBIT’s Friday expiry, up from pre-May position limits of 250,000
- 37.2% Of all IBIT open interest crowded into $40, $45 strike range, per Cboe data
Bitcoin faces a compressed test of volatility and macro momentum as the Federal Reserve’s rate announcement lands Wednesday with options settlement just two days away, according to reporting by CryptoSlate. The Fed will deliver its policy statement and fresh economic projections at 2 p.m. ET Wednesday (September 17), followed by Chair Jerome Powell’s press conference. By Friday (September 19), about 1.47 million options contracts tied to BlackRock’s iShares Bitcoin Trust ETF will expire, with nearly 37% clustered in a narrow band where current price sits. That sequencing creates a visible test: will a Fed-driven move in Bitcoin overcome one of the largest single concentrations of options positioning in US-listed Bitcoin ETF markets, or will dealer hedging and position adjustments pull the market back toward those crowded strikes.
Fed decision and Powell press conference precede the options settlement wall
Bitcoin traded near $76,000 ahead of Wednesday’s announcement, placing it in the middle of the range implied by the most active IBIT strikes. The Fed’s decision and updated projections could reset expectations for rates, growth and inflation, resetting the macro backdrop that has increasingly driven Bitcoin alongside other risk assets during major policy events.
Any initial move from Washington will then collide with Friday’s expiry mechanics, introducing a separate source of positioning pressure independent of Fed reaction.
The distinction matters because IBIT options are physically settled, meaning exercised contracts deliver ETF shares rather than cash or Bitcoin.
$40, $45 strike zone holds 37% of open interest and maps to $70,900, $79,700 Bitcoin range
Cboe data showed 1,465,553 open contracts for IBIT’s September 18 expiry, comprising 833,070 calls and 632,483 puts. At an IBIT reference price of $42.87, that corresponds to roughly $6.28 billion of gross underlying share value.
The concentration is most useful for identifying where the market could become sensitive to price changes as the ETF moves through heavily populated strikes approaching expiry.
Roughly 545,861 contracts, or 37.2% of total open interest, were clustered between the $40 and $45 strikes, with the $45 strike carrying the largest individual position at 141,670 contracts and $40 holding 122,979.
Using the Coin Metrics Bitcoin benchmark at $75,961.76 and IBIT at $42.87 as a proportional mapping, the crowded $40-to-$45 IBIT range corresponds to Bitcoin prices of approximately $70,900 to $79,700. A static calculation of the current book found the lowest gross intrinsic value around an IBIT price of $41, mapping to roughly $72,650 in Bitcoin equivalents.
That $41 level should not be treated as a price target because the calculation excludes premiums, transaction costs, early exercise, position changes and information about who holds each side of the trade.
Position limit increase in May expanded capacity for concentrated bets in IBIT options
Cboe raised IBIT option position and exercise limits from 250,000 to 1 million contracts in May, allowing significantly larger same-side exposure than before. That expansion means the 1.47 million contracts now visible in the market represent a larger permissible concentration than would have been possible earlier in the year, amplifying the potential influence of position adjustments or settlement mechanics on Friday price action.
Market breaks above $79,700 or below $70,900 would signal Fed impulse overwhelmed the options setup
A sustained move outside the busiest IBIT strikes would suggest that the Fed impulse, spot demand, or broader risk positioning overwhelmed the expiry setup and left dealer hedging less influential. Bitcoin would need to hold above roughly $79,700 or below about $70,900 through Friday settlement for that scenario to be confirmed.
A sharp initial break followed by a return toward the $40-to-$45 IBIT zone would put expiry-related positioning back in focus, especially if open interest shifts as traders close or roll contracts.
For options desks, market makers and leveraged traders, the distinction carries immediate consequences: a Fed-driven breakout that persists could force rapid hedge adjustments outside the existing concentration, while a return toward the crowded strikes would leave Friday’s settlement mechanics more influential over short-term price discovery.
The CCS read. We see the options concentration as a map of sensitivity, not destiny. A Fed pivot lower could drive spot Bitcoin demand independent of dealer flows, while the limit expansion itself signals rising institutional conviction in Bitcoin options as a macro hedging tool, the more relevant story for allocators watching crypto-backed lending and structured products emerge.
By end of Friday, traders will have a clearer signal on whether Bitcoin can carry a macro catalyst through one of the largest ETF-options expiries now sitting directly in its path, and whether the doubling of position limits this spring translates into a new floor for institutional options flow or a volatility amplifier that reverses when positioning unwinds.