Offshore dated futures plunge 97% as Bitcoin options overtake contracts
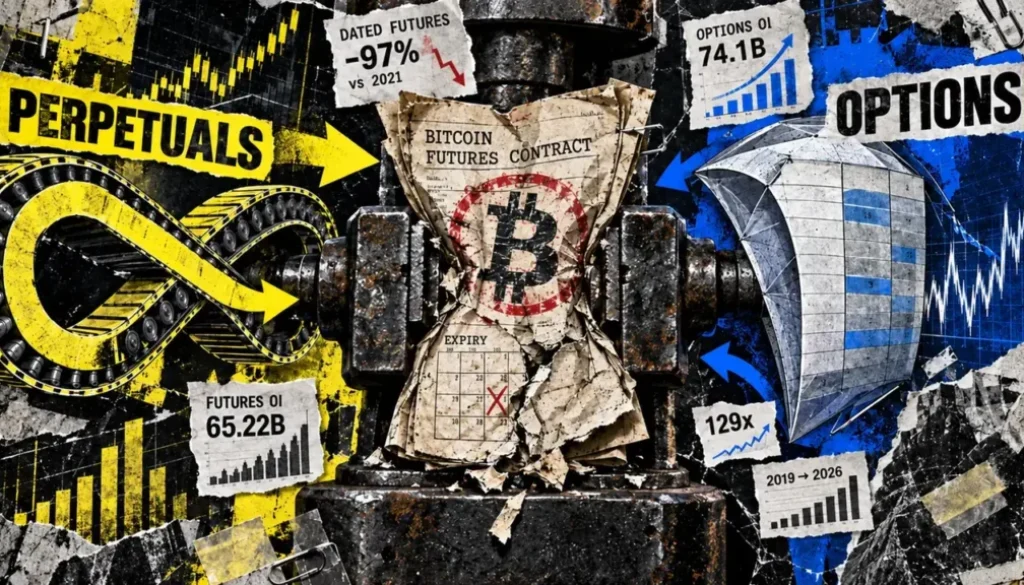
Dated Bitcoin futures volume on offshore, crypto-native exchanges has fallen 97% from its 2021 peak, according to Glassnode data, while options open interest overtook futures for the first time in January 2026. The shift shows that as institutional money has poured into Bitcoin through ETFs, corporate treasuries and structured desks, the market has built more precise tools for managing risk rather than simply betting on direction.
- Dated futures volume across offshore venues tracked by Glassnode sits roughly 97% below its 2021 level.
- Bitcoin options open interest reached about $74.1 billion in January 2026, overtaking futures’ $65.22 billion for the first recorded time.
- On September 18, 2026, Binance’s two main BTC perpetuals held $9.93 billion in open interest versus just $77 million in its dated contracts, a 129-to-1 gap.
- 97% drop in offshore dated futures volume since 2021’s peak
- $74.1B Bitcoin options open interest versus $65.22B in futures
- 129x Binance perpetual open interest over dated futures, Sept. 18
Bitcoin’s derivatives market has grown larger and more institutional over the past five years, yet one of the products that built it, the dated futures contract, has nearly vanished from crypto-native venues. Glassnode’s research, produced with Bybit and detailed in its derivatives report, shows options expanding from roughly a quarter to nearly half of crypto-native open interest, gaining share in four of five market regimes studied since 2019. CryptoSlate has tracked the pattern for years, detailed in its analysis of how the futures market split between perpetuals and options.
Options Open Interest Overtakes Futures for the First Time
The ratio between Bitcoin options and futures open interest had already been climbing for two years before it flipped. CryptoSlate recorded the options-to-futures ratio jumping from 57.8% to 69.6% in under a week in March 2025, well ahead of Ether’s equivalent figure.
By January 2026 options open interest reached $74.1 billion against $65.22 billion in futures, the first time options carried a larger position inventory than futures on the venues CryptoSlate tracks.
That flip did not happen because futures traders switched products overnight. It happened because the futures market itself split into two separate instruments serving different jobs.
Perpetual futures, which carry no expiry date and use funding payments to stay near spot price, absorbed the demand for straightforward leveraged directional exposure that dated futures once served.
Options absorbed the more complex work of hedging, volatility trading and downside protection, a shift tied to the growth of large, sticky Bitcoin holdings that entities such as ETFs and corporate treasuries intend to keep for years rather than trade actively.
Binance Snapshot Shows Perpetuals Outweighing Dated Contracts 129 to 1
A single-exchange snapshot from September 18, 2026, illustrates how far the preference for perpetuals has gone. At around 03:25 ET, Binance’s BTCUSDT perpetual carried about 108,289 BTC of open interest and its BTCUSDC perpetual another 19,465 BTC, together worth roughly $9.93 billion.
Binance’s two dated USD-margined contracts, expiring September 25 and December 25, 2026, carried only about $77 million combined. That puts perpetual open interest at roughly 129 times the size of the corresponding quarterly contracts on a single venue.
The mechanics explain the gap. A dated future forces a trader to settle, close or roll a position at expiry, work that a perpetual eliminates entirely as long as margin is maintained. Holders looking to protect existing Bitcoin positions without selling increasingly turn to options instead of either futures type.
Glassnode also found the market shifting from Bitcoin-margined collateral toward stablecoin and cash-like margin, separating a position’s losses from its collateral’s losses during selloffs, and Bybit’s tracked options volume share rose to 28% from below 10% as its book grew from $529 million to $2.33 billion.
CME Futures Still Anchor Institutional Basis Trades
Glassnode’s dated-futures figures cover offshore exchanges and explicitly exclude CME, a boundary that matters for institutional readers. Regulated asset managers, banks and basis traders still favor CME’s standardized contracts because they slot into existing clearing, compliance and collateral systems that offshore perpetuals cannot match.
Spot Bitcoin ETFs have made that institutional futures market more relevant, not less. Funds holding spot exposure can short CME futures against it, and basis traders can capture the spread when it covers financing costs.
The CCS read. We see this less as futures dying and more as liquidity sorting itself by user type: offshore perpetuals for leveraged retail and prop desks, options for institutions managing existing exposure, and CME for regulated capital doing basis trades. That separation should make it easier for compliance teams to justify derivatives exposure, since each venue now maps to a specific, auditable purpose rather than a single blended risk pool.
CryptoSlate’s data does not yet show whether CME’s own futures volumes are following the same trajectory as offshore venues, or whether the options-futures ratio holds above parity through the next major expiry cycle. Both questions will shape how regulators and institutional desks read Bitcoin’s derivatives market as it continues to mature.