After selling all its Bitcoin to pay off debt, AI firm tries to rebuild $827 million treasury from scratch
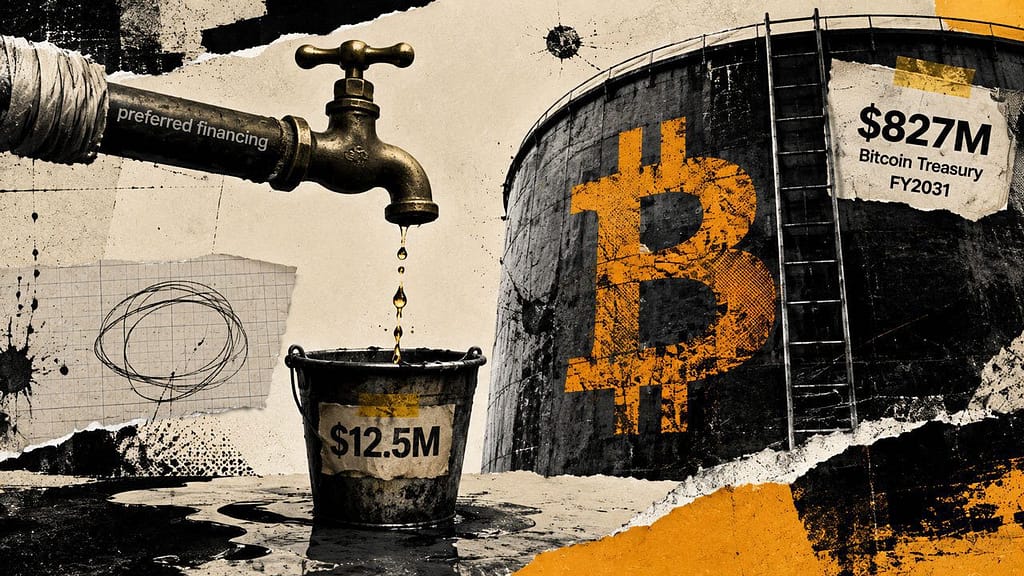
Genius Group, an AI education firm that liquidated its entire Bitcoin treasury to service debt, is now proposing a $12.5 million preferred stock offering to restart accumulation toward an $827 million Bitcoin target by fiscal 2031. The plan exposes a structural tension for corporate treasury strategies: companies using debt to fund crypto purchases risk forced selling into downturns, then face the challenge of rebuilding from zero in a competitive capital environment.
- Genius Group sold all Bitcoin holdings in April 2025 and repaid $8.5 million in debt, leaving it with $2.42 million cash.
- The proposed $12.5 million perpetual preferred offering would finance only 1.51% of the stated $827 million Bitcoin target by 2031.
- At current Bitcoin prices near $79,911, the company would need to acquire approximately 10,349 BTC over six years through multiple future capital raises.
- $827M Bitcoin treasury target by fiscal 2031 versus current zero holding
- $12.5M Initial preferred offering as percentage of total goal
- 156 BTC Equivalent value of first raise at current spot price
Genius Group’s Bitcoin treasury restart strategy highlights a critical risk in corporate crypto accumulation: the vulnerability of leveraged positions to forced liquidation. The company had previously held Bitcoin as a treasury asset but sold the entire position in April 2025 to repay $8.5 million in debt.
That forced exit, combined with a cash position that dropped to $2.42 million by year-end, placed the firm in the difficult position of rebuilding institutional crypto exposure from essentially zero while competing for capital against better-capitalized peers.
The proposed perpetual preferred stock offering of $12.5 million is structurally designed to avoid immediate common-share dilution by creating a non-convertible preferred instrument with monthly variable-rate dividends.
However, the company has not yet set the dividend rate, determined the final offering size, or specified the allocation split among the Bitcoin treasury, an AI portfolio, and a dollar reserve equal to approximately 18 months of preferred dividend obligations.
Those material terms remain subject to board approval, regulatory clearance, and market demand, leaving the actual Bitcoin purchase amount from this tranche still unquantified.
Genius Group’s April debt liquidation forces restart of corporate Bitcoin strategy
The sale of Genius Group’s Bitcoin holdings to service debt represents a worst-case execution scenario for corporate treasury managers: forced selling into market conditions where liquidity demands override price optimization.
In April 2025, the company liquidated its entire Bitcoin position to repay $8.5 million in obligations, a move that reflected balance-sheet stress rather than strategic reallocation.
The subsequent cash position, reported at $2.42 million in audited year-end filings and $106.6 million in unaudited net assets as of June, suggests the company has stabilized operationally but retains limited discretionary capital for aggressive Bitcoin accumulation.
Institutional investors monitoring corporate treasury strategies have noted a pattern: companies using debt to finance Bitcoin purchases are exposed to liquidity traps during downturns or earnings pressure. Genius Group’s experience exemplifies that risk.
The forced sale also created a credibility gap: the company now proposes to build a $827 million Bitcoin position by 2031 starting from zero, requiring sustained capital raises in a competitive fundraising environment where investor appetite for speculative corporate crypto treasuries remains selective.
The timing of the restart matters to institutional capital allocators. The company’s $1.2 billion shelf registration became effective in July 2025, which permits securities issuance over time but does not represent committed capital.
A prospectus supplement filed in April 2026 authorized an approximately $8 million public offering under the same registration, indicating Genius has already deployed part of that shelf capacity for equity or debt raises beyond the Bitcoin-specific preferred offering now under discussion.
$814.5 million funding gap requires multiple capital raises with no committed timeline
The arithmetic of Genius Group’s Bitcoin target reveals the scale of its capital challenge. At current Bitcoin prices near $79,911, the proposed $12.5 million preferred offering would purchase approximately 156 BTC, barely 1.5% of the stated goal.
Reaching the $827 million target (roughly 10,349 BTC in spot-price equivalents) by fiscal 2031 requires raising and deploying an additional $814.5 million, or approximately $136 million annually if distributed evenly across the six-year window. That pace far exceeds the company’s demonstrated fundraising capacity and assumes no material changes in Bitcoin’s valuation relative to the dollar target.
Genius Group has not disclosed a committed fundraising schedule, specific capital sources, or investor commitments beyond the current preferred offering. The company’s filing language emphasizes that each subsequent round “would depend on investor demand,” a formulation that acknowledges execution risk.
For institutional allocators, this signals that Genius Group’s Bitcoin accumulation is contingent on sustained market conditions favorable to equity and preferred issuance from mid-cap fintech and education companies, a narrower capital pool than the mega-cap tech firms or dedicated corporate treasury vehicles that have executed larger crypto purchases.
The preferred structure itself creates an intermediate obligation. Preferred holders will sit ahead of ordinary shareholders in dividend and liquidation claims, with monthly variable-rate distributions that the company has not yet calculated. If Genius raises multiple tranches of preferred stock, each with its own dividend obligation, the cost of capital for future Bitcoin purchases will compound.
The company will be servicing multiple layers of preferred dividends before deploying substantially larger amounts into Bitcoin itself.
Board approval and market conditions remain blocking points for initial offering launch
The $12.5 million perpetual preferred offering faces multiple unresolved approval gates before execution. Genius Group has not determined the issue price, final offering size, timing, or specific exchange listing.
Those terms remain contingent on board approval, compliance with securities regulations, and ultimately investor receptiveness to a perpetual preferred from a mid-cap company with a recent debt liquidation on its record.
The lack of pricing clarity means the exact Bitcoin equivalent of the first raise cannot yet be calculated, further muddying institutional investor visibility into the actual accumulation pace.
The perpetual structure, non-convertible, with variable monthly dividends but no maturity date, is unusual for most institutional investors. Traditional corporate preferred stocks carry defined maturity horizons; perpetuals blur the line between debt and equity, creating a hybrid liability that trades and reprices based on market conditions and issuer credit perception.
For Genius Group, a firm that was recently forced to liquidate Bitcoin to service ordinary debt, the market reception to a perpetual offering will signal whether institutional investors view the company’s treasury strategy as credible or speculative.
Regulatory clearance may also slow execution. The offering will require SEC review under standard prospectus rules; if the company pursues any listing on a major exchange, additional exchange approval and disclosure requirements apply.
Genius Group’s August 2025 update reported unaudited net assets but did not provide a current cash balance, a gap that may prompt SEC questions about financial reporting transparency before final approval of any securities offering.
The next concrete milestones are board approval of the preferred offering terms, SEC clearance of the prospectus, and market pricing: whether institutional investors demand a yield premium above standard preferred rates given Genius Group’s recent debt history. If the initial $12.5 million raises successfully and at favorable terms, the company has stated it intends to pursue additional capital rounds, but no timeline, target size, or investor commitments for subsequent tranches have been announced. Institutional investors should monitor Genius Group’s quarterly financial updates for cash position trends, any debt increases, and board commentary on the preferred offering’s reception, signals that will indicate whether the company can sustain the capital discipline required to fund $814.5 million in Bitcoin purchases without triggering another forced liquidation cycle.