Empery Digital Sells 1,635 Bitcoin As Treasury Buffer Shrinks
Empery Digital’s sale of 1,635 Bitcoin for $102.2 million signals a shift in how public companies deploy crypto treasuries as financial tools rather than indefinite reserves. Institutional investors must now distinguish between headline Bitcoin holdings and unrestricted assets, as collateral pledges and debt obligations increasingly constrain balance-sheet flexibility.
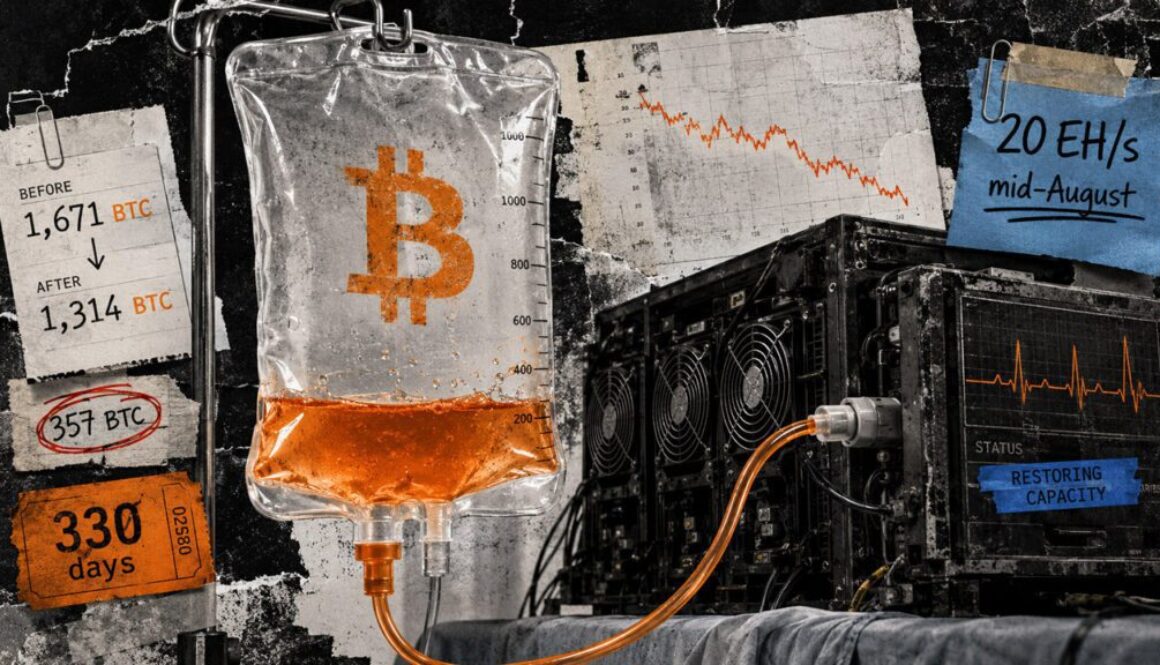
- Empery Digital sold 1,635 BTC for $102.2 million, reducing total holdings to 1,279 BTC as of August 7 filing.
- Only 325 BTC remained unrestricted; 954 BTC was pledged as collateral against debt obligations.
- The sale illustrates a broader shift: corporate Bitcoin treasuries now function as active balance-sheet tools, not static reserves.
- 1,279 BTC Total holdings after sale, down from prior period holdings
- 954 BTC Amount pledged as collateral, representing 75 percent of remaining total
- $102.2M Proceeds deployed toward debt repayment and share buybacks
Empery Digital Holdings disclosed in its Form 10-Q filing on August 7 that it had liquidated 1,635 Bitcoin to raise $102.2 million, using the proceeds to service debt and fund equity repurchases.
The transaction reduced the company’s total Bitcoin holdings to 1,279 BTC, but the filing’s most material detail for creditors and equity investors lies not in the headline count but in how that Bitcoin is encumbered. Of the remaining 1,279 BTC, only 325 BTC sits unrestricted on the balance sheet.
The other 954 BTC, representing 75 percent of holdings, has been pledged as collateral against existing debt obligations, sharply limiting the company’s practical treasury flexibility.
Empery Digital’s Pledged Bitcoin Reveals Hidden Leverage in Corporate Treasuries
The distinction between total Bitcoin holdings and unrestricted Bitcoin has become critical for institutional investors evaluating corporate crypto balance sheets. A company that owns 1,279 BTC but has pledged 954 BTC cannot deploy most of that collateral without triggering covenant breaches or forced liquidation.
This structure, using Bitcoin as security for financing, is increasingly common among companies that built crypto treasuries but face pressure to service debt or demonstrate financial stability to lenders.
Empery Digital’s capital structure exemplifies how Bitcoin moves beyond a simple buy-and-hold reserve into a multi-purpose financial instrument. The company used Bitcoin collateral to secure financing, then deployed the sale proceeds to reduce leverage and support shareholder returns.
This is rational capital management, but it also means Bitcoin holders should evaluate corporate crypto treasuries the way they would evaluate any leveraged asset: by understanding what portion is truly available for strategic use versus what is locked behind creditor claims.
For institutional investors, the filing underscores that headline Bitcoin counts no longer tell the full story. A company reporting “1,279 BTC held” without disclosure of encumbrance obligations could appear far more bullish on Bitcoin than its actual balance-sheet positioning warrants.
Transparency around collateral pledges, loan-to-value ratios, and liquidation thresholds has become essential due diligence for equity and debt investors.
Bitcoin Sale for Debt Repayment Shows Shift Away From Indefinite Accumulation
The $102.2 million liquidation demonstrates that corporate Bitcoin treasuries no longer operate under a uniform “never sell” philosophy. Empery Digital’s decision to convert BTC to fiat in order to repay obligations and repurchase equity reveals a calculus in which Bitcoin is treated as an active balance-sheet asset rather than a permanent reserve.
The company weighed the benefit of Bitcoin exposure against the cost of leverage and the return on capital represented by buybacks.
This marks a departure from the early narrative around corporate crypto treasuries, where companies like MicroStrategy and Tesla accumulated Bitcoin with minimal sale activity, signaling permanent conviction.
Empery Digital’s approach, tactical liquidation for balance-sheet management, is becoming more common as companies face lender pressure, covenant requirements, and shareholder demands for financial discipline. The proceeds also signal management’s view that reducing debt and supporting equity price were higher priorities than maintaining full Bitcoin exposure.
The decision reflects real-world tension between different stakeholder interests. Equity investors may value the deleverage and buyback support. Creditors may prefer the de-risking. Bitcoin-focused investors may view the sale as a loss of conviction or a sign of financial stress. All three perspectives are defensible; the transaction reveals which management prioritized first.
Corporate Bitcoin Strategies Diverge as Financing Structures Become More Complex
Empery Digital’s filing should not be read as evidence that all corporate Bitcoin treasuries are contracting or deprioritizing crypto assets. The broader category is fracturing into distinct strategies. Some companies continue accumulating without sale or pledge activity.
Others, like Empery Digital, use Bitcoin as collateral to optimize capital structures. Some have issued preferred stock or raised additional equity rather than pledging assets. Some sell tactically for balance-sheet flexibility; some hold regardless of financial pressure.
This divergence makes comparative analysis harder for institutional investors but also more necessary. A company’s Bitcoin strategy cannot be evaluated in isolation from its financing structure, leverage ratios, cash-generation profile, and management’s stated conviction on crypto assets.
Two companies with identical BTC holdings may have entirely different balance-sheet risk profiles depending on whether those holdings are free, pledged, or held subject to buyback obligations.
The institutional crypto investor community is moving away from simple metrics like “Bitcoin per share” or “total BTC held” toward more granular disclosure: unrestricted holdings, collateral haircuts, loan covenants tied to Bitcoin price movements, and management guidance on strategic intent. Empery Digital’s filing provides an early example of why that shift is necessary.
The company still holds over 1,000 BTC, a material position, but the practical available cushion is less than 325 BTC, a figure that materially changes how investors should model financial flexibility and risk.
Loan Covenants and Bitcoin Price Volatility Create New Risk Vectors
Companies that pledge Bitcoin against loans face an additional risk that traditional treasury managers do not: collateral haircuts and potential forced liquidation if BTC price falls below covenant thresholds. If a lender has advanced capital secured by Bitcoin at a 70 percent loan-to-value ratio, a 30 percent drop in BTC price could trigger margin calls or forced sales.
Empery Digital’s 954 pledged BTC sits at risk of this dynamic; the filing does not disclose the specific LTV ratios or price triggers at which the company would face forced liquidation.
This creates a feedback loop risk for highly leveraged corporate treasuries. If Bitcoin price declines and forces a company to liquidate collateral to meet margin calls, that liquidation itself puts further downward pressure on price, potentially triggering additional forced sales among other leveraged players.
Institutional investors holding equity or debt of companies with pledged Bitcoin should model these scenarios explicitly rather than assuming stable collateral positions.
Empery Digital’s sale at $102.2 million for 1,635 BTC implies an average price of approximately $62,500 per coin. At current and historical price levels, the remaining 954 pledged BTC would be worth roughly $59.7 million at that price.
If Bitcoin declines materially, that collateral base shrinks, increasing pressure on the company’s financing arrangements and potentially forcing additional asset sales.
Disclosure Standards Lag Behind Complexity of Corporate Bitcoin Structures
The SEC filing requirement for the 10-Q captured the sale and the current holdings count, but standard financial disclosure templates do not yet require detailed breakdown of collateral positions, LTV ratios, covenant triggers, or management’s forward guidance on Bitcoin strategy.
Equity and debt investors rely on footnotes and supplementary disclosures to extract these details, and not all companies provide them with equal clarity.
Empery Digital deserves credit for disclosing the restricted versus unrestricted split. Many companies bury this information or omit it entirely, leaving investors to infer encumbrance from debt covenants and loan agreements. As corporate Bitcoin treasuries become larger and more complex, institutional investors should demand explicit disclosure of collateral positions, financing terms, and management’s capital-