Investors just moved $7 billion into Bitcoin and gold in five days to escape an accelerating dollar crisis
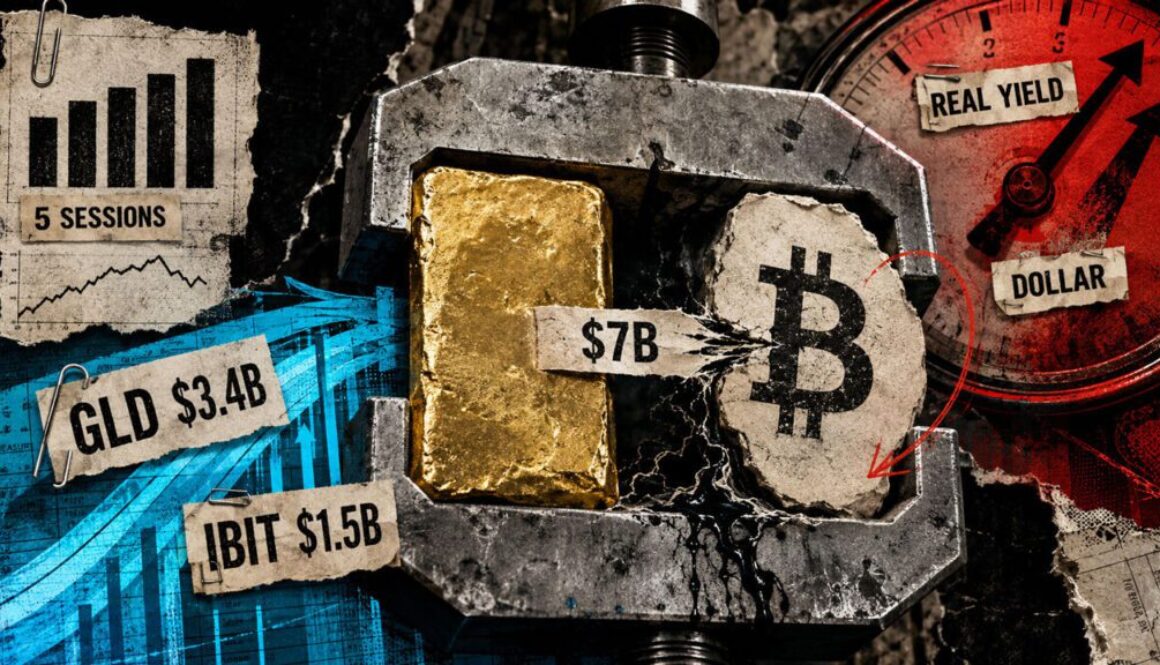
Institutional investors deployed $7 billion into gold and Bitcoin ETFs over five trading days, signaling a coordinated flight toward hard assets amid concerns over US fiscal deterioration and currency weakness. The synchronized inflow, concentrated in the two largest vehicles, GLD and IBIT, reflects a structural shift in how institutional portfolios are approaching inflation and debasement risk.
- $7 billion flowed into gold and Bitcoin ETFs in five US trading sessions, a combined record for both assets
- BlackRock’s iShares Bitcoin Trust (IBIT) and SPDR Gold Shares (GLD) together captured 70% of the inflow across their asset classes
- US public debt exceeded $40 trillion while Treasury doubled maximum liquidity-support buybacks to $4 billion per operation
- $7B Combined inflow into gold and Bitcoin ETFs in five consecutive trading sessions
- $40T+ US public debt level, exceeding previous thresholds during accelerated buying period
- 70% Share of total debasement-trade capital captured by GLD and IBIT combined
The five-day surge in gold and Bitcoin fund inflows represents the largest synchronized capital deployment into both assets simultaneously, according to Bloomberg Intelligence analysis.
Of the $7 billion total, approximately $3.4 billion entered SPDR Gold Shares (GLD), while BlackRock’s iShares Bitcoin Trust (IBIT) attracted roughly $1.5 billion, with the remainder distributed across other gold and Bitcoin vehicles.
Bitcoin rallied above $80,000 during this period, while gold broke through $4,600 per ounce, extending a correlated move that has increasingly positioned both as complementary inflation hedges within institutional allocation frameworks.
The concentration of capital in these two dominant vehicles underscores the institutional nature of the inflow. GLD manages more than $150 billion in assets, while IBIT holds around $60 billion, making each the dominant institutional access point for its respective market.
Bloomberg Intelligence analyst Eric Balchunas confirmed that IBIT ranked among the 10 biggest US ETFs by weekly inflows, alongside its gold counterpart. For Bitcoin specifically, the performance represented a recovery: IBIT’s year-to-date flows had returned to positive territory after earlier deficits, indicating renewed institutional confidence following a period of withdrawal.
Treasury’s Doubled Buyback Program Signals Fiscal Strain Driving Investor Rotation
The timing of the capital deployment coincided with monetary and fiscal policy signals that appear to have triggered the institutional pivot toward hard assets. On August 19, the US Treasury announced it would at least double the maximum size of its liquidity-support buyback operations for longer-dated securities to $4 billion per transaction.
This intervention, coupled with US public debt already exceeding $40 trillion, signaled to investors that traditional debt management tools were being strained. The Treasury’s action initially pulled long-term yields lower, but the broader signal, that fiscal authorities were managing mounting pressure, appears to have accelerated investor interest in assets uncorrelated to government liabilities.
Matt Hougan, Chief Investment Officer at Bitwise, articulated the underlying portfolio theory driving the shift. “A 60/40 portfolio is 100% exposed to fiat currency,” Hougan stated, pointing out that traditional institutional allocations, stocks and bonds, both derive their ultimate value from purchasing power denominated in dollars.
As fiscal uncertainty rises, even conservative institutional portfolios face implicit currency debasement risk with no structural hedge. Bitcoin and gold, by contrast, offer the only meaningful diversification for portfolios that would otherwise be fully exposed to the consequences of sustained fiscal deficits and monetary expansion.
Matt Cole, Chief Executive of Strive, framed the same dynamic through the lens of scarcity and capital flows. Cole argued that dollar debasement mechanically expands the pool of capital searching for limited-supply assets, and that Bitcoin’s continuing monetization, its gradual adoption as a store of value, allows it to capture a growing share of that demand relative to traditional alternatives.
This narrative has particular power for institutional investors managing multi-decade time horizons, as it repositions Bitcoin from a speculative asset to a structural hedge against a specific macroeconomic outcome: persistent deficits requiring either taxation, inflation, or financial repression to resolve.
Bitcoin and Gold Display Synchronized Technical Signals Unseen in Traditional Markets
Beyond the macroeconomic narrative, the capital inflow has coincided with technical convergence between Bitcoin and gold that is rarely observed in institutional markets. Charlie Morris, founder of ByteTree, highlighted that both assets currently carry identical technical readings: positively sloping 200-day moving averages and ByteTrend scores of 5, the firm’s strongest bullish signal.
This synchronization suggests that the inflow is not isolated to a single asset class or narrative, but reflects a broad institutional recalibration across multiple scarcity-based stores of value.
The dollar’s technical performance provides additional context for the timing. While the article notes the dollar has lost ground during this period, the simultaneous strength in both Bitcoin and gold suggests the move reflects more than simple currency depreciation mechanics.
Instead, it indicates that investors are actively rotating capital out of dollar-denominated assets into hard assets regardless of short-term currency movements. This distinction matters: a passive rotation driven by dollar weakness would typically show only modest Bitcoin strength and gold strength.
The scale of the inflow, $7 billion in five days into two ETFs alone, indicates active reallocation rather than passive currency arbitrage.
Bitcoin’s fixed supply of 21 million coins remains the structural foundation of its appeal in this trade, though the asset presents institutional investors with a clear tradeoff compared to gold. Bitcoin is substantially more volatile than gold and has less than two decades of history as a defensive holding.
Gold has millennia of precedent as a store of value and carries significantly lower volatility, making it more suitable for conservative institutional mandates. Yet the fact that institutional capital is flowing into both simultaneously suggests investors are accepting Bitcoin’s higher volatility in exchange for its superior scarcity and perceived monetization potential.
IBIT’s Recovery and GLD’s Dominance Reveal Institutional Appetite Reaching Scale
The $1.5 billion that flowed into IBIT during these five days reversed a year-to-date deficit and confirmed that institutional appetite for Bitcoin, channeled through the regulatory infrastructure of a spot ETF, has returned to positive momentum.
IBIT’s position among the top 10 US ETFs by weekly inflows is particularly significant given it only launched in January 2024. The vehicle has attracted roughly $60 billion in assets under management in less than a year, a velocity that suggests institutional on-ramps for Bitcoin exposure have finally reached sufficient liquidity and regulatory clarity to handle meaningful allocations.
The contrast with GLD, which manages $150 billion and has operated for two decades, illustrates both Bitcoin’s relative youth and its accelerating adoption rate among institutions managing scale.
Together, GLD and IBIT capturing 70% of the combined five-day inflow demonstrates that institutional capital seeking hard assets is concentrating in the largest, most liquid, most regulated access points rather than fragmenting across smaller competitors.
For institutions managing fiduciary mandates, this concentration matters. When 70% of a market movement flows through two vehicles, those vehicles become the de facto liquidity providers and price discovery mechanisms for their respective markets.
Inflows at this scale into IBIT will force BlackRock to accumulate Bitcoin in the secondary market or purchase directly, feeding price pressure and institutional adoption simultaneously. GLD’s $3.4 billion inflow similarly positions the fund as a major buyer of physical gold, supporting spot prices and mining dynamics globally.
What Happens When Fiscal Pressure Forces the Next Policy Move
The immediate question facing institutional investors is whether current inflows will persist if fiscal policy tightens or if Treasury intervention succeeds in stabilizing long-term rates without further debasement concerns. The five-day inflow was driven by a specific policy signal, the Treasury’s doubled buyback operation, combined with debt levels exceeding $40 trillion.
If that debt stabilizes, if yields hold without further intervention, or if political will emerges for deficit reduction, the debasement narrative could lose urgency among institutions that only recently revived it.
Conversely, if Treasury must intervene further, if long-term